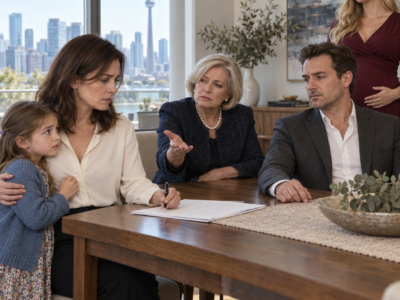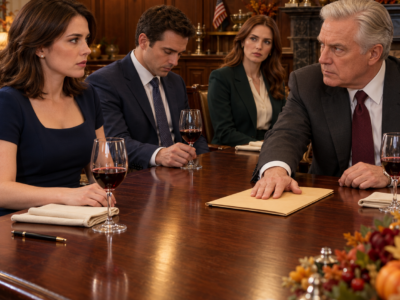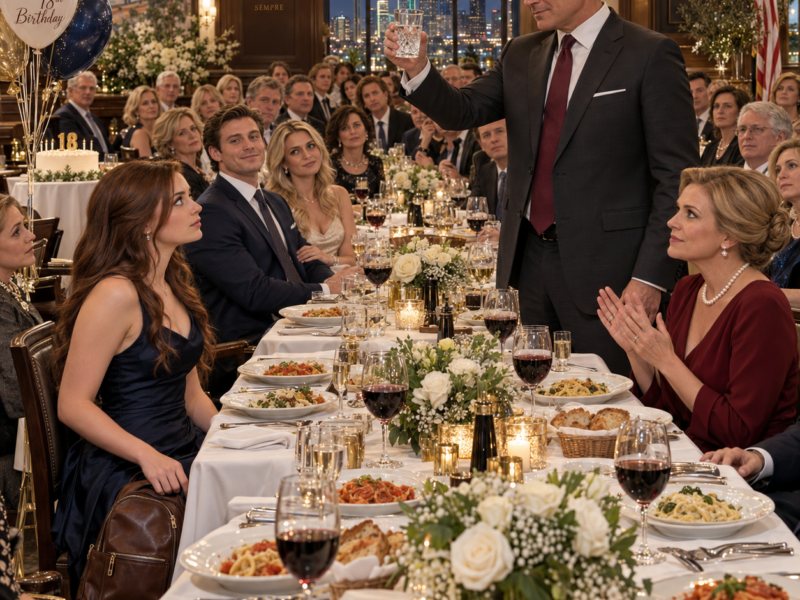
“We emptied your $224,000 college fund last year to save your brother’s marriage. Deal with it,” my father announced at my eighteenth birthday dinner, in front of thirty-two relatives. My mother started clapping. I took out the bank statement my grandfather had mailed me and slid it beside my father’s plate. He looked at the balance, then read it again. By the time he looked up at me, my mother had stopped clapping.
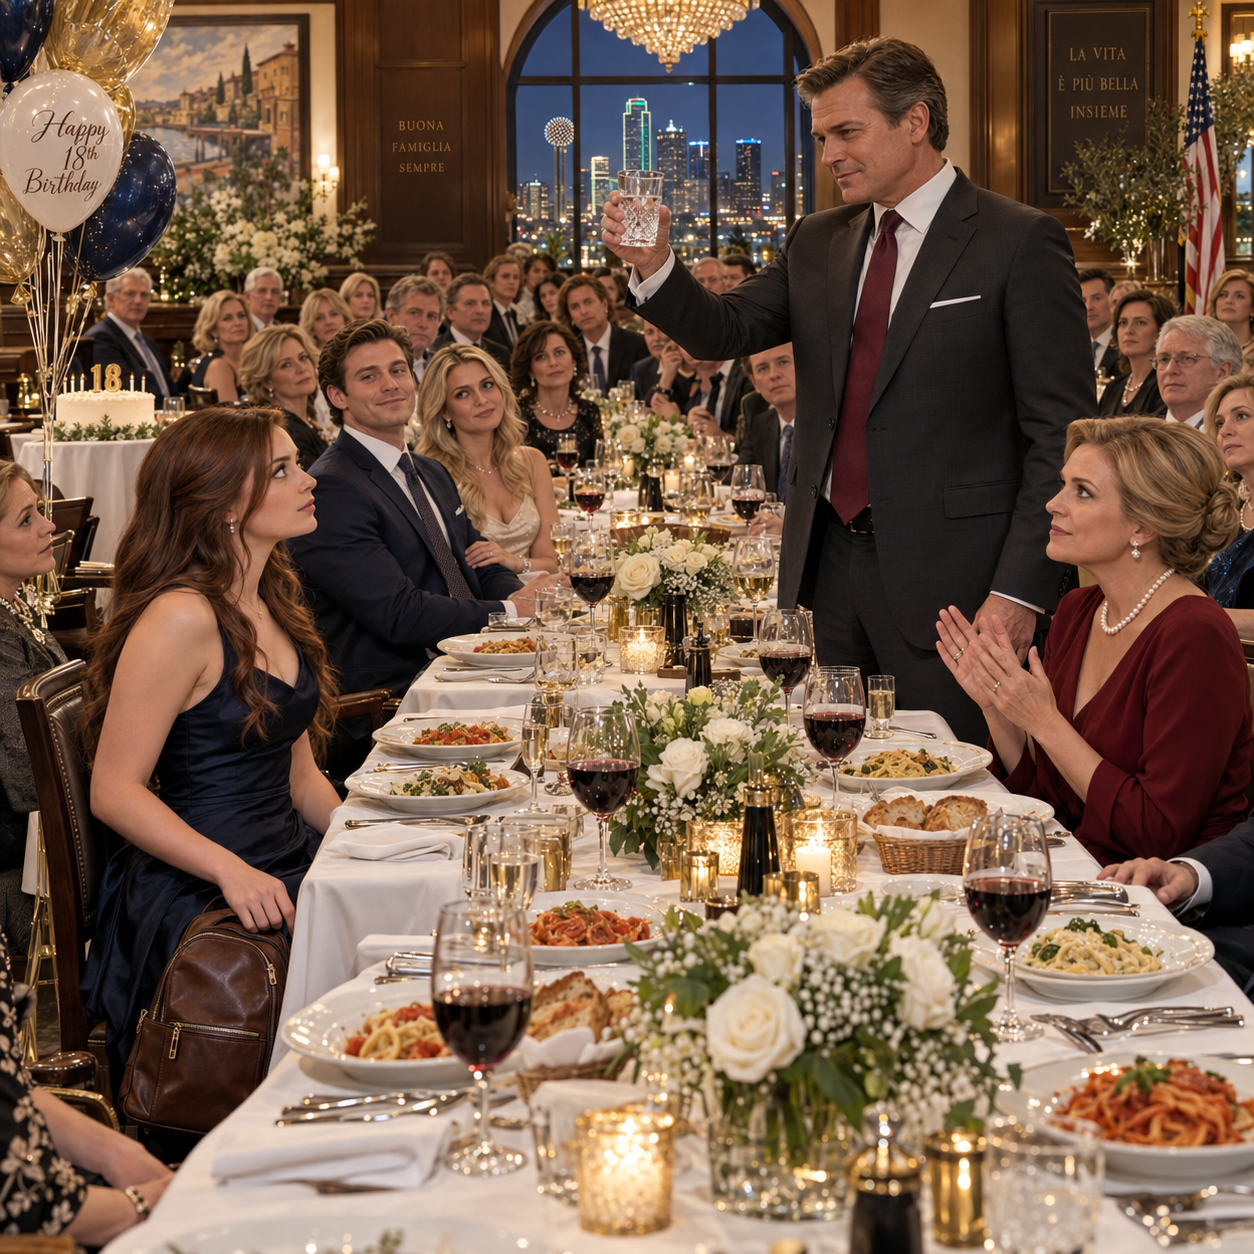
At my eighteenth birthday dinner, in front of thirty-two relatives, my father stood, raised his water glass, and announced that my parents had drained my $224,000 college fund to save my older brother’s marriage.
“We spent it last year,” he said. “Deal with it.”
My mother clapped.
I did not yell or cry. I reached into the leather backpack beside my chair, removed a bank statement my grandfather had mailed me eighteen days earlier, and slid it across the tablecloth until it stopped beside my father’s plate.
He looked at the balance.
Then he looked at the asset list beneath it.
The color left his face.
What my parents did not know was that Grandpa Harrison had never trusted them with my entire future. The money they took was real, but it was not everything he left me.
The statement showed $3,482,611 in an independent trust that became mine at eighteen.
It also showed full ownership of Harrison Retail Holdings, the company that owned Cedar Ridge Plaza, where my parents had operated their home-furnishings business for eleven years.
Their lease had expired three days earlier.
The private dining room at Bellini’s in downtown Dallas smelled of garlic butter, coffee, and the vanilla cake waiting on a side table. Blue and silver balloons tied to my chair brushed the ceiling whenever the air-conditioning started. My parents had arranged the dinner to celebrate my becoming an adult and leaving for college.
At least, that was what the invitation said.
I had learned to distrust family celebrations. In the Lawson family, cake often arrived beside an announcement designed to remind someone where they ranked.
My name is Avery Lawson. At eighteen, I was the younger of two children, an honors student with an acceptance letter from Rice University and a scholarship that covered less than half the cost. For as long as I could remember, my parents told me not to worry about the rest.
“Your college fund is secure,” my mother, Diane, said whenever financial-aid forms came up.
The fund began with money my maternal grandfather, Samuel Harrison, set aside when I was born. My parents added to it occasionally, and Grandpa contributed every year. By my junior year of high school, the quarterly statement showed $224,000.
Then statements stopped arriving.
When I asked, Dad said the bank had switched to electronic delivery. Mother said adults were handling it. Grandpa, whose health was failing, told me quietly that I should request a full accounting when I turned eighteen.
I did not understand why until my birthday dinner.
Directly across from me sat my brother Brandon, twenty-seven, wearing a navy blazer and a watch my parents gave him after his second attempt at starting a business. His wife, Jessica, rested one hand on his arm. A diamond necklace lay against the collar of her cream dress.
Their marriage had nearly ended the year before. Brandon concealed credit-card debt, unpaid payroll taxes from a failed restaurant, and a personal guarantee on equipment he returned damaged. Jessica discovered everything when a collection notice reached their home.
My parents said they were attending counseling.
Apparently, they were also using my education money to pay the debts.
Dad tapped his glass with a fork halfway through dinner. Conversations stopped.
Mark Lawson was fifty-five, broad-shouldered, and proud of being the person relatives called when something went wrong. He lent money, found contractors, negotiated car prices, and made every favor feel like proof that the family could not function without him.
“Before dessert,” he said, “we need to discuss Avery’s college expectations.”
My stomach tightened.
Mother smiled as though we were about to announce a surprise vacation.
Dad looked directly at me. “The college fund is gone. We used it last year to handle Brandon’s legal and financial problems so he and Jessica could keep their home and marriage together.”
The room went silent.
I heard plates moving in the restaurant kitchen beyond the closed doors.
“All of it?” I asked.
“All of it.”
“Without telling me?”
He crossed his arms. “You were a minor. We were the trustees.”
Mother began clapping, three bright little beats.
“Your brother’s family was in crisis,” she said. “College can be financed. A marriage cannot always be rebuilt.”
Brandon did not look up from his plate.
Jessica adjusted her necklace.
Several relatives appeared horrified. Others nodded because Dad had spent years teaching them that his decisions became family duty once announced.
“We drained your future to fix his mess,” Dad said. “Deal with it.”
He expected an emotional response. My mother had placed my birthday cake directly behind me, ensuring every relative would see my face. If I cried, they could call me selfish. If I shouted, they could call me immature. If I left, they could say I ruined my own birthday.
So I took a slow breath and reached for my backpack.
The document inside was not a magical check or a handwritten promise. It was a formal statement from First National Bank of Texas, trustee of the Samuel Harrison Grandchildren’s Trust. Grandpa had mailed it with a letter shortly before he died.
The trust was separate from the education account my parents controlled. He created it when I was twelve after discovering that Dad had borrowed from another family account without disclosing it. The bank served as independent trustee until my eighteenth birthday, when I became co-trustee with a professional fiduciary for five years. I could direct education and living distributions immediately, but major investment and property decisions required the co-trustee’s approval until I turned twenty-three.
Grandpa had designed independence with guardrails.
Samuel Harrison was not a sentimental man. He had built his first commercial property after thirty years as an electrician, saving enough to buy a neglected row of storefronts when Dallas expanded north. He repaired wiring himself, learned leases at night, and treated every tenant’s security deposit as if an auditor were watching.
He usually was the auditor.
When I was eight, Grandpa began taking me to Cedar Ridge on Saturday mornings. I carried a clipboard while he inspected gutters, parking-lot lights, and fire exits. At lunch we sat in a diner booth and added receipts with a calculator.
“Rent is not free money,” he told me. “The roof is borrowing from you every day. One morning it sends the bill.”
At ten, I asked why Mr. Patel paid less rent than the new phone store.
“Because his lease is older, he maintains his unit, and reliable tenants have value.”
“Couldn’t you charge him more?”
“Could and should are different words.”
Those lessons mattered later when relatives expected me to use the plaza as a weapon. Grandpa had never taught me that ownership meant domination. He taught me that control created duties before privileges.
His distrust of my parents did not appear suddenly. Dad had grown up poor and learned to equate money with safety. When he married Mother, he worked long hours, saved aggressively, and opened Lawson Home & Garden with a single rented showroom. Grandpa respected that discipline.
Trouble began when Dad’s success made him the financial center of the family. He paid Aunt Carol’s medical deductible and then told her where to live. He lent Uncle James money and expected a vote in every business decision. When Brandon needed his first car, Dad bought one more expensive than necessary and reminded him of it during every disagreement.
Generosity became leverage so gradually that recipients called it gratitude.
Grandpa refused the pattern. He charged my parents commercial rent, documented repairs, and declined to invest in Brandon’s restaurant without audited books. Dad interpreted each boundary as disrespect.
“Your grandfather trusts paperwork more than people,” he often said.
Grandpa answered once, “Good paperwork protects people when trust becomes convenient.”
I was fourteen and pretended not to hear. The sentence remained with me.
The independent trust originated after a different incident involving Brandon. He was twenty-one and wanted $90,000 to open a sports bar. Dad asked Grandpa to cosign. Grandpa requested a business plan. Brandon produced six pages copied from a franchise website.
When Grandpa refused, Dad withdrew $25,000 from a small account Grandpa had funded for household emergencies. He claimed he was entitled to use it because his name appeared as authorized signer. The bank processed the transfer. Grandpa forced repayment but did not sue.
Instead, he changed his estate plan.
“A bank allowing a transaction does not make the purpose honest,” he told me years later.
That sentence predicted the education-fund dispute exactly.
He did not tell me the size of the separate trust while I was a minor. He sent annual letters about budgeting, credit, and taxes. At sixteen, he gave me $1,000 to manage through a custodial brokerage account. I lost $83 on a company I selected because its product was popular online.
Grandpa made me write a one-page explanation.
“Are you angry?” I asked.
“No. Eighty-three dollars is inexpensive tuition if you learn not to confuse attention with value.”
At seventeen, I earned back the loss through diversified investments and a summer job. He praised the process, not the gain.
His final illness moved quickly. Pancreatic cancer reduced him from a broad man who walked every roof to someone who needed help crossing a room. My parents controlled visits, saying he tired easily. I later learned they argued with him about Cedar Ridge and the education fund.
Eighteen days before my birthday, a certified envelope arrived at Maya’s house rather than mine. Grandpa knew my parents opened mail.
Inside were the bank statement, trust summary, Margaret Ellis’s card, and a handwritten letter.
Avery,
If this reaches you, I may not be available to explain in person. Do not mistake the number on the statement for proof that life will be easy. Money solves some emergencies and creates others. Read before signing. Use professionals. Never punish a tenant to settle a family argument. Ask for an accounting of the education fund as soon as you are legally able.
Your parents may love you and still make decisions that harm you. These facts can exist together. Protection is not disrespect.
Grandpa
He died four days later.
At the funeral, Dad stood beside me and said Grandpa’s affairs were complicated, but adults would handle them. I already had the statement hidden in Maya’s mother’s safe.
I wanted to confront him that day. Margaret advised me to wait until my eighteenth birthday activated co-trustee status and until I could secure identification, records, and housing. Her advice felt cold. It was careful.
For two weeks, I attended graduation events, packed for college, and listened to my parents discuss dorm furniture while knowing something was wrong with the education account. I did not know the money was entirely gone. I suspected they had borrowed part.
That uncertainty was why I carried the statement to dinner.
Preparation did not make the announcement painless. It kept pain from making the next decision for me.
The current statement listed cash, bonds, diversified funds, and the membership interest in Harrison Retail Holdings LLC.
That company owned Cedar Ridge Plaza, a twelve-unit retail center in North Dallas. Lawson Home & Garden occupied its largest unit and warehouse.
My parents had always described Grandpa as their landlord. They did not know he transferred the LLC into my trust six months earlier. The bank managed it during his illness, and notice went to the business address Dad’s office manager handled. The store’s eleven-year lease expired on the fifteenth of June, three days before my birthday.
The bank had offered a six-month extension at market rent. Dad ignored it because he believed family ownership guaranteed that the store could remain under the old rate.
I slid the statement toward him.
“Grandpa asked me to give you this after you explained the college account,” I said.
That was not entirely true. Grandpa told me to protect myself and consult the bank. He did not stage the dinner. I had brought the statement because his final letter warned that Dad might reveal the missing education money only when he believed I had no alternative.
Dad picked up the pages with a dismissive expression. His eyes moved over the letterhead, the balance, and the asset schedule.
His hand stopped.
Mother leaned over his shoulder. The smile disappeared from her face.
“What is it?” Aunt Carol asked.
Dad did not answer.
Brandon finally looked up.
I took the statement back before anyone could damage it.
“Grandpa created a separate trust,” I said. “It owns Cedar Ridge Plaza. The bank sent your business a proposed lease extension six weeks ago.”
My father found his voice. “That property belongs to Harrison Holdings.”
“The trust owns Harrison Retail Holdings.”
“You are eighteen. You do not own commercial property.”
“The trust does. I am a beneficiary and co-trustee as of today.”
Mother’s chair scraped against the floor.
“Samuel would never do that without telling us.”
“He sent notice to the business address.”
Dad turned toward Brandon. “Did you see anything from First National?”
Brandon worked at the store as operations manager. His expression answered before he spoke.
“There were envelopes. I put them in your office.”
“When?”
“I don’t know. May?”
The room erupted into overlapping questions.
I raised one hand. “I am not doubling anyone’s rent tomorrow. I do not have unilateral authority to do that, and Texas law does not allow an owner to invent terms without notice. The bank’s property manager will contact you about a lawful extension or move-out schedule.”
Dad stared at me.
“You would evict your parents?”
“You just announced that you used my education trust without permission. I will not make any decision about your lease at this table.”
“That money was ours to manage.”
“Then you should be comfortable providing a full accounting.”
His face hardened. “This is family business.”
“No. One issue is a trust accounting. The other is a commercial lease. Both are documented.”
Mother began crying. Brandon said the trust was unfair. Jessica whispered that she had not known where the rescue money came from.
I stood, adjusted my jacket, and lifted my backpack.
“Avery, sit down,” Dad ordered.
“I have heard the announcement.”
“You are not leaving your own birthday dinner.”
“You made sure it was no longer a celebration.”
I thanked Aunt Carol for coming and walked out before the cake was cut.
The June heat hit me as soon as I stepped onto the sidewalk. Traffic moved along the wet street beneath restaurant lights. An American flag above the building entrance hung nearly still in the humid air.
I made it to my car before my hands began shaking.
Calm at the table had not meant I felt nothing. It meant I refused to let my family decide how my pain would be displayed.
I called Margaret Ellis, the trust officer whose number appeared in Grandpa’s letter.
“Are you safe?” she asked.
“Yes.”
“Do your parents have access to the statement?”
“No.”
“Do not sign a lease, withdrawal, loan, power of attorney, or settlement without counsel. Come to the bank at nine tomorrow. Bring identification and every record you have regarding the education fund.”
“Can they take the new trust too?”
“Not lawfully. The bank retains joint authority over principal until you are twenty-three. That protection is exactly why your grandfather selected this structure.”
For the first time that night, I breathed fully.
I did not return to my parents’ house. My friend Maya and her mother let me sleep in their guest room. Dad called fourteen times. Mother sent messages alternating between apology and accusation.
You misunderstood.
We sacrificed for the whole family.
Your grandfather poisoned you against us.
Brandon will lose his home because of you.
The final message came after midnight.
If you involve lawyers, do not expect to live under our roof.
I saved every message.
At First National the next morning, Margaret Ellis introduced me to trust counsel Rebecca Shaw and property manager Luis Mendoza. They explained the documents page by page.
The $3.48 million was not spending money. About $1.6 million consisted of the appraised equity in Cedar Ridge Plaza. The rest was invested to support education, reasonable living expenses, and long-term security. Taxes, maintenance, insurance, and reserves reduced available income.
“A trust balance is not a checking-account balance,” Margaret said. “Your grandfather did not intend you to become a teenager with unrestricted millions. He intended you to have options and learn stewardship.”
The distinction steadied me. I did not want a revenge fantasy. I wanted college, housing, and protection from adults who believed my future was available for redistribution.
Rebecca reviewed the education fund documents. It was a separate irrevocable trust created for my benefit, with my parents serving as co-trustees. Distributions were limited to my education, health, maintenance, and support. Transfers to Brandon were not authorized.
“How did they withdraw it?” I asked.
“We need statements from the brokerage and receiving accounts. At first review, it appears they liquidated investments and described the transfer as a beneficiary support distribution. That representation may have been false.”
“Can the money be recovered?”
“Some or all, depending on tracing, available assets, defenses, and litigation. We do not promise outcomes before investigation.”
The property issue was clearer. Lawson Home & Garden remained in possession after lease expiration. Cedar Ridge could accept temporary rent while negotiating a new lease, provide proper notice to vacate, or pursue a holdover remedy if the business refused. Any rent change had to be reasonable, documented, and consistent with market evidence.
Grandpa’s trust required decisions benefiting me, not punishing tenants.
“What is current market rent?” I asked.
Luis opened an appraisal. My parents paid $14.50 per square foot under a lease signed eleven years earlier. Comparable large retail space ranged from $23 to $27, though their unit needed roof and loading-dock work.
The bank proposed $21.75 in year one, rising gradually, with shared improvement costs.
It was a significant increase, not an arbitrary doubling.
“Did Dad receive this?”
“Certified mail was accepted by Brandon Lawson,” Luis said. “Email copies went to the company address. No one responded.”
Brandon had known enough to sign for the notices and careless enough not to read them.
I authorized Rebecca to demand a trust accounting and preserve records. As co-trustee, I approved continuing lease negotiations through Luis. I did not call my family.
They arrived at the bank anyway.
Dad entered the lobby with Mother and Brandon shortly after noon. Security stopped them from reaching the private offices.
Margaret asked whether I wanted to see them.
“With Rebecca present.”
We met in a conference room. Dad placed both hands on the table.
“You will tell the bank this is a misunderstanding.”
Rebecca spoke. “Mr. Lawson, Avery is represented regarding the education trust and her interests in the Harrison trust. Direct requests should come through counsel.”
“She is my daughter.”
“She is also an adult beneficiary and co-trustee.”
Mother turned to me. “We paid for eighteen years of your life.”
“That did not authorize using a restricted education trust for Brandon.”
Brandon leaned forward. “You would rather hoard money than keep my family together?”
“Your marriage was never my financial obligation.”
“I was going to pay it back.”
“How much have you repaid?”
He looked at Dad.
“That is not the point.”
“It is one of the points.”
Dad said the brokerage allowed the withdrawal, which proved it was legal. Rebecca explained that institutions rely on trustee certifications; processing a transaction does not excuse a trustee’s misuse.
“Are you accusing us of a crime?” Mother asked.
“We are requesting records and an accounting,” Rebecca said. “Legal conclusions follow evidence.”
My parents had used accusations to control conversations all my life. Rebecca refused to accept their framing.
Dad changed tactics.
“Avery, come home. We will work this out privately. You can attend community college for two years, then transfer. There is no reason to destroy your brother.”
I thought of the Rice acceptance letter taped inside my bedroom closet.
“I am attending the school I chose if the financial plan is responsible.”
“With Grandpa’s money.”
“With scholarship aid and trust distributions created for education.”
“You sound ungrateful.”
“I am grateful to Grandpa. Gratitude does not belong to whoever happens to demand it.”
The meeting ended.
That afternoon, my parents changed the locks at home and told relatives I had abandoned them. Maya’s mother helped me retrieve clothes, school records, and my laptop with a police standby. I took only what was mine.
My room looked smaller than it had the day before. Birthday gifts sat unopened on the desk. The framed photograph of Grandpa and me at a Texas Rangers game was gone.
Mother stood in the hallway.
“He turned you against us.”
“Grandpa gave me documents. You gave me the reason to use them.”
She did not answer.
I found the photograph inside a kitchen drawer before leaving.
For three weeks, attorneys traced the $224,000. The records showed that my parents liquidated the fund in four transfers. One paid $61,000 in Brandon’s payroll-tax obligations. Another paid $48,000 in credit-card settlements. A third supplied $85,000 toward refinancing his house. The final $30,000 went to my parents’ business account, then covered legal fees and personal expenses.
The forensic accountant, Celia Grant, explained tracing in language I could understand. Money does not retain a physical label after entering a mixed account, but dates, amounts, wire instructions, and subsequent payments can establish paths.
We sat in her office before a wall of screens displaying spreadsheets.
“Your parents moved the first distribution into their joint account,” she said. “Within twenty-four hours, nearly the same amount went to the IRS under Brandon’s tax identification number. The second distribution moved through the business account, then to three card settlements.”
“Why move it through the business?”
“Possibly convenience. Possibly to make it look like a company loan. We determine what records support, not what looks dramatic.”
The third transfer funded Brandon’s mortgage refinance through an escrow company. He signed a statement calling the $85,000 a gift from his parents. That representation was true from his perspective only if the money legally belonged to them.
“Did the title company do something wrong?” I asked.
“It verified the gift letter, not the source behind your parents’ account. Financial systems divide responsibility. Misconduct often crosses the gaps.”
The final $30,000 was harder. It paid my parents’ attorney, a family vacation charged as a business retreat, and inventory invoices. Dad argued that stabilizing the store supported me because its income paid household expenses.
Rebecca rejected the logic.
“A trustee cannot take restricted beneficiary funds for personal business needs and later invent indirect benefit,” she said. “If emergency support for Avery were necessary, the trust required records showing a distribution for Avery.”
There were none.
The brokerage’s role was uncomfortable too. A service representative noticed the unusually large liquidation and asked Dad whether it served my education. He checked a box marked “beneficiary support” and wrote “family educational stability” in a notes field. No one requested invoices or contacted the trust’s drafting attorney.
The institution had not planned the misuse, but its weak verification made it easier. After negotiation, its insurer contributed to fees and enhanced the restoration amount. The brokerage also changed review procedures for custodial and education trusts.
Learning this changed my idea of wrongdoing. I had imagined one theft at a table. In reality, the loss passed through many ordinary systems, each person seeing too little or asking too little.
Celia prepared a timeline for mediation. Four transfers, seven receiving accounts, eleven major payments. No shouting was necessary. The dates spoke clearly.
Dad attacked her report because it included the family vacation.
“Avery came with us,” he said.
I had spent that week sleeping on a sofa in a rental house while Brandon and Jessica used the second bedroom. I was sixteen. Dad now claimed the trip justified taking $7,800 from a college fund two years later.
The mediator asked him whether any trustee resolution authorized it.
He said families did not operate through resolutions.
Rebecca placed the trust document in front of him.
“Trustees do.”
That distinction became the center of the case. Dad wanted every role reduced to family: father, son, sister, daughter. Legal duties existed precisely because family affection can distort judgment.
Mother’s participation was harder to measure emotionally. Her signature appeared on each trustee certification. In deposition, she said Dad placed pages in front of her and told her where to sign.
“Did you read them?” Rebecca asked.
“Not closely.”
“Did you understand you were a trustee for Avery?”
“Yes.”
“Did you know the money went to Brandon?”
“Yes.”
“Then what did you believe your signature meant?”
Mother began crying.
Her tears did not alter the answer. Passivity can breach a duty as surely as action.
I watched the recorded deposition once. Seeing her frightened and evasive did not satisfy me. It showed how dependency becomes complicity. She had spent decades letting Dad make decisions, then used his authority as an excuse when consequences arrived.
The settlement required both parents to complete basic fiduciary training before serving in any future family trust. They considered the requirement insulting. I considered it overdue.
Brandon and Jessica received the benefit, but my parents made the trustee certifications.
Jessica retained her own lawyer. She told investigators she believed Dad used a business line of credit and that Brandon described the money as an advance on future inheritance.
Brandon had lied to her too.
Their marriage did not suddenly heal because the debt disappeared. Removing financial pressure exposed the dishonesty underneath it.
Jessica moved to her sister’s home and filed for legal separation.
Dad blamed me.
“If you had kept this private, Jessica would never have known,” he said in a voicemail.
The sentence revealed the family rule more clearly than any confession. Saving a marriage meant hiding the truth long enough that the person most affected could not choose.
Rebecca filed a civil action seeking an accounting, removal of my parents as trustees, restoration of funds, and damages permitted under Texas law. We did not demand their arrest or issue public accusations. The brokerage froze remaining trust-related accounts after receiving the complaint.
My parents hired an attorney named Dennis Crowe, who argued the payments supported me indirectly by preserving family stability. He claimed that as a minor living at home, my welfare depended on Brandon’s marriage and the family business.
The argument was creative and weak.
The trust language named education, health, maintenance, and support for me. It did not allow hundreds of thousands of dollars to pay an adult sibling’s tax debt.
The court removed my parents as trustees on an interim basis and appointed the bank pending final resolution. Dad described the order online as a technicality.
At Cedar Ridge Plaza, lease negotiations became another battlefield. Dad refused the bank’s proposal and continued paying the old monthly amount. The property company accepted payments only as use and occupancy charges, with written reservation of rights.
Luis commissioned repairs, documented market rent, and offered mediation. Dad rejected all three meeting dates.
“He thinks you will order us to surrender,” Luis told me.
“Can I?”
“You can recommend. The professional co-trustee must agree while you are under twenty-three. More importantly, the decision must serve the trust, not family anger.”
“What serves it?”
“A solvent tenant at market rent if the tenant complies. A replacement tenant if not. Right now, Lawson Home & Garden’s financial condition is unclear.”
The store employed twenty-six people. Some had known me since childhood. Evicting the business impulsively would harm people who had no role in the missing college money.
I asked the bank to offer one final lease with transparent financial disclosure, a five-year term, gradual rent increases, and a cure period for arrears. The offer prohibited subleasing to Brandon’s ventures without approval.
Dad called it extortion.
The bank began a lawful eviction action when he refused.
That filing finally forced disclosure of the store’s books. Lawson Home & Garden had strong sales but poor cash control. Dad paid Brandon a senior manager’s salary despite repeated losses. Family vehicles, restaurant meals, and personal travel ran through business accounts. Inventory records were unreliable.
The store could afford the proposed rent if expenses were corrected.
Employees learned about the dispute when a process server delivered papers. Rumors said I intended to close the plaza and sell it to developers. I asked Luis to organize a tenant meeting but did not attend at first. At eighteen, appearing as a teenage owner could turn a lease dispute into spectacle.
Margaret Ellis disagreed.
“You do not need to manage the property alone,” she said. “But stewardship includes facing people affected by decisions.”
I attended with Rebecca and Luis.
Shop owners filled a vacant unit with folding chairs. A dry cleaner asked whether rents would double. A bakery owner worried about redevelopment. I explained that current leases would be honored, market studies would guide renewals, and no sale was planned.
One woman asked why my parents’ store faced eviction.
“Because its lease expired and management declined the proposed renewal and mediation,” Luis answered.
“Is this punishment over family money?”
“No,” I said. “The education-trust case is separate. Cedar Ridge must treat every tenant consistently. My parents have the same right to negotiate, accept, reject, or contest as any business.”
The answer did not satisfy everyone. It was true.
Afterward, a hardware-store owner named Mr. Patel approached me.
“Your grandfather raised rent twice in twenty years,” he said.
“The current leases remain in force.”
“I know. I’m saying he cared whether we survived.”
“So do I.”
“Then learn the property before you change it.”
I took his advice.
Throughout the summer, I spent two afternoons a week with Luis learning leases, roof reserves, property taxes, insurance, maintenance schedules, and tenant improvements. Commercial ownership was not collecting checks. A parking-lot drainage repair cost $74,000. Two air-conditioning units failed in August. The plaza’s large sign needed electrical work.
The trust balance looked enormous until responsibilities acquired numbers.
I also prepared for college. Rice adjusted my aid after the family financial change and my independent housing circumstances. The trust approved tuition, a dorm room, books, health insurance, and a modest monthly allowance.
Margaret rejected my request for a new car.
“The vehicle you own is safe and functional,” she said.
“The trust has millions.”
“And your grandfather required prudent distributions.”
I was annoyed for a day, then grateful. Grandpa had protected me not only from my parents, but from becoming an impulsive eighteen-year-old with access to unrestricted wealth.
I drove my six-year-old Honda to Houston.
College gave me distance. I studied economics and accounting, worked ten hours a week in the library, and avoided telling classmates about the trust. I wanted friends who knew me before they knew the balance.
My first roommate, Lila Chen, believed I received generous need-based aid. I did not correct her immediately. Secrecy felt safer than explaining why someone with millions in trust assets drove an old Honda and compared cafeteria prices.
The truth emerged when a financial-aid form required additional trust documentation. Lila found me crying over tax schedules at our desk.
“Is someone sick?” she asked.
“No. I have a trust.”
She waited for the rest.
“A large one.”
“Are you in trouble?”
“I don’t know how to tell people without becoming the money.”
Lila closed the door.
“You can start by telling me whether you want tea.”
Her lack of fascination taught me that healthy relationships do not demand complete disclosure on a schedule. I told her the broad outline. She never asked the balance.
We remained friends through college and adulthood.
Other lessons were less gentle. A classmate learned about Cedar Ridge through a public record and suddenly invited me to invest in a clothing app. A student organization suggested I sponsor an event after I declined a committee role. One boyfriend joked that marrying me would solve graduate-school debt.
I became suspicious of every request.
The campus counselor challenged that response.
“Your parents treated access to money as access to you,” she said. “Now you assume everyone who needs something wants control. Can you evaluate requests without assigning motives first?”
We created questions. Was the request clear? Could I decline safely? Did the person offer information? Was the relationship balanced outside money? Would I make the same choice for someone whose approval I did not need?
Those questions helped me give without returning to fear.
I donated small amounts anonymously to campus emergency aid. I lent no money to friends. When Lila’s mother needed surgery, I offered rides and meals, not a check she had not requested. Boundaries allowed generosity to feel voluntary.
Academically, I struggled with a first-semester statistics course despite having been the strongest math student in high school. My instinct was to hide the grade. Grandpa’s letter reminded me that money created no exemption from ordinary failure.
I attended office hours, joined a study group, and earned a B.
Dad would have called that disappointing. I considered it honest work.
Summers brought me back to Dallas for property training. Luis started me with tenant files and maintenance tickets, not investment strategy. I learned which bakery drain clogged repeatedly and why one roof section aged faster. I shadowed the janitorial crew at five in the morning and understood how much ownership depended on labor that statements call operating expense.
Mr. Patel made me work one Saturday at the hardware counter.
“If you raise rent,” he said, “you should know how many boxes of screws pay it.”
By closing time, my feet hurt and I had given incorrect directions to plumbing fittings twice.
“How many?” I asked.
“Too many,” he said. “That’s the lesson.”
I did not freeze rents forever. Property taxes, insurance, and repairs rose. We created predictable increases and longer notice periods so local tenants could plan.
At twenty-one, I proposed converting two vacant units into a national pharmacy. The lease offered strong credit but required exclusivity that could harm the independent medical-supply store. Luis asked me to model both direct rent and tenant impact.
I withdrew the proposal and recruited a regional bookstore instead. Its rent was lower, but customer traffic helped the bakery and café.
Stewardship meant measuring value beyond the largest immediate check.
The trust also forced me to confront privilege. Most students harmed by family finances could not hire Rebecca, rely on a professional trustee, or sleep in a friend’s safe home. My careful response was possible because Grandpa supplied resources.
That did not make my parents’ betrayal acceptable. It made my recovery unusually supported.
I stopped describing myself as self-made. No one is.
The lawsuit continued through my first semester. My parents produced incomplete statements and claimed records were lost. Subpoenas to banks reconstructed the transfers. Dennis Crowe advised settlement after a forensic accountant confirmed the path of funds.
The proposed settlement required my parents and Brandon to restore $224,000 plus a portion of lost investment growth, legal fees, and accounting costs. They did not have enough cash.
Dad offered his house as collateral. Mother offered jewelry. Brandon offered nothing at first.
“He received most of the benefit,” I told Rebecca.
“Benefit does not automatically equal trustee liability,” she said. “But if he knew the source and participated, claims may exist. Evidence is mixed.”
Text messages changed that.
In one exchange, Brandon asked Dad whether “Avery’s school pile” could cover the tax lien. Dad replied that I had scholarships and would “never know until it no longer mattered.” Brandon responded with a thumbs-up symbol.
He knew.
Jessica provided the messages from a shared tablet during financial discovery in their separation.
Brandon was added to the settlement negotiations.
At mediation, my family sat across a long conference table. It was the first time we had occupied one room since my birthday.
Dad looked tired. Mother wore pearls as if formality could restore authority. Brandon stared at his phone.
The mediator separated us for most of the day. Offers traveled between rooms. My parents wanted me to forgive the debt in exchange for peace. I wanted a judgment or secured repayment that did not destroy the store’s employees.
We reached an agreement after eleven hours.
My parents acknowledged breach of fiduciary duty without admitting criminal intent. They transferred a $140,000 secured note to the education trust, backed by equity in their home. Brandon signed an $84,000 repayment agreement tied to his income and sale of a boat and recreational vehicle. Insurance from the brokerage covered part of professional fees after its own review identified verification failures.
Lost growth and remaining costs were allocated under a structured settlement.
No one walked away happy. That was one sign the compromise reflected reality.
The agreement did not send my family to prison, make me instantly whole, or erase taxes created by liquidation. It created enforceable responsibility and preserved enough stability for repayment.
The commercial lease settled separately. Lawson Home & Garden accepted the bank’s five-year proposal with an added requirement for quarterly financial reporting during the first two years. Dad reduced personal expenses. Brandon left the store as a condition of the business lender’s renewal.
Twenty-six employees kept their jobs.
At the lease signing, Dad refused to look at me.
Luis placed documents in front of each party. The bank’s officer signed for the trust because I was a co-trustee with limited unilateral authority.
“Your grandfather would be ashamed,” Dad said as he capped his pen.
“He wrote the structure we are following.”
“He never expected you to use it against us.”
“Protection feels like an attack only when someone expected access.”
Rebecca touched my arm, signaling that the meeting was complete.
The first repayment arrived the following month.
My parents did not speak to me for almost a year.
Mother mailed birthday cards without messages. Dad sent tuition questions through attorneys even though the separate Harrison trust paid school expenses. Relatives divided into camps.
Aunt Carol called me ungrateful. Uncle James said Dad had been wrong but believed I should forgive the debt because parents make sacrifices. Cousin Nina sent care packages to my dorm and never asked for details.
I learned that family support often reveals itself through what people do not demand. Nina did not require me to defend myself before offering kindness.
Brandon’s life changed sharply. Without the store salary, he found work selling commercial equipment. The income was lower but real. He sold the boat and recreational vehicle. Jessica continued with the separation, then filed for divorce after discovering additional lies unrelated to money.
For months, Brandon blamed me in angry emails.
You ruined my marriage.
You always wanted to be Grandpa’s favorite.
You care more about paperwork than people.
I replied once.
Your marriage ended because you hid debt and accepted money taken from my trust. The repayment agreement addresses money. Your relationship choices are yours.
Then I blocked him outside counsel-managed communication.
At Rice, I excelled academically but struggled personally. Independence was not the same as knowing how to live. I overworked because achievement had always been my defense. I checked trust statements compulsively, afraid money would disappear if I looked away.
A campus counselor helped me understand financial betrayal as a breach of safety, not merely an accounting dispute.
“You were told the future was secure,” she said. “Then adults announced they had taken it and expected gratitude. Of course you monitor everything.”
We built routines. I reviewed accounts monthly, not daily. I asked Margaret questions without apologizing. I budgeted my allowance and worked because I wanted experience, not because I needed to prove I deserved education.
Money became a tool again instead of a warning signal.
During my sophomore year, a severe storm damaged Cedar Ridge Plaza’s roof. Insurance covered part, but reserves absorbed a six-figure deductible and code upgrades. I attended meetings remotely and learned how quickly deferred maintenance becomes emergency cost.
Grandpa had left notes with the property files. One read: Keep reserves boring. Excitement is expensive.
I framed a copy above my desk.
The repair introduced me to commercial redevelopment. I changed my major focus, interned with a real-estate investment firm, and later completed a master’s degree in urban planning and finance.
At twenty-three, I became sole individual trustee subject to continuing institutional investment oversight. I did not remove First National. I converted its role from co-trustee to investment adviser and property administrator, preserving checks that had served me well.
“Your grandfather expected you might dismiss us on your birthday,” Margaret said.
“Was he worried?”
“He said if you did, the trust would have taught you less than he hoped.”
I kept the bank.
Cedar Ridge improved gradually. We repaired lighting, added covered walkways, and converted an empty unit into a shared space for small service businesses. Mr. Patel joined a tenant advisory group. Occupancy rose.
Lawson Home & Garden also stabilized under a professional manager. Dad remained owner but stopped taking daily cash withdrawals. Mother managed design services. Their rent became current.
The secured repayment note performed for three years.
Then sales declined after a national chain opened nearby. Dad missed one installment and called me directly for the first time since mediation.
“If the trust enforces the note, we lose the house,” he said.
“One missed payment does not trigger immediate foreclosure. The agreement has a cure period.”
“You know what I mean.”
“Send financial information to the administrator. We can evaluate a modification.”
“Can’t you decide as our daughter?”
The request transported me back to Bellini’s.
“I can consider hardship as trustee under the same standards applied to any secured obligation. I will not erase it privately.”
“You have more money than you will ever need.”
“The amount I have does not change what you agreed to repay.”
He ended the call.
The administrator approved a three-month interest-only period based on documented cash flow. Dad cured the arrears. Structure allowed compassion without returning to secrecy.
My relationship with Mother resumed first. She attended my graduate-school ceremony and waited near the edge of the crowd holding flowers. Dad did not come.
“I’m proud of you,” she said.
I wanted those words enough that part of me tried to accept them without context.
“Are you proud of me, or relieved Grandpa’s trust paid?”
Her face tightened. “Must everything return to that?”
“Not everything. But we have never discussed what you did.”
She looked around at families taking photographs.
“This is not the place.”
“Then choose one.”
She did not for another six months.
We finally met with a family therapist in Dallas. Mother said she had believed Dad when he claimed the education account was legally theirs. She knew Brandon received the money but did not know every transfer.
“Why did you clap?” I asked.
She covered her face.
“Your father told me we needed to present unity. He said if we looked uncertain, you would make a scene and embarrass Brandon.”
“So you celebrated.”
“I was afraid of him turning on me.”
“He turned on me instead, and you joined him.”
She nodded.
It was the first time she accepted the sentence without adding but.
“I am sorry,” she said.
Apology did not restore immediate trust. We began with monthly lunches in public. She did not ask about trust balances or carry messages from Dad. When she slipped into defending him, I ended the conversation and tried again later.
Repair came through repeated choices, not one emotional meeting.
Dad remained distant until Grandpa’s house, which had passed to him separately, suffered a kitchen fire. No one was injured, but smoke damaged family papers stored in a study.
Dad called because he found a metal document box labeled AVERY.
Inside were copies of trust agreements, my childhood report cards, and letters Grandpa had written but never mailed. Dad could have discarded them. He brought the box to my office.
By then, I was thirty and managed a small real-estate development company using no trust capital beyond a market-rate loan approved by the bank. Cedar Ridge was one of several properties under management.
Dad placed the smoke-stained box on my conference table.
“He kept everything,” he said.
“He kept records.”
“Same thing to him.”
One letter described why Grandpa created the separate trust.
Mark believes providing money gives him the right to direct people. Avery must learn stewardship without learning control. Protect her long enough to make her own mistakes.
Dad read the line before handing me the box.
“He thought poorly of me.”
“He understood one of your patterns.”
“You agree with him.”
“Yes.”
He sat across from me.
“Did I ever do anything right?”
The question was not an apology, but it contained less authority than I had ever heard from him.
“You taught me to negotiate. You worked hard. You helped relatives when no one else would. You also treated help as ownership and took money you were legally required to protect.”
“Both?”
“Both.”
He looked at the box.
“I thought if Brandon’s marriage failed, it would prove I had failed as a father.”
“So you made my future pay for your fear.”
“Yes.”
It was the first direct admission he gave me.
We did not hug. He left after twenty minutes.
Two weeks later, the education trust received the final payment on the secured note, three years ahead of the modified schedule. Dad had sold a parcel of inherited land to pay it.
He did not request thanks.
Brandon’s repayment took longer. He missed payments, changed jobs, and once attempted bankruptcy. The court treated parts of the obligation according to applicable law, and a revised plan continued. I stopped tracking each installment emotionally. Professionals administered it.
At thirty-two, Brandon requested a meeting.
We met at a diner near Dallas Love Field. He looked older, less polished, and more comfortable in his own skin. He had remarried and worked as a regional equipment salesman.
“I have sixty-one payments left,” he said.
“I know generally. The administrator handles details.”
“I used to think you checked every month hoping I would fail.”
“I used to check because I was afraid everyone would.”
He stirred coffee.
“Jessica was going to leave no matter what.”
“Probably.”
“Dad said money would buy time.”
“It did. It did not buy honesty.”
“I knew where it came from.”
“I saw the messages.”
“I’m sorry.”
“For knowing or for getting caught?”
He considered the question rather than becoming angry.
“At first, for getting caught. Now, for deciding your plans mattered less because you were younger.”
That answer felt real.
We rebuilt cautiously. I met his second wife, Elena, after a year. They kept separate business accounts and attended financial counseling before marriage. Brandon completed the repayment plan at thirty-seven.
On the day of the final payment, he texted a screenshot of the confirmation.
Done. I know this does not erase it.
I replied: It does not. It does complete the obligation. Thank you.
The original $224,000, plus recovered growth and settlement payments, ultimately funded more education than mine. I completed school without using all of it. With court approval and consistent with trust terms after my education ended, the remaining funds created the Harrison Opportunity Scholarship for students affected by family financial misconduct or sudden loss of promised support.
Creating the scholarship required more work than writing checks. We formed an independent nonprofit, recruited a board without Lawson relatives, established privacy rules, and partnered with accredited financial counselors. Applicants did not need to publish painful stories or prove that relatives were villains. They needed documentation of changed financial circumstances and an educational plan.
The first application cycle received eighty-three requests for six awards.
I read redacted summaries without names. One student’s father emptied a joint college account during a gambling relapse. Another aged out of foster care after a promised tuition waiver failed. A forty-six-year-old mother sought certification after divorce revealed that her husband had opened debt in her name.
Pain could not be ranked neatly. The board created a scoring system based on urgency, plan viability, available aid, and expected impact. We funded six, then raised outside donations for four more.
At the first scholarship luncheon, I told recipients only part of my story. I did not mention the $3.48 million balance because it could make the lesson sound like every loss hides a larger fortune.
“A promise about money is not security until you understand the account, ownership, and rules,” I said. “Ask for statements. Protect your identity. Seek independent advice. If promised support disappears, shame belongs to the person who misused it, not to you for needing a new plan.”
Afterward, a recipient named Naomi asked whether confronting family ever becomes easy.
“No,” I said. “But clarity reduces the number of arguments you must keep having.”
She later completed nursing school and joined the scholarship board. Her presence kept our decisions grounded in what students actually needed: textbook advances before aid arrived, emergency housing during breaks, credit repair, and counseling.
We learned that tuition alone rarely solves instability. Support had to recognize the whole transition without creating another controlling relationship.
Recipients kept autonomy. Funds went through clear agreements. No one owed personal access, public gratitude, or a success story suitable for fundraising.
That policy was Grandpa’s deepest lesson translated beyond my family.
The first recipient was a nursing student whose parent had opened credit cards in her name. Another was a young man whose college account disappeared during a divorce. They received tuition support and independent financial counseling.
I did not attach the Lawson name.
Grandpa had protected one granddaughter. The scholarship extended the principle.
Cedar Ridge Plaza remained in the trust for twenty years. We modernized it, maintained affordable space for local businesses, and added a community financial-counseling office in a former insurance unit. Mr. Patel retired and sold his hardware store to two employees through a structured purchase.
Lawson Home & Garden closed eventually, but not because I evicted it. My parents retired after receiving a fair offer for inventory and the customer list from a regional company. They completed the lease and left the unit in good condition.
On the final day, I met them at the store.
The showroom looked enormous without furniture displays. Faded rectangles marked walls where mirrors had hung. Dad handed Luis the keys.
“Eleven years,” he said.
“Twenty-three,” Mother corrected. The store had operated elsewhere before Cedar Ridge.
Dad looked at me. “You could have closed us after the birthday.”
“The trust needed a good tenant. Employees needed jobs. You needed a lawful chance to decide whether the business could survive.”
“I called that weakness.”
“I know.”
“It wasn’t.”
That was the closest he came to thanking me.
We walked outside. The plaza sign carried an American flag for Memorial Day. Evening heat rose from the parking lot. The unit that had once represented my parents’ control became an empty commercial space waiting for another tenant.
I did not feel triumphant.
I felt finished.
The family story changed slowly after that. Relatives who watched my birthday humiliation remembered themselves differently. Some claimed they had always been horrified. Others said they did not understand the trust. Aunt Carol apologized for calling me ungrateful, then asked whether her grandson might qualify for a scholarship. I directed her to the independent application process.
I stopped arguing about who had supported whom. Memory is flexible when consequences become clear. Documents mattered because they did not adjust themselves to preserve anyone’s pride.
I kept the original bank statement in a fire-resistant box. The paper yellowed slightly along one edge. The balance printed on it became outdated within weeks, but its meaning did not.
It was never proof that I was richer than my parents.
It was proof that another adult had anticipated the possibility of betrayal and built protection before I knew I needed it.
Grandpa’s trust did not save me by making me wealthy. It saved me by separating support from control. The bank could question my requests without punishing disagreement. The co-trustee could say no without withdrawing love. Rules existed before conflict and applied after it.
That structure became the model for how I ran my company and handled family.
Help was written clearly.
Loans were documented.
Gifts carried no secret authority.
Forgiveness did not erase repayment.
Boundaries did not require hatred.
On my fortieth birthday, our family returned to Bellini’s for the first time since I turned eighteen. The private dining room had been remodeled, but the windows and heavy wooden doors were the same.
I did not choose the restaurant. Mother suggested it carefully, saying we could go elsewhere if I preferred.
I agreed because the room no longer frightened me.
There were only nine of us: my parents, Brandon and Elena, Maya and her mother, Margaret Ellis, my husband David, and me. Jessica had built a different life and was not part of our family gatherings.
No one tapped a glass with a fork.
Dad gave me a small wrapped box privately before dinner. Inside was Grandpa’s old brass letter opener, the one he kept beside trust papers.
“I found it in the document box,” Dad said. “It should be yours.”
“Thank you.”
He looked toward the table.
“I rehearsed an apology.”
“You can say it if you want.”
“It sounded like I wanted you to tell me I was still a good father.”
I waited.
“I took money entrusted for you. I lied about why, humiliated you in front of the family, and expected you to carry the consequences quietly. I was wrong.”
No explanation followed.
“Thank you for saying that,” I replied.
“Do you forgive me?”
“I forgave enough to have dinner. Trust grew because you repaid the money and changed how you behave. Those are not the same thing, and neither erases the past.”
He nodded.
At the table, Mother placed a chocolate cake in front of me. She did not clap for herself or announce a sacrifice. Everyone sang badly. I made a wish I do not remember and blew out the candles.
Margaret raised her coffee cup.
“To responsible distributions,” she said.
I laughed so hard I nearly dropped the cake knife.
Later, Brandon asked whether I still had the statement I placed beside Dad’s plate.
“Yes.”
“What would you have done if Grandpa had not created the second trust?”
The question had visited me many times.
“Applied for more aid. Deferred enrollment if necessary. Worked. Sued for an accounting once I understood the documents.”
“Would you have forgiven us?”
“I don’t know. The money gave me breathing room. It did not make the betrayal smaller.”
People loved the twist because the large balance turned power instantly. But most young people whose families misuse their money do not discover millions or property. Their rights still matter. Their futures are not less worthy because no wealthy grandfather anticipated harm.
That understanding shaped the scholarship and counseling office more than any desire to celebrate revenge.
At the end of dinner, I walked through the restaurant lobby beside Dad. He paused near the spot where I had stood shaking at eighteen.
“I thought you were cold that night,” he said.
“I was terrified.”
“You didn’t look it.”
“Calm is sometimes what fear looks like when it has a plan.”
Outside, Dallas lights reflected on wet pavement after a brief summer storm. David took my hand. My parents drove home together. Brandon waited while Elena finished talking with Maya.
No one’s life had been destroyed. Consequences had changed it.
The education fund was restored over time. The store survived until retirement. Brandon learned to support his own household. Mother learned that unity without truth was participation. Dad learned, late but not too late, that providing help did not purchase another person’s future.
And I learned that wealth alone is not independence.
Independence is information, lawful authority, practical skills, and the confidence to use them without apologizing.
At eighteen, I believed the bank statement was the most powerful thing at the table.
I was wrong.
The statement mattered because I had read it, protected it, and brought it with me. Grandpa’s planning mattered because professionals enforced it. Rebecca’s counsel mattered because anger did not become reckless action. Luis’s management mattered because innocent employees were not sacrificed for a satisfying ending.
Power was not the seven-figure balance.
Power was the structure that prevented the loudest person in the family from deciding what belonged to everyone else.
That idea influenced the estate plan David and I later created. We did not have children, but we had nieces, nephews, scholarship commitments, and employees whose livelihoods could be affected if either of us became incapacitated. Our attorney asked who should control assets and under what conditions.
Years earlier, I might have selected the person I loved most and called that trust. Instead, we separated affection from function. A professional fiduciary would manage investments. Named relatives could advise on personal needs without controlling distributions. Successor managers for my company had defined authority, independent oversight, and removal procedures.
David read every page. We invited questions from the people assigned roles. No one learned about a duty at a funeral or birthday dinner.
“This feels unromantic,” he said after the third meeting.
“Clear plans are romantic. They prevent grief from becoming administration.”
He smiled. “That sounds like your grandfather.”
“He would have used fewer words.”
We also created a small discretionary fund for family emergencies. It required written requests and independent approval. Help would remain possible without turning one relative into the gatekeeper for everyone else.
Brandon initially laughed at the formality. Then an illness kept him away from work for two months. He applied, provided documents, and received temporary support under the same terms available to other named relatives.
“It was strange asking a committee,” he admitted.
“Did it feel humiliating?”
“No. Actually, it felt cleaner. I didn’t have to promise anyone Christmas for the rest of my life.”
That was the point.
Our family did not become perfect. Dad still offered advice as if it were an instruction. Mother sometimes defended old choices when ashamed. Brandon occasionally joked that I would audit his coffee order. I sometimes reached for a document when a conversation needed empathy.
Change did not erase personality. It gave us ways to interrupt harmful habits before they became another crisis.
At gatherings, younger relatives heard two versions of my eighteenth birthday. In Dad’s version, a terrible mistake forced the family to learn financial discipline. In Brandon’s version, a bank statement nearly stopped his heart. In mine, the evening was when private betrayal became visible and therefore solvable.
None of us described it as the night I defeated them.
Families are not defeated without everyone losing something.
We were corrected, separated where necessary, and slowly rebuilt where behavior made rebuilding possible.
My father told me to deal with losing my future.
So I did.
I dealt with it through records, courts, leases, education, and boundaries. I did not double rent overnight, empty anyone’s account, or destroy a business to prove I could. I asked for an accounting. I required repayment. I learned the property. I built a life.
The balance made my father pale for one evening.
The truth changed our family for decades.
Whenever I look at that old statement now, I remember neither the seven figures nor the shock around the table. I remember walking into the Dallas night with a backpack, a legal document, and no certainty that the people I loved would ever speak to me kindly again.
The real inheritance was not Cedar Ridge Plaza. It was the knowledge that love and accountability can occupy the same room, that protection does not require cruelty, and that a young person’s future is not a family emergency fund waiting for the most demanding relative to claim it.
Grandpa left me assets. Learning how to use them without becoming my father was the part I had to earn for myself.