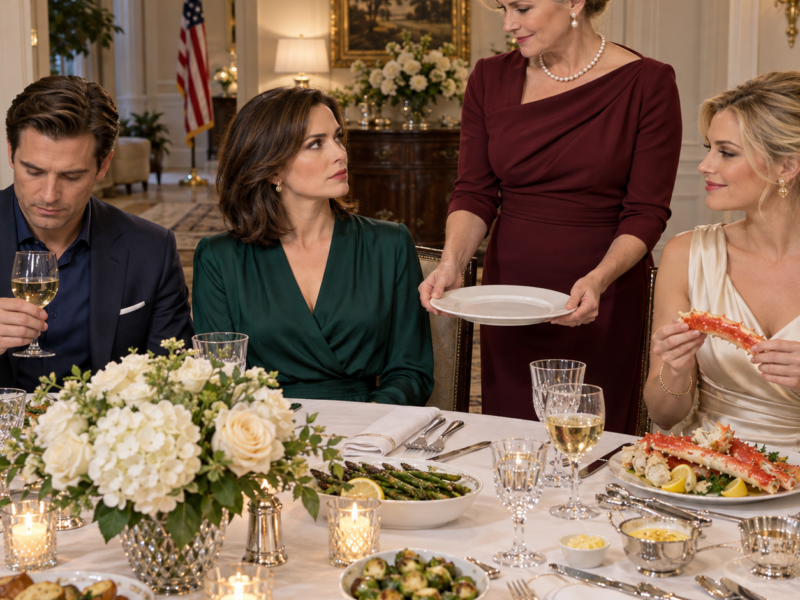
“We didn’t forget your dinner. Our funds for you are exhausted,” my mother-in-law said, setting an empty plate in front of me while her other daughter-in-law ate king crab. Three months earlier, I had sent her $12,000 to help save her house. When I asked my husband to say something, he called me entitled. I left them to their dinner. That night, I opened the folder containing six years of payments I had made for his family. By morning, I was comparing what I had sent with what her mortgage lender had received. The numbers didn’t match.
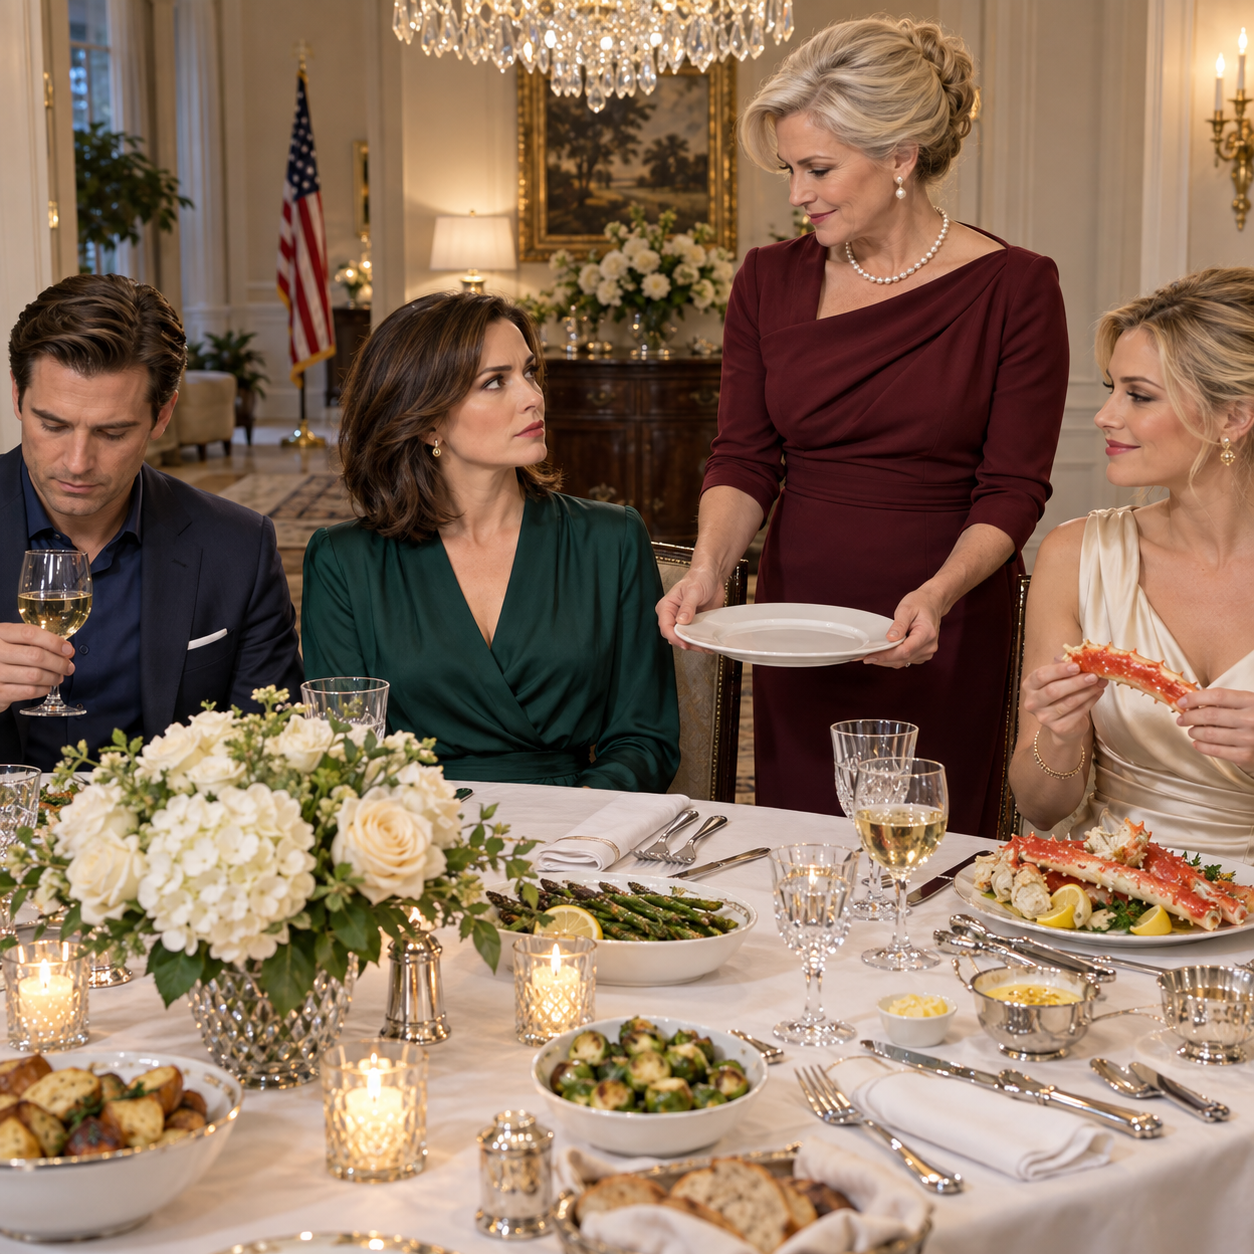
The empty plate in front of me was not an accident.
My mother-in-law, Diane, set it down with a smile so calm that I understood the insult before she spoke. Around us, the dining room smelled of garlic butter, roasted corn, lemon, and expensive Alaskan king crab. Steam lifted from two silver platters in the center of the table. Every place setting held a generous portion except mine.
Across from me, my sister-in-law, Vanessa, cracked open a thick crab leg and dipped the meat into melted butter. Diane hovered beside her like a proud hostess.
“Only the premium kind for Vanessa,” Diane said. “She appreciates quality.”
Then she glanced at the clean white plate she had placed in front of me.
I waited a moment, giving her one final chance to pretend it was a mistake.
“Did you forget mine?” I asked.
Diane laughed.
My husband, Mark, suddenly became fascinated with the wine in his glass.
“Oh, honey,” Diane said. “We didn’t forget.”
Vanessa smiled without looking up from her dinner.
Diane folded her hands over the front of her cream-colored blouse. “Our funds for you are exhausted.”
The room fell silent.
The sentence was absurd enough that I almost laughed. During the six years I had been married to Mark, Diane had never spent meaningful money on me. I had not asked her to. I paid for my own clothes, my own car, my own vacations, and half the household expenses Mark and I shared. More than that, I had quietly covered nearly every crisis Diane called a family emergency.
I paid $4,800 for her furnace when she said she would freeze through January without help. I covered medical copays after a minor surgery. I paid an overdue property-tax installment. I sent money for roof repairs after a storm, then another payment when the contractor supposedly discovered hidden damage. Three months before that dinner, Mark had persuaded me to send $12,000 toward Diane’s mortgage because she was, in his words, temporarily short.
Yet there I sat before an empty plate while she announced that her budget for me had run out.
Vanessa lifted a piece of crab to her mouth. “Don’t be so sensitive, Claire. Mom is just being financially responsible.”
I looked at Mark.
“Say something.”
He sighed, as though my discomfort were the only rude thing happening at the table. “Maybe Mom has a point. You’ve been acting a little entitled lately.”
Entitled.
The word landed harder than Diane’s performance. He knew where the money came from. He knew how often I stayed late at work, how carefully I maintained our savings, and how many times I had postponed something I wanted because his mother needed help. He had watched me write every check. In several cases, he had stood over my shoulder telling me the situation could not wait.
Diane leaned closer. “You married into this family. You don’t get to expect equal treatment just because you’ve written a few checks.”
“A few?” I asked.
Mark kicked my ankle under the table.
The gesture was small and childish, but it clarified everything. He did not want his mother to stop humiliating me. He wanted me to cooperate with the humiliation so dinner could remain pleasant for everyone else.
I looked down at the spotless plate.
Then I smiled.
“Understood.”
That reaction disappointed all three of them.
Diane had expected tears. Vanessa wanted an argument she could later describe as proof that I was unstable. Mark expected me to apologize and ask what I could do to earn my place back at the table.
Instead, I placed my napkin beside the empty plate and stood.
“Enjoy dinner.”
I walked into the hallway. Behind me, a crab shell cracked and someone released a nervous laugh. Mark followed before I reached the front door.
“You’re embarrassing me,” he whispered.
I turned and looked at him. He was forty-one years old, wearing the blue shirt I had bought him for his birthday, standing in the house whose mortgage problem I had repeatedly helped solve, telling me that my quiet departure was embarrassing.
“No, Mark. Your mother just taught me something valuable.”
“What?”
“Generosity without boundaries becomes an expectation.”
His expression tightened. “It was a joke.”
“Then go laugh.”
“Claire, don’t make this a bigger deal than it is.”
“I won’t.”
I took my coat from the hall closet and drove home alone.
Our house was twenty minutes away in a quiet suburb outside Baltimore. The drive took me past a pharmacy, a grocery store, and a small church where an American flag hung motionless beneath a yellow security light. I kept both hands on the wheel and did not turn on the radio. Anger usually made people want noise. Mine made everything unusually clear.
At home, I went directly to the office at the back of the house. Mark called twice. I let the calls ring. Then a message appeared.
Mom says you owe her an apology.
I set the phone face down.
At midnight, I unlocked the bottom drawer of my filing cabinet and removed a blue folder. Inside were six years of transfers, receipts, mortgage statements, emails, loan agreements, and notes from family conversations. Mark had always teased me for documenting everything. He called it my forensic-accountant brain, as if professional discipline were a charming flaw I should leave at the office.
He had forgotten what I did for a living.
I specialized in finding the story hidden inside ordinary transactions. My clients were companies that had lost money without understanding how. Sometimes the cause was fraud. Sometimes it was carelessness, poor controls, or an employee whose personal expenses slowly blended into business costs. I did not begin an investigation by accusing anyone. I began by collecting facts, building a timeline, and asking whether the records supported the explanation.
For six years, I had applied those standards everywhere except my marriage.
That night, Diane convinced me to audit my own family.
I began with the $12,000 transfer from three months earlier. Mark had sent me a screenshot of a mortgage statement showing that Diane needed help. The image displayed an amount due, an account ending in four digits, and a mailing address. He told me to send the money into an account that Diane used for housing expenses because an electronic payment from there would post faster.
I had asked why I could not pay the mortgage servicer directly.
Mark said Diane felt ashamed and wanted to handle it herself.
At the time, respecting her dignity seemed kind.
Now I compared the account information with earlier requests. The same destination appeared on transfers for roof repairs, property taxes, medical bills, and a supposed insurance shortage. It was not an account belonging only to Diane. An older authorization form showed Mark as a joint owner.
I created a spreadsheet.
Date. Amount. Stated purpose. Destination. Supporting document. Confirmed use.
The first year contained only three transfers. The second contained seven. The requests became more frequent after Mark’s father died. That timing had always made sense to me. Diane lost part of the household income, and grief made paperwork harder. I wanted to ease the transition.
But grief did not explain why invoices carried inconsistent dates. It did not explain why a roof contractor’s estimate had the same invoice number as a receipt from eight months earlier. It did not explain why Diane’s mortgage statements showed smaller payments than the money I had sent.
By breakfast, I had reconstructed eighteen months of assistance.
I transferred $38,600.
Only $9,200 could be matched to mortgage payments.
I checked the figures again because I wanted them to be wrong. Then I reviewed credit-card records Mark had once attached to a household budgeting email. Several transactions lined up with dates immediately following my transfers: a Caribbean cruise deposit, luxury-store purchases, expensive restaurants, and $7,300 paid to a cosmetic dental practice Vanessa had praised at Thanksgiving.
The picture grew uglier with every row.
My money had not merely helped Diane survive. It had subsidized a version of her life she could no longer afford while allowing Vanessa to enjoy benefits presented as gifts from her mother.
The most painful discovery arrived through a device sitting ten feet from me.
Mark had left his tablet on the office bookshelf after using it to review a home-insurance policy. The tablet was jointly owned and connected to the family messaging account he regularly used in front of me. A notification appeared on the screen as I reached for a binder.
Claire is getting suspicious about money.
The preview showed Diane’s name.
I did not guess a password or break into a private account. The device was already open, and the family thread appeared on the screen. I photographed the visible messages and stopped once I understood their significance.
Diane: Claire is getting suspicious about money.
Vanessa: She’ll still pay. She always does.
Mark: Just keep her feeling guilty. She hates conflict.
Then Diane wrote the sentence that ended something inside me.
Once the mortgage is current, we don’t need to pretend to like her anymore.
I read it three times.
The house was quiet except for the refrigerator humming in the kitchen. Morning light had begun to gather at the edges of the blinds. I expected to cry. Instead, I felt the same stillness that came over me when an investigation finally made sense.
The problem was no longer confusing.
They did not misunderstand my generosity. They had designed a strategy around it.
At 7:30, I called my attorney, Rachel Coleman. She had helped structure a small investment company I formed before marrying Mark. I explained only the facts I could document. She warned me not to move joint assets, destroy messages, access private accounts without authority, threaten anyone, or take action based solely on anger. She asked me to send the loan agreement I had made with Diane two years earlier.
That loan was different from the informal assistance. When Diane faced an earlier foreclosure threat, she asked me to cosign a mortgage refinance. I refused. Instead, my investment LLC lent her enough to cure the default. Diane signed a promissory note. As security, she granted the company a properly recorded interest in a small rental house inherited from her mother. The rental property was not Diane’s residence. It produced income and had no mortgage at the time.
The agreement required monthly payments, insurance, taxes, and notice of any new lien. It also described what would happen after default, including notice and an opportunity to cure.
I had not checked the loan ledger in nearly a year because Mark told me Diane was paying through an account he monitored.
She was not.
The last payment had arrived eleven months earlier.
“Have you sent any written extensions?” Rachel asked.
“No.”
“Did your company accept anything that could alter the agreement?”
“Not that I know of.”
“Then we will review the file, confirm the recorded security instrument, calculate the balance, and provide whatever notices the contract and state law require. Enforcement is a legal process, not a switch. Do not tell them you are taking the property. We do not know yet whether that will be necessary.”
“Understood.”
“And Claire, what do you want to do about Mark?”
I looked at the photographed messages.
“I need to understand my options.”
“Then gather statements for your own and joint accounts. Preserve the tablet without searching beyond what is authorized. Change passwords on accounts held solely in your name. Keep ordinary household expenses current. We’ll meet this morning.”
Those instructions protected me from the kind of impulsive behavior that makes satisfying stories and terrible legal cases. I did not cancel the electric bill, drain the joint checking account, or lock Mark out of our home. I did not call Diane and reveal what I knew. I went to work, moved through my scheduled meetings, and documented the facts.
That evening, Mark came home carrying takeout from my favorite Thai restaurant.
“For us,” he said, smiling as if the previous night had ended with a minor misunderstanding.
I sat at the kitchen table with my laptop open.
He kissed my forehead. “Mom says you owe her an apology.”
“For what?”
“Being dramatic. Walking out made everybody uncomfortable.”
“Anything else?”
He opened the takeout bag and avoided my eyes. “She needs another payment soon.”
I almost admired the nerve.
“How much?”
“Probably ten thousand.”
“For the mortgage?”
“And taxes. She’s still sorting it out.”
I nodded slowly. “Send me the documents.”
Relief moved across his face so quickly that I nearly missed it.
“I knew you’d calm down,” he said.
He believed the restaurant bag had restored the old arrangement. He did not ask whether I had eaten since the empty plate. He did not apologize. His only concern was whether the money would continue.
After he went upstairs, I reviewed records Diane had previously provided while asking for help. I did not impersonate her or demand private information from her mortgage servicer. I used the statements, notices, and authorization pages already in my possession and gave them to Rachel for review.
The documents showed three missed payments. The loan was approaching ninety days delinquent. The money Mark claimed had been sent was nowhere near the lender.
The following afternoon, Vanessa sent me a photograph of another expensive seafood dinner. A bright red lobster filled most of the plate.
Maybe next time bring your own food, she wrote.
I saved the message.
At 4:17, Mark texted from work.
Mom says she needs the mortgage money tomorrow. Don’t make this weird.
I replied with two words.
Of course.
That night, he slept peacefully beside me.
I did not.
I printed every transfer, every relevant message, and every document Diane had used to justify a request. I placed them inside the blue folder. Then I made copies for Rachel and stored the digital files in a secure account Mark could not access.
At 8:06 the next morning, my phone rang.
Diane.
She skipped hello.
“Claire! The mortgage is almost ninety days late. Pay it today.”
Her voice was not frightened. It was commanding.
I looked through my office window at commuters moving along the street below. For six years, urgency in Diane’s voice had activated the same response in me: solve the problem, avoid conflict, protect the family. This time, I listened to the demand without accepting it.
“Sorry, Diane.”
“What?”
“My funds for you are exhausted.”
The silence lasted four seconds.
“You think this is funny?” she screamed.
“No. I think it’s finished.”
“You promised to help this family.”
“I helped. You redirected the money.”
She inhaled sharply. “How dare you accuse me?”
“Thirty-eight thousand six hundred dollars. That is what I transferred during the last eighteen months. Only $9,200 can be matched to your mortgage.”
Her breathing changed.
“Would you like me to list the rest?” I asked. “Vanessa’s dental work. Your cruise. Designer purchases. Restaurants. Or should I start with the $3,400 resort charge Mark helped you hide?”
“You went through our accounts?”
“I reviewed my transfers and records you gave me.”
The front door of our house slammed hard enough to shake the framed photograph in the hallway. Mark rushed into my office, still wearing his coat.
“What did you say to Mom?”
I put the call on speaker and placed the phone on my desk.
“Perfect timing.”
Mark saw the blue folder. The color left his face.
I slid three pages toward him. They contained the messages visible on the tablet.
She’ll still pay. She always does.
Keep her feeling guilty.
We don’t need to pretend to like her anymore.
Mark lowered himself into the chair.
“Claire, listen.”
“I have been listening for six years.”
Diane shouted through the phone. “Mark, fix this!”
I laughed once, not because anything was funny but because the command exposed how little she understood. She believed Mark could still reset me with an apology, a meal, or a warning about family loyalty.
“There is nothing to fix,” I said.
I handed Mark another document.
He stared at the heading. “What is this?”
“A copy of the default notice Rachel’s office is preparing under the loan agreement.”
Diane’s voice cracked. “What notice?”
“The private loan secured by your rental property. You stopped making payments eleven months ago.”
“You wouldn’t.”
“I kept extending grace because you were family. You used that grace to finance vacations and humiliate me.”
“You’re going to take my property over dinner?”
“No. Your rental property may be subject to enforcement because you violated a written agreement for eleven months. Dinner convinced me to stop shielding you from the consequences.”
Diane began crying and said I would make her homeless.
“The collateral is not your home,” I replied. “It is a rental property producing income. Your residence is a separate house.”
The crying stopped almost immediately.
I looked at Mark.
“And you should pack a bag.”
His eyes widened. “What?”
“I met with a divorce attorney.”
“Claire, come on.”
“You helped your mother deceive me.”
“It wasn’t like that.”
I tapped the messages. “It is written down.”
He tried confusion, then regret, then anger. I watched each emotion arrive as a strategy rather than a feeling.
“You can’t destroy everyone because Mom made a stupid joke,” he said.
“I am not destroying anyone. I am no longer financing people who despise me.”
For the first time in our marriage, Mark had no answer ready.
The confrontation was not the end of the story. It was the first moment I stopped carrying it alone.
Mark moved into the guest room that night. Rachel advised me not to remove him from the house without an agreement or court order. We separated our daily routines while the legal process began. I continued paying my share of ordinary household expenses and preserved every relevant record. Mark retained access to joint funds for legitimate costs. What ended was the secret pipeline from my income to his family.
Within twenty-four hours, the calls began.
Mark’s aunt said Diane had made mistakes but did not deserve to be punished. A cousin I had met twice told me marriage meant forgiveness. Vanessa sent nine messages accusing me of enjoying power over an elderly widow. None mentioned the $38,600. None asked why only $9,200 reached the mortgage.
The family focused on my response because examining Diane’s conduct would force them to revise a story they preferred. In that story, Diane was a struggling widow, Vanessa was a devoted daughter, Mark was a patient son, and I was the wealthy outsider who needed to learn humility. My money was welcome because it preserved their identities. My questions were dangerous because they threatened them.
I stopped explaining.
Rachel sent Diane the formal notice required under the agreement. It stated the amount due, the default, her right to cure, and the deadline. It offered contact information for discussing a realistic repayment plan. There were no threats, insults, or references to the crab dinner.
Diane called the notice heartless.
Her lawyer called it enforceable.
Those were not the same thing.
During the next week, I learned more about the rental property. Diane collected $1,850 a month from a schoolteacher named Carla who had lived there for four years. The lease required Diane to maintain the roof, plumbing, and heating. Yet several of the repairs I supposedly funded at Diane’s residence had actually involved the rental house, and some appeared never to have been completed.
I did not contact Carla directly. She was a tenant, not evidence. Rachel obtained information through proper channels while evaluating the collateral. We confirmed taxes and insurance, ordered a title update, and requested an independent valuation.
The records showed that Diane could have paid the private loan from rental income. She chose not to.
When confronted, she claimed the rent covered maintenance. Receipts showed otherwise. The account that received Carla’s payments also funded resort charges, restaurant meals, and transfers to Vanessa.
It became clear that the empty plate had not been a spontaneous act of meanness. It was part of a power structure maintained through money and status. Diane rewarded the daughter who depended on her and belittled the daughter-in-law whose income protected her. Vanessa helped preserve the illusion by praising Diane’s generosity. Mark served as the bridge, moving my money into the system while reassuring me that every request was temporary.
As long as I kept paying, all three could pretend the hierarchy was real.
The hierarchy collapsed the moment I asked for records.
Mark spent the first week insisting that the messages were jokes. He said families sometimes complained privately. He claimed “pretend to like her” referred to Diane being frustrated after I questioned a roof estimate. He said he told them I hated conflict because he wanted everyone to get along.
“You told them how to manipulate me,” I said during one conversation in Rachel’s office.
“I was trying to keep the peace.”
“Whose peace?”
He opened his mouth, then closed it.
“Every peaceful dinner required me to ignore an insult,” I continued. “Every peaceful holiday required me to pay for something. Every peaceful conversation required me not to ask where the money went. That was not peace. It was compliance.”
Mark looked at Rachel as if he expected her to soften my words.
She did not.
The divorce disclosure process brought its own revelations. Mark earned a respectable salary as a regional sales manager, but his personal savings were far smaller than I believed. He had been sending between $600 and $1,400 a month to Diane and Vanessa in addition to the larger requests routed through me. Some transfers came from joint funds. Others came from a credit card I rarely used.
He had accumulated $27,000 in revolving debt.
“Why didn’t you tell me?” I asked when the statements arrived.
“Because you would have said no.”
“That is not an answer.”
“It is the answer.”
The honesty shocked me more than another lie would have.
Mark did not hide the debt because he feared my anger. He hid it because informed consent might interrupt the arrangement. In his mind, my likely refusal justified removing my chance to refuse.
He told himself the expenses were temporary. Diane would sell the rental house someday. Vanessa would repay him after a promotion. A bonus would erase the card balance. Every future solution allowed him to avoid a difficult conversation in the present.
I had seen the same pattern in fraud cases. People imagine wrongdoing begins with greed. Often it begins with avoidance. Someone shifts one expense into the wrong category to prevent an uncomfortable meeting. Then another. Soon the person is not solving a problem but protecting the first concealment. The lie grows because truth becomes more expensive every month.
Mark’s concealment had reached our marriage before I recognized it.
The joint debt had to be addressed fairly. Rachel did not promise that every hidden charge would automatically become Mark’s legal responsibility. Family law was more complicated than moral outrage. We documented when the debt was incurred, who benefited, what Mark disclosed, and which payments related to marital expenses. His attorney did the same. Some amounts would be contested. Others were clearly personal.
I did not need a judge to declare me right about every dollar. I needed the final agreement to reflect evidence rather than pressure.
Meanwhile, Diane’s cure deadline approached.
Her first proposal offered $200 a month on a balance that would have taken decades to repay. It included no financial disclosure and assumed the security interest would remain dormant indefinitely. My company rejected it through counsel.
Her second proposal promised a lump sum after Vanessa refinanced her condominium. Vanessa did not own a condominium.
Her third proposal asked me to forgive half the balance as a family gift.
Rachel responded that my company would consider a documented repayment plan supported by current income, expenses, and the rental property’s value. Diane refused to provide the information.
Instead, she organized a Sunday lunch at the church she attended and invited Mark, Vanessa, three relatives, and me. The invitation arrived by text two days before the cure deadline.
We need to talk as a family, she wrote. No lawyers. No spreadsheets. Just love.
I showed it to Rachel.
“You are not required to attend,” she said.
“I know.”
“If you go, do not negotiate legal terms. Do not agree to delay. Do not let anyone separate you from your records or pressure you to sign anything.”
I decided to attend for one reason. I wanted to hear whether anyone in that family could speak about what happened without making my money the central obligation.
The church hall smelled of coffee and baked ham. Folding tables were covered with white plastic cloths. A small flag stood near the podium, and children’s drawings from a Sunday-school class decorated one wall. Diane chose a public, respectable place because she believed appearances would control the tone.
She greeted me with swollen eyes and a trembling smile. Vanessa did not greet me at all. Mark arrived separately and sat between us.
For the first twenty minutes, relatives described Diane’s grief, her years as a mother, and the importance of keeping family matters private. Nobody mentioned the false explanations for the transfers.
Finally, I opened my notebook.
“I have one question,” I said. “Where did the $29,400 that did not reach the mortgage go?”
Diane looked at the pastor’s wife, who had joined lunch without knowing the details.
“This is exactly what I mean,” Diane said. “She reduces people to numbers.”
“The request was about money. The answer requires numbers.”
Vanessa pushed back her chair. “You make more in a year than Mom has ever had. Why does it matter?”
There it was.
Not denial. Not confusion. The belief that my ability erased their obligation to ask.
“It matters because it was obtained through false statements,” I said.
“Mom needed joy after Dad died.”
“Then she could have asked whether I wanted to pay for a cruise.”
“You would have said no.”
“Exactly.”
Vanessa stared at me as if I had confessed to cruelty.
Mark’s aunt spoke next. “Maybe Diane handled it badly, but taking property is extreme.”
“The loan was signed two years ago,” I replied. “The property was offered as collateral by Diane with independent legal advice. She stopped paying eleven months ago. She has received formal notice and several opportunities to propose a workable solution.”
“Can’t you just let it go?”
I looked around the table. “What amount of deception would this family consider too much?”
No one answered.
“If I forgive the debt today,” I continued, “what changes? Does anyone repay the diverted money? Does Mark acknowledge the hidden credit-card balance? Does Vanessa stop mocking the person financing her expenses? Does Diane apologize for the empty plate, or does everyone simply learn that enough pressure will make me pay again?”
Diane began to cry.
This time, I did not call the tears false. She was frightened. The property, the mortgage, and the family story were all slipping beyond her control. Her fear was real. It also did not erase the choices that produced it.
“I never thought you would turn on us,” she said.
“I did not turn on you. I stopped turning against myself.”
I left before dessert.
Mark followed me into the parking lot.
“You made Mom look terrible in front of everyone.”
“I asked where the money went.”
“You knew she couldn’t answer.”
“That is why the question matters.”
“Do you enjoy this?”
“No.”
“Then stop.”
I looked at him across the hood of my car. “You still think discomfort proves I am wrong.”
“I think you could choose mercy.”
“Mercy is not the same as restoring access.”
He stood there while I got into the car. In the mirror, I watched him return to the church hall, shoulders bent as if I had assigned him an impossible burden.
The burden was responsibility.
He had avoided it for so long that it felt like punishment.
Three days later, Diane failed to cure the default.
My company did not instantly seize the rental house. Rachel followed the enforcement process required by the agreement and state law. Notices were recorded and served. Diane obtained counsel. An appraisal and title review were completed. The tenant’s lawful rights remained protected. Diane could still refinance, sell voluntarily, or negotiate if she produced a credible plan.
She chose delay.
Her attorney requested extensions. We granted one short extension conditioned on updated financial information. The documents finally provided showed that the rental property had significant equity. They also showed more than $22,000 in withdrawals and transfers to Vanessa during the same period Diane claimed she could not pay the loan.
The evidence changed the tone of negotiations.
Vanessa had used the money for dental work, a leased luxury crossover, boutique clothing, and a destination birthday weekend. She called these necessities because her career required her to maintain an image. She worked in real-estate marketing and believed appearing successful was part of the job.
“My clients notice everything,” she told me during a settlement meeting.
“Then they may also notice whether you can afford it,” I replied.
Her lawyer asked everyone to remain civil.
I apologized for the remark. It was satisfying but unhelpful, and I was trying to learn the difference.
Diane proposed selling the rental property herself. My company agreed, provided the sale occurred within a defined period, the property remained insured, taxes stayed current, and proceeds were handled through closing. A voluntary sale would likely preserve more equity than forced enforcement.
For the first time, Diane faced a decision with numbers she could not move into someone else’s account.
She listed the property.
The tenant, Carla, received proper notice and relocation support required under the sale arrangement. I insisted that part of the resolution account for repairs Diane had neglected. Not because I wanted to appear generous, but because Carla had paid rent and deserved to be treated as a person rather than an obstacle.
When the rental house sold, the legitimate loan balance, contractual costs, taxes, and authorized expenses were paid at closing. The remaining proceeds went to Diane as the law and agreement required. I did not take a dollar beyond what the company was owed.
That fact disappointed relatives who had spent months saying I wanted to steal the entire property.
They did not apologize when the closing statement proved otherwise.
Diane’s residential mortgage remained her responsibility. By then, the delinquency had worsened. She could have used the remaining sale proceeds to cure it, but doing so would leave her with a house too expensive to maintain on her income. A housing counselor and her attorney helped her evaluate the options. She sold before foreclosure and bought a modest condominium with lower taxes and no large yard.
The move was not the tragedy she described. The condominium was clean, safe, and near her church. It had two bedrooms, an elevator, and a small balcony. What she lost was not shelter. She lost the image of being the prosperous center of a family whose lifestyle had quietly depended on me.
Vanessa discovered that premium crab looked different when no one else paid the bill.
Her leased vehicle was returned early at a cost. She reduced shopping, took on additional clients, and moved her birthday celebration from a resort to a local restaurant. These were ordinary adjustments millions of adults make. In family conversations, however, they were described as suffering caused by Claire.
I learned that people who benefit from an arrangement often call its end an attack.
Mark fought the divorce at first. He objected to nearly every proposed division, challenged the classification of my premarital investment company, and accused me of using professional knowledge to hide assets. Rachel responded with complete records, valuations, tax returns, and account histories. Transparency did not eliminate conflict, but it narrowed the space where fantasy could survive.
My company had been formed four years before the marriage using savings and an inheritance from my grandmother. Its value and later marital contributions required careful analysis, not slogans. An independent financial expert traced the funds. I accepted that some growth attributable to marital effort might be considered in the settlement. Mark had a right to a fair process, even after behaving unfairly.
The house Mark and I shared had been purchased during the marriage. We had both contributed, though my down payment was larger. The mortgage and equity were marital issues. I did not assume I could keep everything simply because I earned more. We obtained an appraisal and considered whether either of us could afford a buyout.
Neither of us truly wanted the house.
It had become a container for a marriage that no longer existed.
We agreed to sell.
Preparing it for the market required weeks of quiet cooperation. Mark packed books from the den while I sorted the kitchen. We chose repairs based on the real-estate agent’s advice. Sometimes we moved through the same room without speaking. Other times an ordinary object opened a memory neither of us expected.
He found a chipped mug from our first vacation and held it up.
“You kept this?”
“You said the chip made it lucky.”
“I was trying to stop you from throwing it away.”
“It worked.”
We both smiled, then remembered where we were.
The existence of good memories did not invalidate the divorce. That was one of the hardest truths to accept. Mark had not been cruel every day. He brought me soup when I was sick, sat beside my mother during chemotherapy, and once drove six hours through snow when my flight was canceled. I had loved him for reasons that were real.
He also helped his family deceive me, used guilt to keep money flowing, and concealed debt because he knew I might refuse.
Both versions were true.
People often stay in damaging relationships because they think leaving requires proof that every moment was bad. It does not. A marriage can contain tenderness and still become untrustworthy. Someone can have loved you and still choose actions that make continuing unsafe.
Our mediation took place four months after the crab dinner. Mark sat across from me in a conference room with his attorney. He looked older than he had at Diane’s table. The credit-card debt, house sale, family pressure, and legal fees had worn away his certainty.
The mediator began with assets and debts. We worked through accounts one by one. Joint retirement contributions were divided according to the agreed formula. The house sale proceeds would be distributed after mortgage and closing costs. Personal property was resolved through lists. Mark kept his vehicle and assumed its loan. I kept mine.
The hidden credit-card balance took longer. Records showed which transactions went to Diane and Vanessa. Mark argued that supporting his mother was a marital purpose because I had supported her before. Rachel replied that prior gifts did not create unlimited consent, particularly when Mark concealed the borrowing.
We compromised after considering litigation cost and uncertainty. Mark accepted most of the disputed debt. I accepted a smaller portion tied to ordinary household spending. Neither side received everything requested.
Then the mediator asked whether there was any possibility of reconciliation.
Mark looked at me.
“I want there to be,” he said.
It was the first time he had said so in front of counsel.
“What would be different?” I asked.
“I would stop sending Mom money without telling you.”
“That is a rule, not a repair.”
“I would apologize.”
“For what?”
He rubbed his hands together. “For letting things get out of control.”
“They did not get out of control by themselves.”
His attorney shifted in her chair.
Mark tried again. “I should not have hidden the debt.”
“And the messages?”
“I was frustrated.”
“You gave them instructions for manipulating me.”
“I didn’t think of it that way.”
“That is the problem.”
He looked down. The mediator allowed the silence to remain.
“I am sorry,” Mark finally said. “I knew you hated conflict. I used it. I told myself I was protecting everyone, but I was protecting myself from having to choose.”
The words were more honest than anything he had said since the dinner.
I believed him.
I still declined reconciliation.
An apology can acknowledge a broken bridge. It does not always make the bridge safe to cross.
Six months after Diane placed the empty plate in front of me, the divorce became final. The hearing lasted less than an hour. There was no dramatic speech from the judge and no family waiting in the hallway. The court reviewed our agreement, confirmed that both of us understood it, and entered the necessary orders.
Outside the courthouse, Mark asked whether we could get coffee.
We walked to a diner across the street. The waitress filled two thick white mugs and called us honey without knowing what had just happened.
Mark stirred sugar into his coffee.
“Mom blames me,” he said.
“For the divorce?”
“For everything. The house, the rental, Vanessa’s problems. She says I brought you into the family and let you turn us against each other.”
“Did I?”
“No.” He looked toward the window. “I think we were already against each other. We just had money covering it.”
That was the first sentence that made me believe he might eventually understand.
“Why did you let them treat me that way?” I asked.
He did not pretend to misunderstand.
“Because when they were angry at you, they weren’t angry at me.”
The answer was painful and complete.
Mark had used me as both resource and shield. My income solved the practical problems. My outsider status absorbed the resentment. As long as I occupied those roles, he could remain the good son and generous brother without paying the full financial or emotional cost.
“I hope you change that,” I said.
“I’m trying.”
We finished our coffee. At the curb, he hugged me briefly. I wished him well and meant it.
Then I drove away.
For the first few weeks after the divorce, freedom did not feel triumphant. It felt quiet in ways that unsettled me.
I rented a furnished apartment while the house sale closed. The building stood near a park where retirees walked in pairs each morning and young parents pushed strollers beneath old maple trees. My unit had one bedroom, a small balcony, and a kitchen with barely enough counter space for a coffee maker. After years of receiving family calls at all hours, I found myself checking my phone for emergencies that no longer belonged to me.
At 6:30 each morning, I woke before the alarm and expected a message from Mark.
Mom needs help with taxes.
Vanessa’s car is making a sound.
The roof estimate went up.
Can you transfer the money today?
Most mornings, the screen was empty.
At first, that emptiness felt like proof that nobody missed me. Then I began to understand it as time returned to its rightful owner.
I started walking through the park before work. I learned which coffee stand opened earliest and which bench caught the first sunlight. I called friends I had neglected because Diane’s emergencies always seemed more urgent. I accepted a Saturday invitation without checking whether Mark had promised our weekend to his family.
The ordinary freedom embarrassed me. I had not realized how much of my life required silent permission from people who claimed I controlled them.
My therapist, Dr. Helen Park, asked why I had helped for so long.
“Because I could,” I answered.
“That explains capacity,” she said. “What did helping protect you from?”
I disliked the question.
I had spent months identifying everyone else’s motives. Diane wanted status and security. Vanessa wanted comfort without the cost. Mark wanted to avoid conflict and preserve his role as the good son. Their behavior could be traced through statements and messages.
My own behavior could not be explained by a spreadsheet alone.
I grew up in a household where money disappeared without warning. My father owned a small repair shop. Some months were good, and some ended with my mother spreading bills across the kitchen table after my sister and I went to bed. I learned to recognize the sound of financial fear: drawers opening too quickly, envelopes torn at the edge, whispered arguments stopping when a child entered the room.
By sixteen, I balanced my parents’ checkbook. By nineteen, I understood interest, insurance deductibles, and payment plans better than most adults around me. Numbers became a way to prevent panic. If I could see every obligation, I could prepare. If I could prepare, nobody had to feel afraid.
That skill built my career.
It also taught me to confuse rescue with love.
When Mark brought me a family problem, solving it gave me a sense of belonging. Diane called me brilliant when I found a better insurance policy. Vanessa hugged me when I covered a deposit. Mark told friends he did not know what the family would do without me. Their dependence felt like proof that I had earned a permanent place.
The crab dinner revealed how fragile that place was. Six years of help could be erased by one empty plate because gratitude had never been the structure holding us together. Usefulness was.
“Were you afraid they would not love you if you stopped?” Dr. Park asked.
“Yes.”
“And what happened when you stopped?”
“They did not love me.”
She waited.
I corrected myself. “They did not treat me lovingly.”
That distinction mattered. I could not know everything another person felt. I could judge conduct. Love hidden beneath deception, humiliation, and entitlement was not a form of love I could safely build a life around.
As spring approached, I began looking for a permanent home. My real-estate agent showed me townhouses, condominiums, and small detached houses. At first, I evaluated each one as if Mark might join me. I noticed whether a second car would fit and whether the guest room could hold Diane’s antique dresser. Old habits continued drafting a future that no longer existed.
Then we visited a small house near the Chesapeake Bay.
It had weathered gray siding, two bedrooms, and a narrow porch facing the water. The kitchen cabinets were older but solid. A previous owner had planted rosemary and lavender along the back steps. There was no formal dining room and no place for twelve relatives to gather around a table while pretending everything was fine.
I stood at the living-room window and watched sunlight scatter over the bay.
“This one,” I said.
The purchase was comfortably within my budget. I did not need a loan from anyone, a joint signature, or family approval. My inspector found ordinary issues, and I negotiated repairs without confusing caution with conflict. Six weeks later, I received the keys.
On my first evening there, I unpacked one pan, one plate, and a wineglass. Then I drove to a seafood market and bought crab legs, corn, lemons, and a small loaf of bread.
I cooked with the windows open. Butter and garlic warmed the kitchen, carrying a familiar smell through a place untouched by the old family. I filled my plate, carried it to the porch, and watched the sun move toward the water.
I had imagined the meal as a declaration. Instead, it felt private and gentle.
There was no audience to understand the symbolism. No camera captured it. No relative saw that the plate was full.
That made it better.
My life was no longer a performance directed at people who had underestimated me.
Work changed too. The experience made me more attentive to the emotional structure behind financial misconduct. At my firm, we investigated a regional nonprofit whose accounts showed unusual reimbursements. The executive director insisted the amounts were harmless and reminded us how many families the organization served. Board members hesitated to ask questions because they did not want to appear disloyal to the mission.
I recognized the language immediately.
Good causes do not make records unnecessary. Family language does not make consent automatic. Generosity does not transform deception into need.
Our team found that the director had routed personal travel through a program budget. The amount was smaller than expected, but the control failure was serious. We helped the board correct it without destroying the nonprofit. The goal was accountability, not spectacle.
After the case, a younger accountant named Leah asked how I remained calm when people accused us of lacking compassion.
“Compassion and verification are not opposites,” I told her. “If help can survive only while nobody checks the facts, it is not a healthy system.”
The sentence applied as much to my marriage as it did to the client.
I began writing down the practical lessons I wished I had followed. Not rules for punishing relatives, but safeguards for helping without losing oneself.
Pay a provider directly when the stated need is specific.
Ask for documents before urgency removes the chance to think.
Define whether money is a gift or a loan. If it is a loan, use a real agreement and enforce it consistently.
Never cosign or guarantee an obligation without understanding the worst possible outcome.
Do not lend money required for retirement, housing, medical care, or basic security.
Notice whether the same emergency repeats after every rescue.
Most important, pay attention to how someone reacts when you ask a reasonable question.
People in genuine difficulty may feel embarrassed. They may be disorganized or overwhelmed. But a person who needs secrecy more than assistance is asking for something different from help.
Accountability did not require me to accept blame for Diane’s choices. It required me to see how my avoidance helped the pattern continue. I had called delayed confrontation kindness. Often it was fear wearing a respectable name.
Several months after I moved, Carla, the former tenant of Diane’s rental property, sent a note to my attorney. She had learned through closing documents that my company held the loan. Her letter was brief.
Thank you for making sure I received notice and time to move. Mrs. Bennett told me the house would be taken without warning because her daughter-in-law wanted revenge. That was not what happened. I found an apartment near my school and received my deposit. I thought you should know.
I kept the note.
It mattered because Carla had been the person most vulnerable to decisions made by others. She owed me no gratitude, and I had not rescued her. We simply insisted that the process recognize her rights. Sometimes decency is not dramatic. It is notice delivered on time, a deposit returned, and enough days to find another home.
The story circulating through Mark’s family remained different. According to them, I had used a dinner insult as an excuse to take a widow’s property. Facts about default notices, sale proceeds, and the protected tenant were too complicated for gossip. The empty plate was simple. It allowed them to call my reaction disproportionate while ignoring everything the plate represented.
For a while, I tried correcting the story. I drafted messages listing amounts and dates. I imagined sending the closing statement to every relative. Rachel advised me not to distribute private documents merely to win a social argument.
“The legal matter is resolved,” she said. “Ask yourself what victory you expect from people committed to a convenient version.”
I deleted the drafts.
The decision cost me several relationships. Holiday cards stopped. Invitations disappeared. People I had once helped did not call. Their absence hurt, even when I understood it.
Boundaries are often described as empowering, but the early stage can feel like grief. When a person stops performing a role, she may lose everyone who related primarily to the role. The silence afterward is not immediate proof that the boundary was wrong. Sometimes it is evidence of how little room the old relationship allowed for a full human being.
I built new traditions slowly.
Vanessa contacted me in January.
Her message was unusually formal.
I would like to discuss resolving the remaining money issues without lawyers.
There were no remaining money issues between us. The transfers to her had come through Diane or Mark. The divorce was final, and the loan closing was complete. I suspected she wanted financial help but did not answer immediately.
The next day, she sent another message.
My car situation has affected work. Mom cannot help. Mark says no. You know I can repay you after my commission closes.
The request almost impressed me with its return to the old script. Emergency. Temporary. Family connection. Future repayment. No acknowledgment of the photograph she had sent after the crab dinner. No apology for calling me entitled while eating food I indirectly financed.
I replied once.
I am not available as a lender. A nonprofit credit counselor may help you review your options. Please do not contact me again about money.
Her response arrived within a minute.
You always thought you were better than us.
I did not answer.
The accusation once would have sent me into a long explanation. I would have listed every act of help as proof that I did not feel superior. Now I understood that she was not requesting information. She was searching for the emotional lever that had worked before.
When guilt failed, she tried shame.
I blocked the number.
Mark handled boundaries with his family less cleanly. We spoke occasionally about the house closing and tax documents. During one call, he admitted that Diane and Vanessa continued asking for money.
“What do you say?” I asked.
“Sometimes no.”
“And the other times?”
“I send what I can.”
I did not lecture him. Divorce had returned his decisions to him. If he chose to support them from his own income after paying his obligations, that was his right.
“Just do not borrow to avoid their anger,” I said.
He gave a tired laugh. “You still sound like an accountant.”
“I am an accountant.”
“I know. I used to say it like it was a flaw.”
The conversation ended kindly.
Over the following year, Mark reduced the credit-card balance and rented a small townhouse. He attended counseling, something he once dismissed as paying a stranger to take sides. He did not transform overnight. Neither did I. Growth was less visible than our conflict had been.
One afternoon, he emailed a scanned page from a notebook. It contained two columns.
What I can help with.
What I cannot take responsibility for.
He wrote that the exercise came from counseling. Under the second heading, he had listed his mother’s housing choices, Vanessa’s car, other adults’ reactions, and keeping everyone happy.
I stared at the last item for a long time.
Then I replied: That is a strong list. Keep it where you can see it.
He thanked me. Neither of us mentioned getting back together.
The fact that he changed after losing the marriage once would have felt unbearably unfair. Why could he not learn while we were together? Why did consequences succeed where love had failed?
Dr. Park offered an answer I resisted.
“Love may have softened the consequence every time it approached,” she said.
I had paid the bill, calmed the argument, accepted the explanation, and returned to the table. My love did not cause Mark’s dishonesty, but my rescue prevented some choices from becoming fully visible to him. When I stopped, he finally had to meet himself without me standing between him and the outcome.
That did not mean I should have been harsher sooner. It meant love without truth can preserve the very behavior that eventually destroys a relationship.
On the first anniversary of the crab dinner, I was at a grocery store when I saw a display of king crab legs on crushed ice. The memory arrived so vividly that I could smell Diane’s dining room.
For a second, my chest tightened.
Then I noticed the price and laughed. I bought two legs, lemons, and a small container of clarified butter. At home, I called my neighbor, Ruth, and invited her to dinner.
“What are we celebrating?” she asked.
I considered telling her the entire story.
“A full plate,” I said.
We ate on the porch beneath a clear evening sky. Ruth talked about learning to repair a leaky faucet by watching a library video. I told her about the workshop. We discussed books, local politics, and whether the rosemary would survive winter. The dinner was generous without being transactional. Neither of us kept score.
After she left, I washed the plates by hand and thought about the phrase Diane had used.
Our funds for you are exhausted.
She had wanted the sentence to make me feel poor in the only currency she believed mattered: acceptance by her family. She thought exclusion would remind me to be useful. Instead, it revealed that I had been buying access to a table where nobody intended to feed me.
The realization changed more than my finances.
At work, I stopped automatically volunteering for every difficult assignment. I mentored Leah without doing her work for her. I asked for appropriate staffing instead of proving my value through exhaustion. When senior partners praised me as the person who always saved troubled engagements, I asked why the firm kept planning engagements that required rescue.
That question led to new project controls and, eventually, a promotion.
The old Claire would have accepted more responsibility with quiet gratitude. The new version negotiated title, authority, compensation, and resources. I did not want the appearance of power without the ability to make decisions. I had lived that contradiction at home long enough.
Forgiveness came gradually. It did not arrive as a warm reunion or the disappearance of anger. It arrived the first week I realized I had not rehearsed an argument with Diane in my head. It appeared when Vanessa’s name came up and my pulse stayed steady. It emerged when I could remember good years with Mark without using them to question the decision to leave.
Forgiveness did not restore access.
That distinction protected me from the idea that healing required reconciliation with everyone who harmed me. I could hope Diane enjoyed her condominium. I could wish Vanessa professional success. I could respect Mark’s effort to change. None of those feelings required a renewed financial relationship or a seat at their dinner table.
Two years after the divorce, Mark’s mother mailed me a letter.
The envelope was addressed by hand. I recognized Diane’s careful script from hundreds of holiday cards. For several days, I left it unopened on my desk.
When I finally read it, the letter began with explanations. She had been lonely after her husband died. She feared losing the house. Vanessa struggled more than I knew. Mark felt responsible for everyone. Diane wrote that she never intended for the money to become such a problem.
Halfway through the second page, the tone changed.
I should not have lied about where the money went. I should not have allowed Mark to ask you for more. I should not have put an empty plate in front of you. I wanted to remind you that I was the mother of the family. Instead, I showed you that I did not know how to be one without controlling the table.
I stopped reading and looked toward the bay.
The apology did not erase the past. It also did not feel meaningless.
Diane wrote that the condominium was easier to manage. She had joined a widow-support group and begun helping with bookkeeping at the church, under the supervision of another volunteer. She and Vanessa were speaking less because Diane had stopped paying her bills. The sentence carried sadness rather than accusation.
At the end, she wrote: I hope someday you understand that I did care about you, even though I acted as if your value was what you gave us. You did not deserve that dinner.
I placed the letter beside the blue folder.
For a week, I considered my response. Part of me wanted to correct every remaining distortion. She still described certain choices passively, as if money wandered into cruise accounts on its own. Another part wanted to reward the apology with immediate warmth.
I chose something in between.
Thank you for writing. I appreciate your acknowledgment of the deception and the dinner. I am glad your new home suits you. I wish you peace and good health.
I did not include my phone number. I did not suggest a visit. Kindness did not require reopening the relationship before I was ready.
She never wrote again.
Not every answer led to no. I remained generous. I helped my younger cousin with a certification course after we wrote down the amount and expectations. I paid for Ruth’s meals while she recovered from surgery because she had no nearby family and never treated assistance as a debt I owed her. I contributed to emergency funds and scholarship programs.
The difference was choice.
Healthy generosity left me feeling connected, not erased. It could survive questions. It did not require secrecy or humiliation. It did not place the recipient above the giver or turn refusal into evidence of bad character.
I also learned to receive.
That proved harder than saying no. When Ruth brought soup during a flu, I almost insisted I was fine. When Leah offered to drive me home after a medical procedure, I began explaining that a rideshare would be easy. Both women looked at me with the same patient frustration.
“You know help is allowed to travel in both directions,” Leah said.
She was right.
My old role depended not only on giving too much but on needing too little. If I remained self-sufficient, nobody could disappoint me. If I paid, planned, and solved, I controlled the risk of relying on someone else. Real reciprocity required more courage than rescue because it required trust without control.
I practiced accepting small things. A ride. A meal. A neighbor watering plants while I traveled. I said thank you without immediately searching for a way to repay the exact value. The relationships did not turn into ledgers. Nobody presented an invoice during an argument.
That was another lesson the empty plate eventually taught me. The opposite of exploitation is not perfect independence. It is mutuality.
Years have passed since Diane set down that plate. I no longer remember every word spoken at the table, but I remember the white porcelain against the dark wood and the way Mark looked into his wineglass. I remember the first cold night in my office, adding transfer after transfer until the total reached $38,600. I remember the message saying I would always pay because I hated conflict.
They were right about who I had been.
I did hate conflict. I believed keeping peace was an act of love, even when the peace required my silence. I believed documentation could protect me without confrontation. I believed generosity would teach other people to be generous in return.
The empty plate corrected those beliefs.
Avoided conflict does not disappear. It accumulates interest.
Documents matter only when a person is willing to act on what they show.
Generosity reveals character, but not always the giver’s. Sometimes it reveals who respects a gift and who mistakes it for access.
People who hear the story often focus on the final line I gave Diane when she demanded the late mortgage payment.
My funds for you are exhausted.
They imagine it as a perfect act of revenge. It was not. Revenge would have required me to stay emotionally tied to her suffering. What I felt was release. I had finally stopped using money to purchase the possibility of being treated well.
The legal enforcement was not revenge either. Diane received notice, counsel, opportunities to cure, a voluntary sale, and the remaining equity. Carla’s rights were protected. The numbers were documented. The process did what the original agreement said it would do.
Consequences are not cruelty merely because someone hoped to avoid them.
The divorce was not revenge. Mark received a fair division of marital property and an opportunity to present his claims. I did not hide assets, empty accounts, or use my professional training to confuse him. The records that exposed his conduct also protected his legitimate rights.
That mattered to me.
Power used carelessly would have turned me into another participant in the same system. Diane controlled the table because she wanted everyone to feel their place. Vanessa used ridicule to reinforce that order. Mark used information and money to avoid choosing. I did not want freedom that depended on humiliating them in return.
I wanted a life where nobody needed an empty plate to feel important.
Today, the bay house has a larger dining table than when I moved in. I bought it after realizing I wanted friends to gather, not because I feared being alone. The table seats eight. Every chair fits comfortably, and every place receives food before anyone begins eating.
That is not a rule born from bitterness. It is a simple expression of the kind of home I choose to create.
Sometimes we serve crab. Sometimes soup, bread, and salad are enough. Guests bring dishes because they want to, not because their place depends on the contribution. We talk openly about allergies, costs, and who needs a ride home. Ordinary respect makes the evening easy.
On one summer night, I looked around the table at Ruth, Leah, two neighbors, my cousin, and a couple from the walking group. Laughter moved through the open windows. The plates were mismatched because I had stopped saving good dishes for people I needed to impress.
For a moment, I thought of Diane.
I hoped she had learned to sit at a table without controlling who deserved to eat. I hoped Mark understood that neutrality can become participation. I hoped Vanessa discovered that self-respect costs less than an image financed by somebody else.
Their lessons were no longer mine to supervise.
Mine was in front of me.
A full plate. An unlocked evening. People who liked me when I contributed and when I rested. Help moving in both directions. Questions that did not threaten the relationship. Kindness with boundaries strong enough to keep it kind.
After dinner, everyone carried something into the kitchen. Ruth wrapped leftovers. Leah loaded the dishwasher badly, and I resisted rearranging it. My cousin wiped the table while the others chose music. Nobody treated the work as invisible.
When the house was quiet again, I stepped onto the porch.
The bay reflected a thin line of moonlight. I could hear water against the pilings and the distant sound of a boat returning to shore. My phone rested inside, face down, with no emergency waiting to decide my value.
For six years, Mark’s family mistook my kindness for weakness because they believed kindness meant I would never withdraw consent. I had mistaken endurance for loyalty because I believed leaving the table would prove I did not belong.
We were all wrong.
Kindness without choice is compliance. Loyalty without honesty is captivity. Belonging purchased through silence expires the moment the payment stops.
Diane’s empty plate did not take my place in the family away.
It showed me that the place they offered had never been worthy of me.
Stopping the money revealed the price of their affection. Following the records returned responsibility to the people who had avoided it. Walking away gave me something no transfer, apology, or family dinner could provide.
The freedom to fill my own plate, choose my own table, and welcome only those who understood that generosity is a gift, never an entitlement.