My parents gave my sister a house for Christmas. I got $50 and a lecture: “Save up and buy your own house. Nothing comes for free.” I had spent twenty-two months paying the mortgage on the house we were sitting in. So I moved out and stopped the automatic payments. Twelve days later, Dad called me back to explain myself. I brought the receipts. He had a bank representative waiting on speakerphone.
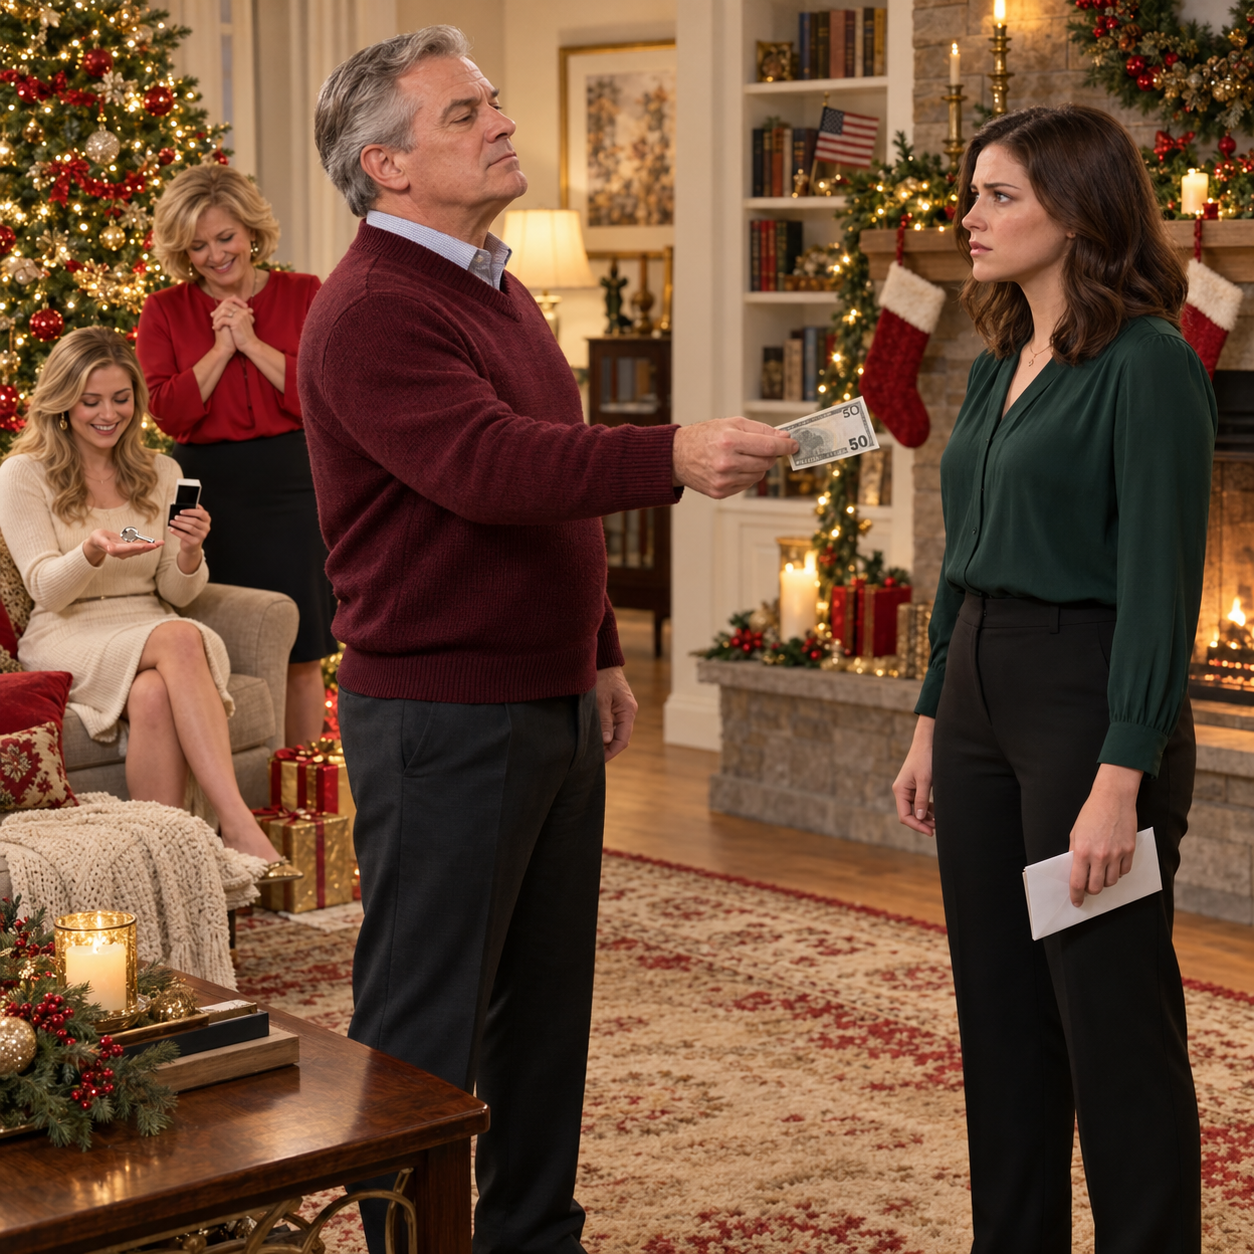
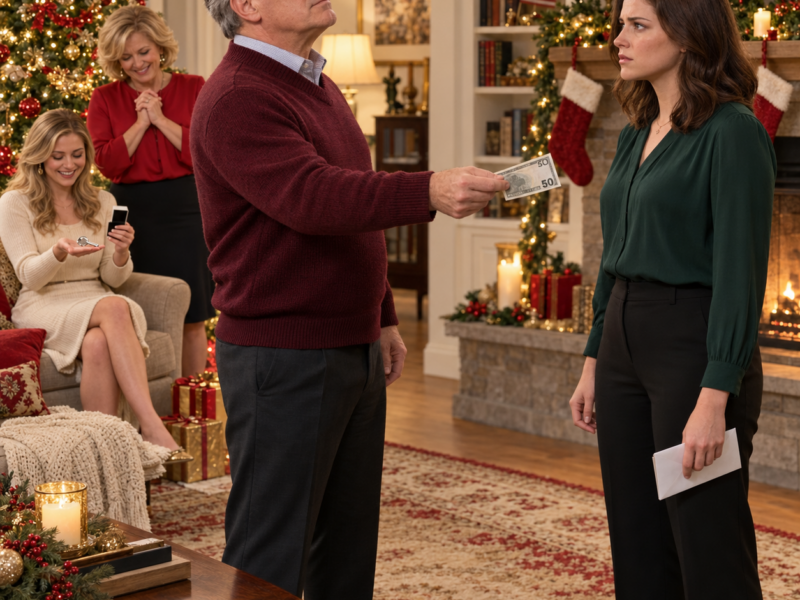
My father placed a folded fifty-dollar bill in my hand on Christmas Eve and laughed.
“Save it,” he said. “Maybe someday you can buy your own house. Nothing comes for free.”
Across the living room, my younger sister, Megan, was holding the silver key to a three-bedroom house our parents had just given her.
Everyone was smiling except me.
What none of them seemed to remember was that the mortgage, utilities, insurance, property taxes, groceries, and repairs on the house where we were celebrating had been coming out of my bank account for almost two years.
They thought the fifty dollars was a lesson.
It was. Just not the lesson my father intended.
My name is Emily Carter. I was thirty-four that Christmas, living in Columbus, Ohio, and working full time as a bookkeeper for a commercial landscaping company while finishing an accounting degree at night.
In my family, I had always been known as the dependable daughter.
Megan was the easy one.
That was how Mom described us when relatives asked about our childhood. She meant that Megan was cheerful, spontaneous, and charming. I was practical, cautious, and good in a crisis.
Those descriptions sounded harmless until I understood what they permitted.
Easy children received comfort because everyone enjoyed comforting them. Dependable children received responsibility because everyone assumed they could carry it.
I had been carrying my parents for twenty-two months by the time Dad handed Megan that key.
It started with a phone call on a Tuesday afternoon.
Dad worked as a shift supervisor at a distribution center on the west side of Columbus. His company had lost a contract, and his overtime disappeared almost overnight. Mom worked at a dental office, but an increase in health-insurance premiums had reduced what reached her checking account.
“We only need a little help until summer,” Dad told me. “Three or four months, tops.”
I was renting a modest apartment at the time. My lease was about to expire, and Dad suggested that I move back into my childhood bedroom. If I covered a few household expenses, I could save on rent while helping them through a temporary setback.
It sounded reasonable.
I created a spreadsheet before I packed my first box.
The original arrangement was simple. My parents would deposit their share into a household checking account. I would add $700 each month, which was less than my apartment rent, and I would organize the bills so nothing was late.
At first, it worked exactly as promised.
Then Dad’s deposits arrived a week late.
Mom’s contribution became smaller because of a dental procedure that insurance did not fully cover.
The furnace stopped working during a February cold snap. Dad promised to reimburse me if I put the $3,800 repair on my credit card. He paid back $500, then stopped mentioning it.
The following spring, their property-tax escrow was short by $2,700. I covered it because the lender’s notice frightened Mom.
By summer, I was paying the entire $1,620 mortgage.
An average of $340 went toward taxes and insurance. Utilities ran between $390 and $520, depending on the season. Internet cost $89. Groceries were usually another $650 because Dad preferred name brands and Mom enjoyed hosting Sunday dinners.
Every month, I told myself the same thing.
This is temporary.
My father’s overtime will return.
Mom will catch up next month.
Family helps family.
I picked up Saturday shifts. At night, after class, I handled bookkeeping for two small businesses from the desk in my childhood bedroom. I wore the same winter coat for a third season and postponed a dental crown because the deductible on my parents’ hail-damage claim had to be paid first.
Nobody forced me to enter the payments.
That fact became my father’s favorite defense later.
But responsibility inside a family is rarely enforced with a written threat. It is enforced with worry, history, and the knowledge that if you do not act, someone you love will face the consequence.
Dad understood that about me.
He also understood how to keep me from asking too many questions.
Whenever I raised the budget, he reminded me that I was saving money by living at home.
“You would pay rent anywhere else,” he said.
That was true, but it ignored the scale. I was not paying for one room. I was financing the entire household.
Mom thanked me often, usually while rushing to work or carrying laundry upstairs. Her gratitude felt sincere, but it never became curiosity. She did not ask how much I had saved. She did not ask whether I could afford school. She assumed that because the lights stayed on, I must be managing.
Megan lived twenty minutes away in a one-bedroom apartment near Grandview Heights. She worked in event coordination for a hotel and seemed permanently one unexpected expense away from panic.
Her car needed brakes. Dad paid for them.
Her rent increased. Mom covered the difference for three months.
Her dog needed surgery. The whole family contributed, including me.
None of those choices seemed outrageous individually. What hurt was the pattern.
When Megan struggled, the family gathered around her.
When I struggled, everyone praised my independence.
I did not see the house coming.
In October, Dad handed me a folder of tax documents and asked me to organize them before his appointment with an accountant. Inside, I found a preliminary statement for a $140,000 home-equity loan secured by my parents’ house.
The monthly payment was a little over $1,300.
I carried the page downstairs and found Dad watching football.
“What is this for?”
He barely glanced at it. “A financial opportunity.”
“That is a large loan.”
“I know what a loan is, Emily.”
“Can you afford another $1,300 payment?”
His eyes stayed on the television. “I am not discussing every financial decision with my daughter.”
I should have pressed harder.
Instead, I put the paper back in the folder.
The house was theirs. The debt was theirs. I had spent years being accused of overthinking everything, and I did not want another argument in which caution became disrespect.
Still, I saved a copy of the statement with the other household records. Bookkeepers keep records. It was habit, not strategy.
In November, Mom began whispering with Megan whenever I entered a room. Dad made several unexplained trips to a title company. Packages arrived containing kitchen towels, a welcome mat, and brass house numbers.
I assumed Megan was moving.
I did not assume our parents were buying the house.
On Christmas Eve, snow had begun falling before noon. It dusted the shrubs and softened the edges of the street, giving our ordinary suburban neighborhood the polished appearance of a holiday card.
I spent the morning cooking.
Mom had promised to make dinner, but the dental office scheduled emergency appointments, and Dad said he needed to pick up “one last thing.” I prepared the ham, sweet potatoes, green beans, rolls, and pecan pie while answering messages from a freelance client.
Megan arrived at four wearing a red sweater and carrying a bottle of wine.
“It smells amazing,” she said.
“You can thank me by setting the table.”
She saluted with the bottle. “Yes, ma’am.”
We were close in the uncomplicated way sisters can be when they avoid the subjects most likely to expose old wounds. We talked about work, movies, and her dog. We did not talk about money or why our parents still treated her like a twenty-year-old while treating me like a second parent.
Mom arrived just before five. Dad came in ten minutes later carrying a small box wrapped in gold paper.
He placed it beneath the tree and told Megan not to touch it.
She laughed. “That means it is for me.”
“You will find out after dinner.”
During the meal, Dad seemed almost giddy. He asked Megan about neighborhoods she liked and whether she preferred gas or electric stoves. She answered without recognizing the direction of his questions.
I noticed Mom watching him with a nervous smile.
After dessert, we moved into the living room. Dad handed me a flat white envelope first.
“Open yours,” he said.
Inside was a fifty-dollar bill.
I looked up, expecting another part of the gift.
Dad grinned. “For the house fund.”
Megan laughed because she thought he was joking. Mom gave a small, uncertain smile.
“Thank you,” I said.
Dad leaned back in his chair. “Save it. Maybe someday you can buy your own house. Nothing comes for free.”
The words landed strangely because I had spent that morning paying the electric bill for the room where he said them.
Before I could respond, he reached beneath the tree and gave Megan the gold box.
She tore the paper away and lifted the lid. A silver key lay inside on white cotton.
“What is this?”
Mom squealed and clapped her hands.
“A house,” Dad announced. “Three bedrooms, fenced yard, fifteen minutes from your office. We closed last week.”
Megan stared at him. “You bought me a house?”
“Consider it your real start in life.”
She began crying. Mom cried with her. Dad stood between them with one arm around each, smiling like a man in a photograph he had planned for months.
I remained on the couch holding fifty dollars.
For a few seconds, I tried to force the scene into a shape that did not hurt.
Megan needed housing. My parents had found a way to help. Gifts did not have to be equal. Love was not a ledger.
Then Dad looked at me and laughed again.
“Do not look so serious, Emily. Your sister needs help. You are good with money.”
That was when I understood that the inequality was not an oversight.
It was the point.
Megan received a house because she needed help.
I received a lecture because my help had made their generosity possible.
“How did you pay for it?” I asked.
Dad’s smile thinned. “That is private.”
“Did you use the home-equity loan?”
Mom turned toward him. “What loan?”
The room went still.
Dad looked furious, but only for a second. Then his expression settled into the patient superiority he used whenever he wanted me to feel childish.
“This is Christmas,” he said. “Do not turn Megan’s moment into an audit.”
“I asked one question.”
“And I said it is handled.”
Megan was still clutching the key. Her happiness had become confusion.
“Is something wrong?” she asked.
“Nothing is wrong,” Dad said. “Emily has trouble letting other people enjoy things.”
I looked at Mom. “Did you know about the loan?”
She glanced at Dad before answering. “Your father manages that side of things.”
That was not a yes.
I could have opened my banking app and shown them every mortgage transfer. I could have taken the loan statement from my files upstairs. I could have explained, in front of the Christmas tree, exactly whose labor supported Dad’s performance of generosity.
Instead, I folded the fifty-dollar bill, returned it to the envelope, and placed it in my purse.
“Congratulations, Megan,” I said.
Then I carried the dinner plates into the kitchen.
Dad followed me.
“Do not embarrass your sister.”
I kept rinsing plates. “I congratulated her.”
“Your face says otherwise.”
“What expression should I have while the man whose mortgage I pay tells me nothing comes for free?”
His voice dropped. “You live under my roof.”
“I pay for the roof.”
“You contribute because you are an adult. Stop acting like a victim.”
The kitchen faucet ran between us.
For years, I had believed the right explanation could make him understand. That night, I finally saw that misunderstanding served him. If he acknowledged what I paid, he would have to admit that the gift in the next room was partly financed by the daughter he mocked.
“All right,” I said.
He frowned. “All right what?”
“I understand.”
I turned off the water and dried my hands.
He mistook my calm for surrender.
The next morning, I began looking for an apartment.
I did not announce it. I did not threaten to leave or use the payments as leverage. I opened rental listings, calculated deposits, and scheduled three viewings.
The first place smelled like cigarette smoke despite the fresh paint. The second had a broken exterior lock. The third was a studio in a brick building near Clintonville, above a quiet insurance office.
It had thin walls, an unreliable dishwasher, and one narrow closet. Sunlight came through two tall windows and reached almost all the way across the room.
The rent was $1,050.
For the first time in twenty-two months, I calculated a budget based only on my own life.
Even after rent, utilities, tuition, groceries, insurance, and transportation, I would have money left.
I signed the lease on December 28.
That evening, I transferred my share of the upcoming household expenses one final time. I paid the mortgage through the end of the month and scheduled no future payments.
Then I removed my bank account from every automatic withdrawal.
Mortgage.
Electricity.
Gas.
Water.
Internet.
Insurance.
I printed confirmations and added them to a blue accordion folder.
On December 30, while Mom and Dad were at work, I packed my clothes, books, computer, and the small desk I had purchased myself. A friend from class helped me carry everything down the stairs.
I left the bedroom cleaner than I found it.
On the kitchen counter, I placed a list of account names, due dates, and customer-service numbers. At the top, I wrote: All automatic payments from my accounts have ended. January bills are your responsibility.
I included no accusation.
I took no furniture that belonged to them.
I simply left.
Mom called at 6:12 that evening.
“Where are you?”
“My apartment.”
“What apartment?”
“The one I rented.”
She was silent long enough for me to hear Dad speaking in the background.
“You moved out without telling us?”
“I left a full account schedule.”
“That is not what I asked.”
“I did not think I needed permission.”
Dad took the phone.
“Get back here and explain yourself.”
“No.”
It was the first time I had said that word to him without adding an excuse.
He hung up.
The calls began the following morning.
Dad called seventeen times before breakfast. Mom called nine. Megan called twice and sent a message asking whether I was safe.
By New Year’s Day, my phone showed more than two hundred missed calls.
The messages moved through predictable stages.
Where are the mortgage details?
Why did the electric company reject the payment?
You cannot make decisions like this without discussing them.
Your mother is sick with worry.
Stop punishing us over a Christmas gift.
I replied once.
The account schedule is on the kitchen counter. I am safe. I will not resume payments.
Dad answered within a minute.
You are being childish.
I turned off notifications.
My first night in the studio was quiet except for footsteps in the apartment above me. I sat on the floor because my secondhand table had not arrived and ate takeout noodles from the carton.
I expected guilt to overwhelm me.
Instead, I felt tired.
Then I slept for ten hours.
On January 2, Mom discovered that the regular mortgage payment had not been scheduled. The lender’s portal showed the account still current, but the next payment was due.
Dad apparently tried to move money from the household account and found less than $900.
That was when the volume of calls doubled.
By January 4, there were 502 missed calls, counting repeated attempts from the house phone, both cell phones, and Dad’s work number.
His final voicemail said, “Come here tomorrow and explain what you have done. The bank is calling about Megan’s house, and this is your responsibility.”
I listened twice.
Then I opened the blue folder.
I organized twenty-two months of statements, mortgage confirmations, utility bills, repair receipts, and transfers. I added the home-equity loan disclosure Dad had given me in October. I prepared a spreadsheet summarizing every dollar I could verify.
The total exceeded $51,000.
That figure did not include hundreds of hours of cooking, cleaning, errands, account management, and unpaid worry.
I did not assign those hours a price.
I no longer needed to prove that everything had been unfair. I only needed to establish what belonged to me and what did not.
I arrived at my parents’ house the next afternoon.
Megan’s car was in the driveway.
Inside, Mom stood beside the dining table holding two of my bank statements. Megan sat with the silver house key in front of her. Dad had a bank representative on speakerphone.
He did not greet me.
“Sit down,” he said.
I remained standing. “What is the call about?”
“The home-equity payment.”
“That account is not in my name.”
“Do not start.”
The bank representative cleared his throat. “Mr. Carter, I should clarify that I cannot discuss account details with anyone who is not a borrower.”
“My daughter managed our finances,” Dad said.
“That does not make her legally responsible for the loan.”
Dad muted the phone.
“You created this problem by moving without warning.”
I placed the blue folder on the table. “I gave you written notice that I stopped paying.”
“Four days is not notice.”
“You gave me no notice before borrowing $140,000 while I was covering your household.”
Mom looked sharply at him.
Megan stopped turning the key between her fingers.
Dad pushed the closing statement toward me. “We need to restructure the payments until your mother and I get organized.”
His hand hovered over the page, but I kept my palm flat against the paper.
“That is not the page you should be worried about,” I said.
For several seconds, no one moved.
The bank representative was still waiting on speakerphone.
Dad looked from my hand to my face. “What does that mean?”
I opened the folder wider.
Christmas Eve had been twelve days earlier, but I could still hear his voice as clearly as if we were standing beside the tree again.
Save up and buy your own house.
Nothing comes for free.
I pulled out the spreadsheet.
“Before we discuss Megan’s house,” I said, “we should establish what I was actually paying here.”
Dad folded his arms. “You paid rent.”
“No. I paid the mortgage.”
Mom stared at him.
I continued. “Every month, $1,620 for the mortgage. An average of $340 toward taxes and insurance. Utilities between $390 and $520. Internet was $89. Then groceries, the furnace repair, the plumbing emergency, the property-tax shortage, and the hail-damage deductible.”
Megan slowly sat back.
I turned the spreadsheet so all three could see it.
“At minimum, I paid more than $51,000 toward this household over twenty-two months.”
Mom’s lips parted. “Fifty-one thousand dollars?”
Dad shook his head. “That number is ridiculous.”
I slid the statements toward him. “That is why I brought receipts.”
He did not touch them.
Mom did.
She examined page after page, her expression changing with every line. I had never hidden the payments. That was the absurd part. She had simply never gathered them into one place.
“Richard,” she said, “did you know she was paying all this?”
He gave a frustrated shrug. “She was living here.”
“That was not my question.”
His eyes sharpened. “This is exactly why mixing family and money creates problems. Emily volunteered to help, and now she wants applause.”
“I do not want applause. I want you to understand why automatic payments stopped when I moved out.”
Dad leaned toward me. “You deliberately put us behind.”
“No. I stopped paying expenses for a house where I no longer live.”
“You knew we depended on that money.”
The contradiction settled over the table.
A minute earlier, I had merely paid rent.
Now I was responsible for keeping them solvent.
Mom heard it too.
“You said we could afford Megan’s house,” she whispered.
Dad looked impatient. “We can.”
The bank representative cleared his throat again through the speaker.
“Mr. Carter, should I remain on the line?”
Dad unmuted the phone. “One minute.”
Megan pointed to the closing statement. “What exactly did you borrow?”
Dad’s expression changed.
That was the moment I realized she truly had not known. She accepted the house without asking many questions, but she believed our parents had purchased it from savings.
Mom apparently believed the same thing.
Dad rubbed his forehead. “It is called using equity intelligently.”
“How much?” Mom asked.
He did not answer.
I did.
“One hundred forty thousand dollars.”
Mom gripped the back of a chair.
Megan went still.
Dad glared at me. “You had no right to dig through private finances.”
“You asked me to organize your tax documents. The loan statement was in the folder you handed me.”
The truth was painfully simple.
My parents had used savings for part of Megan’s purchase and taken a home-equity loan against their own residence for the rest. That might have been manageable if they had enough monthly income.
They did not.
Their budget worked only because I paid the mortgage, utilities, taxes, insurance, groceries, and repairs on their current home.
Dad had assumed that arrangement would continue indefinitely.
Megan stared at him. “You used this house to buy mine?”
“To help you,” he snapped.
“You told me my house was paid for.”
“It is. Your property does not have the loan. Ours does.”
Mom closed her eyes. “How much is the payment?”
“A little over $1,300 a month,” I said.
That was in addition to the original mortgage.
Mom sat down hard.
Dad unmuted the phone and asked what would happen if the payment was late. The bank representative explained the grace period, late fees, and consequences if the loan remained unpaid.
Nothing catastrophic would happen overnight, but the debt was secured by my parents’ home. There would be no exception because the borrowed money had purchased a Christmas present.
Dad ended the call abruptly.
Then he turned to me. “What do you want?”
“What?”
“You came with a folder. You planned this performance. What do you want from us?”
The question showed that he still did not understand.
“I did not plan anything. You called me 502 times.”
Mom lowered her eyes.
Dad continued. “Do you want an apology for Megan’s house? Fine. We are sorry your feelings were hurt.”
Megan winced.
“My feelings are not your financial problem,” I said.
“Then why are you here?”
“Because your voicemail said I needed to explain what I had done. I came to explain it. I moved out. I canceled payments from my account. That is what I did.”
I closed the folder halfway.
Dad laughed without humor. “And you expect us to suddenly cover everything?”
“Yes.”
The word landed harder than a speech.
Mom whispered my name. “Emily, we cannot handle all of it immediately.”
My anger softened when I looked at her.
Mom had participated in the favoritism. She hugged Megan while I held fifty dollars. She never asked how I managed two jobs and school. But she had also allowed Dad to control the finances because she trusted him.
That trust had cost her.
“I am not asking you to handle it immediately for me,” I said. “I am telling you that I will not handle it anymore.”
Dad struck the table with his palm. “Family helps family.”
Megan flinched.
I reached into my coat pocket and placed the Christmas envelope beside the spreadsheet. The fifty-dollar bill was still inside.
“You were right about something,” I said. “Nothing comes for free.”
His eyes dropped to the envelope.
For once, he had no answer.
Megan broke the silence.
“Can my house be sold?”
Dad turned toward her. “No.”
“If you borrowed against this house to buy mine, maybe we should sell mine and repay the loan.”
“Megan, stop.”
“I am serious.”
“It was a gift.”
“A gift you cannot afford.”
It was the first time I heard my sister challenge him directly.
His expression hardened. “You do not understand finances.”
She glanced at me. “Apparently neither did I.”
I expected satisfaction. Instead, I felt tired.
Megan benefited from our parents’ favoritism, but Dad had encouraged her to believe resources appeared because he loved her, not because someone else absorbed the cost.
She looked at me. “Did you know they were buying the house?”
“No.”
“Did you know about the loan?”
“I found the paperwork in October. I knew they borrowed money. I did not know it was for your house until Christmas.”
“Why did you not tell me?”
Because I had spent years avoiding the accusation Dad had thrown at me anyway: dramatic, selfish, ungrateful.
Because every time I questioned family finances, he reminded me that it was his house.
Because I thought adulthood meant enduring discomfort without making anyone else uncomfortable.
“I thought it was not my decision,” I said. “The loan is in their names. The house is theirs. Adults are allowed to make their own financial choices.”
Dad seized on the words. “Exactly.”
I looked at him. “And I am allowed to make mine.”
This silence felt different.
Not humiliating.
Final.
Dad tried anger first.
Before I reached my apartment, he sent six messages accusing me of abandoning the family. He said I had deliberately waited until after Christmas to create a crisis. He said a loving daughter would have given them six months to adjust.
I did not point out that he had given me no notice before adding $1,300 to a household budget I already carried.
I saved the messages and turned off my phone.
The following morning, Mom called from work. Her voice was unsteady.
“I do not know which bills are due when.”
“The schedule is on the counter. I can email another copy.”
“Your father says some passwords are not working.”
“The accounts in your names require you to reset them. Customer-service numbers are listed.”
“Could you come over and do it?”
I looked around my studio. Boxes covered the floor. My mattress was still without a frame, and three mugs were drying on a towel beside the sink.
For twenty-two months, any sign of worry in Mom’s voice had pulled me into action.
“I can talk you through the first one,” I said. “After that, you need to manage them yourselves.”
She was quiet.
“All right.”
We reset the electric account password together. I showed her where to find the amount due and how to schedule payment from her bank. The process took seven minutes.
“That was easier than I expected,” she admitted.
“Most of it is.”
The hard part had never been clicking the payment button. The hard part was having enough money in the account because a family had spent nearly two years avoiding the truth about what it could afford.
Dad moved from anger to bargaining.
He offered to let me return home without rent for six months if I restarted the mortgage transfer.
I reminded him that I had never been paying rent. I had paid the mortgage itself, along with most other expenses.
He changed the offer. If I paid only the mortgage, he and Mom would handle utilities and food.
“I have my own rent now,” I said.
“Break the lease.”
“No.”
“You would choose strangers over your family?”
“I am choosing responsibility for my own household. You taught me that adults do that.”
He ended the call.
Next came guilt.
Mom left a voicemail saying Dad had barely slept. An aunt texted that family disagreements should not threaten a roof over anyone’s head. A cousin I saw twice a year told me parents sacrifice everything for their children.
None of them knew about the $140,000 loan.
None knew I had paid more than $51,000.
Dad had told them only that I stopped contributing after becoming jealous of Megan’s Christmas gift.
I considered sending my spreadsheet to the entire family. The thought offered a brief, satisfying picture of everyone reading the totals and turning against him.
Then I closed the message.
Public humiliation would not repair the budget. It would give Dad a new argument about betrayal and allow the actual problem to become a competition over reputation.
I replied to my aunt with one sentence.
There is more financial information than you have been given, but I will not discuss my parents’ private accounts.
She did not answer.
Megan made a different choice.
Two days after our meeting, she called a real-estate agent named Carla Jenkins. Carla had represented the seller when my parents bought the house and knew that the purchase had closed only weeks earlier.
Selling immediately would be expensive. There would be commissions, title costs, transfer fees, and the likelihood of a modest loss. Megan had already moved some furniture into the house, though she had not ended her apartment lease.
Dad insisted that selling would be financial insanity.
Megan put the call on speaker while I sat beside her in my studio.
“Keeping a house the family cannot afford is also a financial decision,” Carla said carefully. “I cannot advise you about your parents’ loan. I can prepare a market analysis for the property you own.”
“Do that,” Megan said.
After the call, she stared at the blank wall above my desk.
“Are you angry with me?”
“Yes.”
She nodded as if she expected it.
“I am not angry that you accepted a gift,” I continued. “I am angry that you watched them treat me like I mattered less and never questioned why.”
Her eyes filled with tears. “I thought you did not need anything.”
“Everyone needs consideration.”
“I know that now.”
“Knowing now does not erase then.”
“I know that too.”
I appreciated that she did not ask me to say it was fine. An apology becomes another burden when the injured person must immediately make the apologizer comfortable.
Megan told me what our parents had said for years.
Emily is good with money.
Emily likes doing things herself.
Emily would be insulted if we offered help.
Emily is not sentimental.
Those statements had turned neglect into praise. They allowed everyone to admire my strength while benefiting from it.
“I should have asked you,” Megan said.
“Yes.”
She wiped her eyes. “What can I do now?”
“Make the decision about your house based on facts, not guilt. Do not sell it just to prove that you are on my side.”
“The facts say Mom and Dad could lose their home.”
“Then talk to a financial adviser who is not me.”
That boundary mattered. I did not want to become the unpaid manager of the crisis created by my unpaid management.
Megan scheduled an appointment with a housing counselor at a nonprofit agency. Mom agreed to attend. Dad refused at first, calling the counselor a stranger who could not understand family obligations.
He attended when Mom said she would go without him.
The counselor reviewed their income, debts, housing costs, and the likely proceeds if Megan sold. He did not shame anyone. He placed numbers in columns and asked what could be paid from actual monthly income.
The answer was uncomfortable.
Without my contributions, Mom and Dad could cover their original mortgage and essential household costs only if they cut spending and increased income. They could not also sustain the home-equity payment without draining what remained of their savings.
Megan could not make the payment either. Her salary covered her ordinary expenses, but property taxes, insurance, maintenance, and utilities on the new house would leave almost nothing for emergencies.
The gift had been unaffordable on both sides.
Dad argued that property values would rise.
The counselor agreed they might. Then he asked how Dad planned to meet next month’s payments while waiting for that increase.
Dad had no answer.
Megan listed the house three weeks later.
On the morning the sign went into the yard, Dad drove over and stood on the porch blocking the agent.
“You will regret this,” he told Megan. “You may never own a place this nice again.”
Megan held the screen door open. “Then I will rent.”
“You are throwing away what we gave you.”
“No. I am refusing to let you lose your house to protect mine.”
He looked at me, though I was standing near the curb and had said nothing.
“This is your influence.”
“The deed is in Megan’s name,” I replied. “The decision is hers.”
That was another lesson he had taught me.
Adults were allowed to make their own financial choices.
The house received an offer after twelve days, but the buyer withdrew following an inspection. The report identified an aging water heater, two windows with damaged seals, and a grading problem near the back patio.
Dad insisted the defects were invented to lower the price.
Carla brought in licensed contractors and obtained estimates. Megan reduced the price slightly and offered a credit at closing.
The second offer held.
Six weeks after listing, Megan signed the closing documents at a title office in Dublin, Ohio. Dad did not attend. Mom sat beside her, pale and quiet.
After commissions, closing costs, and the small loss, the proceeds repaid most of the home-equity balance. My parents still owed several thousand dollars, but the $1,300 monthly obligation was nearly eliminated.
When the transfer was complete, Megan placed the silver key on the title agent’s desk.
She looked relieved and heartbroken at the same time.
Both feelings were honest.
The sale did not rescue my parents from their original budget.
Dad picked up extra shifts at the distribution center. Mom reviewed every recurring charge and canceled subscriptions they barely used. They downgraded the cable package, switched insurance carriers, sold Dad’s second car, and stopped hosting large Sunday dinners.
The giant television disappeared from the living room. Dad had purchased it on a store credit card during the period when I paid the electric bill.
He complained that selling it brought only a fraction of what it cost.
That was true of many choices made for appearance.
Mom began packing lunch instead of ordering from nearby restaurants. She used the public library rather than buying every novel recommended by her book club. None of these changes alone solved the problem, but together they created room.
Most importantly, my parents paid their own mortgage again.
It was difficult.
It was also possible.
The world did not collapse when my checking account stopped supporting it.
My life changed more quietly.
During my first full month in the studio, I opened my banking app on payday and stared at the balance. For years, money arrived and disappeared almost immediately into someone else’s obligations.
Now I paid rent, utilities, tuition, groceries, insurance, and transportation and still had money left.
I created an emergency fund with an automatic transfer of $300 per paycheck.
Then I opened a separate savings account.
I labeled it DOWN PAYMENT.
Not because Dad told me to save for a house.
Because saving for one was finally possible.
I bought the winter boots I had postponed. They cost $86. I stood in the store for twenty minutes debating whether the purchase was irresponsible.
The old habit of scarcity remained even after the immediate cause was gone.
At checkout, I used my debit card and felt my stomach tighten.
Nothing terrible happened.
The mortgage remained paid because it was no longer mine.
I scheduled the dental crown. I replaced the six-year-old laptop that overheated during class. I bought a small dining table from a neighborhood resale group and carried it upstairs with the help of the seller’s teenage son.
These were not glamorous acts of freedom.
They were ordinary decisions made without calculating which family emergency would punish me for them.
My grades improved. I had spent semesters attending lectures after late-night bookkeeping sessions and weekends full of errands. Once I lived alone, I discovered how much mental space constant responsibility had consumed.
I could study for two uninterrupted hours.
I could sleep without hearing Dad call from downstairs because a password had expired.
I could leave cereal in the cupboard and know it would still be there the next morning.
At work, my manager, Linda Park, noticed the change.
“You seem lighter,” she said during a quarterly review.
I almost told her everything. Instead, I said I had moved closer to the office and improved my schedule.
She reviewed my performance and offered me responsibility for three additional commercial accounts, along with a raise.
For years, I had directed every increase in income toward my parents. This time, I increased my retirement contribution and my down-payment transfer.
Then I bought myself dinner.
Megan and I began meeting for coffee on Sunday afternoons.
At first, every conversation returned to the house. She worried Dad would never forgive her. She worried I would never trust her. She worried Mom secretly blamed both of us.
“You cannot solve every relationship in one month,” I told her.
“That sounds like something a person with spreadsheets would say.”
“A spreadsheet would give you a deadline. I am specifically refusing one.”
She smiled.
Over time, we talked about other things. She described difficult clients at the hotel. I told her about an accounting professor who treated punctuation like a moral issue. We compared apartments, recipes, and used furniture.
One afternoon, Megan admitted that being the favored child had not always felt secure.
“Dad helped me whenever I failed,” she said. “But he also expected me to stay the person who needed him.”
I considered that.
“He expected me to be useful and you to be grateful.”
“Neither left much room to change.”
That did not make our experiences equal. She had received resources and protection that I had been denied. But it helped me see favoritism as a system that assigned both of us roles.
I had been the foundation.
She had been the display.
Dad became angry whenever either of us stepped out of position.
Mom’s change came more slowly.
She called me every few days, often with a question she could answer herself. At first, I heard each call as an attempt to pull me back into management.
Sometimes it was.
Other times, she simply missed me and did not know how to say so without creating a task.
One evening, she called to ask whether the water bill could be paid by mail.
“The instructions are on the statement,” I said.
“I know.”
We sat in silence.
Then she said, “The house is very quiet.”
I leaned against my kitchen counter.
“Mine too.”
“Do you like it?”
“Most of the time.”
“I miss hearing you on the stairs.”
It was the first conversation we had that was not disguised as an emergency.
“I miss you too,” I said.
Missing her did not mean returning. Love did not cancel the boundary. I was learning that two truths could exist without one defeating the other.
Dad spoke to me only through brief messages for nearly three months.
He sent photographs of bills with questions that could have been answered by reading them. He forwarded an article about adult children helping aging parents. He informed me that family loyalty had once been considered a virtue.
I responded only to practical matters connected to accounts I had previously managed. Each answer was short and factual.
The gas account is in Mom’s name.
The escrow analysis explains the adjustment on page two.
I have no access to that password.
When he tried to reopen the argument, I stopped replying.
Boundaries felt rude at first because our family had defined unlimited access as kindness.
I kept them anyway.
In March, Dad appeared at my apartment without warning.
I saw him through the glass entrance door carrying a cardboard box. I considered pretending I was not home, but he had already spotted me on the stairs.
I opened the building door but did not invite him upstairs.
“What is that?”
“Your mail.”
“You could have called.”
“You do not answer.”
“I answer messages that require an answer.”
He looked past me into the hallway. “So this is where you live now.”
“Yes.”
“Small.”
“It is enough for me.”
He shifted the box from one arm to the other. Mixed among bank advertisements and catalogs was a letter from my college confirming my expected graduation date.
Dad saw it.
“You are still taking classes?”
“I graduate in August.”
He looked genuinely surprised.
“I thought you stopped when work got busy.”
I had attended evening classes for almost three years. The fact that he did not know should have hurt more than it did.
“No.”
“Why did you not tell us?”
“I did. More than once.”
He frowned as though searching his memory.
“Well,” he said finally, “that is good.”
“Thank you.”
For a moment, I thought he might apologize. Instead, he asked whether I could lend them $2,000 to clear the remainder of a credit card.
“No.”
His face closed.
“I would pay you back.”
“I am not lending family money.”
“After everything we did for you?”
There it was. The ledger he denied keeping whenever mine appeared.
“I am not discussing this in the doorway.”
“You have become cold.”
“I have become clear.”
I took the box, thanked him for bringing it, and closed the door.
My hands shook for fifteen minutes afterward.
Saying no did not feel powerful. It felt sad, unnatural, and necessary.
That distinction mattered. People often describe boundaries as moments of triumph, but many of mine felt like grief. I was not only refusing a request. I was letting go of the hope that the right sacrifice would finally make my father treat me fairly.
In April, Mom asked me to join her for lunch without Dad.
We met at a diner near her office. She ordered soup and spent several minutes tearing a cracker wrapper into narrow strips.
“I owe you an apology,” she said.
I waited.
“I knew you were paying a lot. I did not know the total, but I knew it was more than your share.”
“Why did you not ask?”
She looked out the window. “Because I was relieved.”
The honesty hurt, but I preferred it to an excuse.
“Your father said overtime would return. Every month, I thought the next month would be different. When you took care of things, I let myself stop looking.”
“You also helped him buy Megan a house.”
“I thought most of the money came from savings. He told me the loan was small and temporary.”
“Did the fifty dollars seem fair?”
Her eyes filled.
“No.”
“But you smiled.”
“I was trying to keep Christmas pleasant.”
“Pleasant for whom?”
She had no answer.
I let the silence remain. For most of my life, I rushed to rescue Mom from discomfort. That habit had protected her from facing choices that hurt me.
“I am sorry,” she said again. “Not only for the money. I am sorry I allowed being proud of you to become an excuse for neglecting you.”
That was the apology I needed.
Not because it erased anything. It did not.
But because it named the mechanism.
“Thank you,” I said.
She reached across the table and covered my hand with hers. I let her.
We did not discuss money again that day.
In May, my parents’ air conditioner failed during the first hot week of the year.
Mom sent me a photograph of the estimate. The replacement would cost nearly $6,000.
My first reaction was automatic. I opened my banking app.
My emergency fund contained enough to cover it.
I stared at the balance while the old logic assembled itself.
They are my parents.
The house will become unsafe in summer.
Mom has health problems.
I can help.
Then I called instead of transferring money.
“Have you requested a second estimate?”
“Not yet,” Mom said.
“Ask the utility company about assistance programs and financing. Check whether the system can be repaired safely before replacing it.”
“Your father says we need the top model because it is more efficient.”
“You should decide based on your budget.”
She hesitated. “Can you help us compare the estimates?”
That was different from asking me to pay.
“Yes. Email them.”
We compared three proposals. A reputable contractor repaired the system for $1,100 and explained that replacement could wait at least two years.
My parents used their new emergency fund.
I gave them time and knowledge, not money.
It felt like help rather than rescue.
That summer, I completed my final accounting course. The graduation ceremony was held in an auditorium on a humid August evening. Megan arrived first, carrying flowers from a grocery store because she knew I disliked elaborate bouquets.
Mom came alone.
“Where is Dad?” I asked.
“He said he had to work.”
I nodded, pretending it did not matter.
Halfway through the ceremony, I saw him enter at the back wearing his distribution-center uniform. He stood against the wall because the seats were full.
When my name was called, all three of them cheered.
Afterward, Dad approached with his hands in his pockets.
“Traffic was terrible,” he said.
“I am glad you came.”
He looked at my diploma cover. “You did this while working all those hours?”
“Yes.”
He seemed about to say something more, then Megan pulled us together for a photograph.
In the picture, Dad looked uncomfortable, Mom looked relieved, and Megan’s smile was too wide. I stood in the center holding the degree I had financed while financing everyone else.
It was not a perfect family photograph.
It was honest.
Two weeks later, I accepted a position with a regional accounting firm. The salary was almost thirty percent higher than what I had earned at the landscaping company. The benefits included tuition reimbursement, though my tuition was already paid, and a retirement match I intended to use fully.
My first instinct was to calculate how quickly the increase could stabilize my parents.
Then I corrected the thought.
How quickly could it stabilize me?
I increased my emergency fund target to six months of expenses. I paid the remaining balance on the furnace repair that still sat on my credit card. I set aside money for professional certification courses.
Every decision felt both selfish and sensible.
I was learning that the two words were not synonyms.
By autumn, Mom and Dad had built a three-month emergency fund. Mom called to tell me the total with the pride of someone announcing a promotion.
“Your father wants to replace the television,” she said.
“What do you want?”
“I want the emergency fund to remain an emergency fund.”
“Then tell him.”
“I did.”
Her voice carried surprise at her own courage.
Dad did not buy the television.
Megan moved into a smaller apartment near her job. She bought a secondhand dining table and sent me photographs of the pieces spread across the floor.
Two hours later, she sent another photograph. The table leaned noticeably to one side.
I called her.
“Did you follow the instructions?”
“I followed my instincts.”
“Your instincts produced a ramp.”
“I was hoping you would come fix it.”
“I will come help you fix it. You are holding the screwdriver.”
We spent Saturday afternoon taking the legs off and starting again. Megan did most of the work. When the finished table stood level, she ran her hand over the scratched wood as if it were expensive.
“I bought this myself,” she said.
“You did.”
“It feels better than the house did.”
I understood.
Ownership without agency had felt like another kind of debt.
Almost ten months after Christmas, I met with a mortgage adviser named Paul Whitaker. His office overlooked a strip mall on the edge of Columbus, and the walls were decorated with photographs of smiling buyers holding oversized cardboard keys.
I brought pay stubs, tax returns, account statements, and a folder of estimates.
Paul reviewed everything and asked about a series of large transfers from the previous year.
“Family support,” I said.
“Do those obligations continue?”
“No.”
He looked at me over his glasses. “Are you certain? Lenders care about recurring commitments, even informal ones.”
The question reached beyond underwriting.
“Yes,” I said. “I am certain.”
Based on my income, credit, and savings, I could realistically consider a small two-bedroom townhouse on the edge of the city if I waited another year and kept saving.
Nothing extravagant.
No dramatic reward waited around the corner because I finally chose myself.
There was a practical goal, a monthly target, and time.
I walked out holding a folder of projections.
Folders had become strangely important in my life.
One had exposed what I paid.
Another showed what I could build.
That evening, I opened the drawer where I kept important documents. The Christmas envelope was still there. I had never spent the fifty dollars.
For months, I thought I kept it because I was angry.
Eventually, I understood it differently.
It was a receipt from the night my family accidentally gave me something more valuable than a house key.
They showed me the difference between being dependable and being used.
Between helping someone and financing choices I was never allowed to question.
Between love and unlimited access to my labor.
I placed the envelope beside my down-payment statements and closed the drawer.
My father had said nothing came for free.
He meant it as a lesson for me.
In the end, all four of us had to learn it.
The first Thanksgiving after I moved out was held at Megan’s apartment.
Her dining table was small enough that our plates nearly touched in the center. The oven heated unevenly, and the turkey finished forty minutes later than planned. Mom brought sweet potatoes. I made pie. Dad arrived carrying rolls from a bakery.
No one discussed who had paid for what.
That silence was not avoidance. Each person had brought something within their means, and nobody had built the meal on a hidden obligation.
Before dinner, Dad stood near the window while Megan searched for a serving spoon.
“Your mother says you met with a mortgage adviser,” he said.
“I did.”
“What did he say?”
“If I keep saving, I may be ready next year.”
Dad nodded. “Interest rates could change. Do not rush.”
It was the kind of ordinary fatherly advice that once would have irritated me. This time, he offered it without ridicule or demand.
“I will be careful,” I said.
He looked down at his hands. “I went through the blue folder again.”
I waited.
“I did not realize how much you covered.”
I could have reminded him that he chose not to realize. The statements had always existed. The mortgage portal displayed my transfers. Each repair invoice carried my name.
I let him continue.
“I told myself you were contributing because you lived with us. Then things got tight, and I started assuming the payments would keep coming.”
“You did more than assume. You planned new debt around them.”
“I know.”
He said it without argument.
“When we decided to help Megan, I thought I was giving one daughter something she could not get herself. I told myself you did not need the same help.”
“And the fifty dollars?”
His face tightened.
“That was cruel.”
It was the first clean apology I received from him.
No explanation about a joke.
No complaint that I was sensitive.
No reminder that parents make mistakes.
Just the truth.
“Yes,” I said. “It was.”
He nodded. “I am sorry.”
I accepted the apology.
I did not offer money.
Those were separate things.
At dinner, Dad asked about my new job. He listened to the answer. Mom described the budget app she had learned to use. Megan announced that the hotel promoted her to senior events coordinator.
“Does that come with a raise?” Dad asked.
Megan narrowed her eyes playfully. “Are you planning to borrow against my dining table?”
For one alarming second, nobody moved.
Then Dad laughed.
“The table is safe.”
The tension broke.
It was not forgiveness completed in one meal. Families do not transform that neatly. Dad still became defensive when money was mentioned. Mom still sometimes called me before reading instructions. Megan still expected help faster than she offered it.
I still kept score in my head when I was tired.
But the pattern was visible now.
Once a pattern is named, participating in it becomes a choice rather than a reflex.
The following spring, I began visiting townhouses on weekends.
Some looked excellent online and disappointing in person. One had foundation cracks hidden behind storage shelves. Another sat beside a road so loud that conversation on the patio required raised voices. A third smelled strongly of air freshener, which the inspector later said could indicate an attempt to hide moisture.
I did not rush.
Dad had been right that nothing came for free. A low purchase price could conceal repair costs. A beautiful kitchen could distract from an aging roof. A generous loan could still be debt secured by something real.
The lesson no longer belonged to him.
It belonged to me in a form that did not require shame.
After four months, I found a two-bedroom townhouse in Westerville. It had beige siding, a small patio, and a maple tree near the front walk. The kitchen cabinets were dated, but the inspection was clean. The monthly payment, taxes, insurance, and association fee fit the conservative budget Paul had prepared.
I made an offer below asking price.
The seller countered.
I walked away.
Two days later, the seller accepted my original offer.
When I told my family, Mom cried. Megan shouted so loudly that I held the phone away from my ear. Dad asked sensible questions about the inspection, reserves, and closing costs.
Then he said, “I am proud of you.”
I closed my eyes.
For years, I thought those words would repair everything. They did not. They warmed one place inside me while leaving other places tender.
That was enough for the moment.
At closing, I sat across from a title agent with my own blue folder beside me. Every page was explained. Every amount matched the estimate. The down payment came from my account, built one transfer at a time after I stopped financing choices that were not mine.
The agent handed me two ordinary brass keys.
They were less elegant than the silver key Megan received on Christmas.
They felt heavier.
I drove to the townhouse alone and unlocked the front door. The rooms echoed. Afternoon light lay across the empty living room, and the maple branches moved beyond the window.
I did not have enough furniture.
I had no artwork for the walls. The refrigerator made a sound that concerned me, and the upstairs carpet would need replacing within a few years.
It was not a symbol of victory.
It was a home I could afford.
That distinction made it beautiful.
My family arrived later with pizza and folding chairs. Megan brought a toolbox. Mom brought cleaning supplies even though the place had been professionally cleaned. Dad carried a small wrapped box.
For an instant, the gold paper returned me to Christmas Eve.
He noticed my hesitation.
“It is not money,” he said.
Inside was a simple wooden key rack with four hooks. He had made it in a workshop at the distribution center.
On the back, written in black ink, were the words: For Emily’s home.
No lecture.
No comparison.
No joke at my expense.
“Thank you,” I said.
Dad looked toward the empty wall near the door. “I can hang it if you want.”
I handed him the level.
Megan held the rack while he measured. Mom stood behind them offering unnecessary instructions. I watched the three people who had hurt me try, imperfectly, to act differently.
Trying did not create a debt I owed them.
The old records showed what I had spent maintaining someone else’s choices.
The new one showed what became possible when I funded my own.
That did not make the earlier help foolish. My parents kept their home during a difficult period. The furnace worked. Taxes were paid. We shared meals and ordinary evenings I still valued.
The mistake was not helping.
The mistake was allowing temporary help to become an invisible entitlement.
Help needs truth.
It needs limits, informed consent, and a plan that does not depend on one person’s exhaustion.
Without those things, generosity can become a structure in which the most reliable person slowly disappears.
I had nearly disappeared inside my role.
The fifty-dollar bill brought me back into view.
Not because it was small, and not because Megan’s gift was large.
Because Dad’s joke revealed the story my family told about me. In that story, I had resources but no needs, strength but no feelings, obligations but no claim to consideration.
Leaving forced us to write a more honest story.
I was dependable.
I was also allowed to need rest.
Megan was loved.
She was also responsible for questioning gifts that transferred harm elsewhere.
Mom was caring.
She was also accountable for the comfort she protected at my expense.
Dad was frightened by financial failure.
He was also responsible for the deception and cruelty he used to hide it.
Those truths did not cancel one another.
They made change possible because nobody had to be reduced to a hero or villain.
Years later, when a younger coworker told me she had moved home to help her parents, I did not tell her to leave. I did not assume her family resembled mine.
I asked whether they had written down the arrangement.
She laughed. “They are my parents.”
“That is why clarity matters.”
We discussed a shared budget, a time frame, and what would happen if income changed. I advised her to maintain an emergency fund in her own name and to review the plan every three months.
Two weeks later, she thanked me. Her parents had not been offended. They were relieved to know what she could actually contribute.
A healthy family does not need confusion to prove love.
That may be the most important thing I learned.
At my parents’ fortieth anniversary dinner, Megan gave a short toast. She spoke about mistakes, endurance, and the strange ways a family can learn to become honest.
She did not mention the house.
She did not need to.
Dad looked at me across the table. Mom reached for his hand.
After dessert, he asked whether I remembered the Christmas envelope.
“Of course.”
“I think about it more than I would like.”
“So do I.”
“For a long time, I thought providing meant giving people impressive things. A house. A car. Something everyone could see.”
“What do you think now?”
He glanced at Mom, then Megan.
“I think providing can mean refusing to promise what you cannot sustain.”
It was not a dramatic statement. Nobody nearby heard it.
But I understood the distance he had traveled to say it.
“That is a good definition,” I replied.
When I drove home, the key rack waited beside my front door. The glass house ornament was packed away until December. My mortgage payment was scheduled for the following week, supported by an account I reviewed every month.
There was no secret source of money.
No hidden person absorbing the cost.
No gift built on somebody else’s silence.
I had a home, but the house was not the ending.
The ending was the ability to enter it without carrying everyone’s future on my back.
The ending was knowing that love could survive the word no.
The ending was understanding that being needed and being valued were not the same thing.
My father gave me fifty dollars and told me nothing came for free.
He was right in a way neither of us understood that night.
Freedom had a cost.
It cost the comfort of old roles, the approval I had chased, and the illusion that endless sacrifice would eventually produce fairness.
It was worth every dollar I stopped paying.