SHE CAN’T EVEN READ A BALANCE SHEET,” DAD LAUGHED AT THE MEETING. MOM NODDED: “STICK TO YOUR LITTLE JOB.” I OPENED MY LAPTOP QUIETLY. THE BOARD CHAIRMAN STOOD UP: WHY IS OUR $440M MAJORITY INVESTOR BEING DISMISSED?
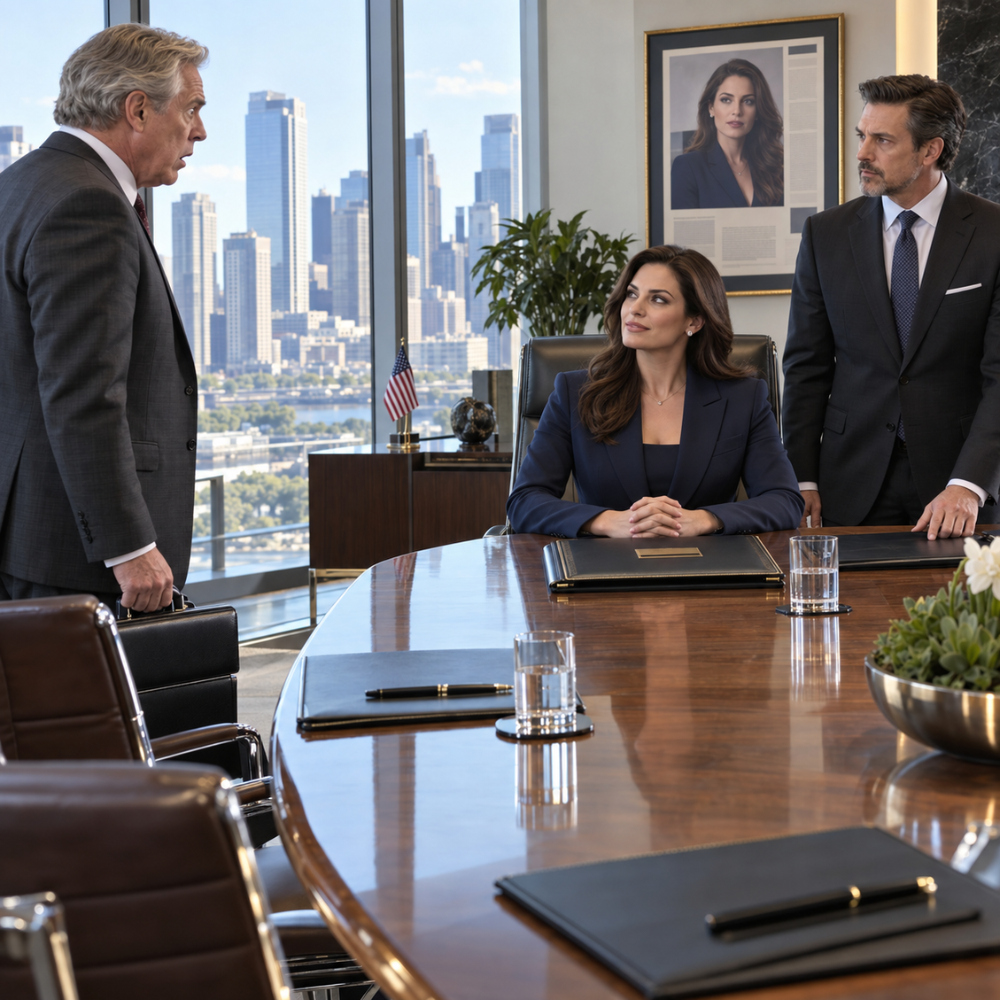
My parents laughed when I said I belonged in their emergency board meeting—then the chairman told them I owned 55% of their company.
The first sound after I said I had a right to be there was my father’s laugh.
It was not a cruel laugh, at least not by his standards.
It was worse.
It was affectionate.
The soft, condescending chuckle he had used my entire life whenever I said something he considered too ambitious, too complicated, or too far beyond what he believed I could understand.
The sound traveled down the long mahogany table and disappeared into the paneled walls of the executive boardroom at Chen Technologies.
Eleven people were seated around that table.
Only two of them were laughing.
My parents.
Everyone else knew why I was there.
I had deliberately arrived almost twenty minutes after the meeting started. Not because I enjoyed theater, but because I wanted the board to hear my parents’ restructuring proposal before I introduced mine.
I slipped into an empty chair near the back wall, set my laptop on the narrow credenza in front of me, and opened the financial model I had reviewed so many times that I could have rebuilt half of it from memory.
My mother noticed me first.
Patricia Chen had the kind of posture that could make a cashmere sweater look corporate.
She was sixty-one, elegant, controlled, with short dark hair streaked naturally with silver and a talent for making concern sound remarkably similar to criticism.
“Emma?”
Every face turned.
Mom lowered her glasses.
“What are you doing here?”
“I was invited.”
My father looked up from the packet in front of him.
Richard Chen was sixty-four, broad-shouldered, still physically energetic, with hands that looked slightly out of place in a boardroom because they belonged to an engineer who had spent half his life around soldering stations, manufacturing equipment, and prototype benches.
He laughed.
“Invited?”
“Yes.”
“Sweetheart, this is a board meeting.”
“I’m aware.”
“We’re discussing the future of the company.”
“I’m aware of that too.”
Mom’s expression tightened.
“Emma, this is not the time.”
I did not move.
Across the table, Marcus Webb, Chen Technologies’ chief financial officer, stared at his laptop as though it might offer him a trapdoor.
Thomas Harrison, the board chairman, slowly removed his reading glasses.
My parents did not notice.
Dad leaned back.
“I appreciate that you want to be supportive, but these are confidential discussions.”
“I understand.”
“Do you?”
Mom’s voice sharpened.
“Because we’re talking about debt restructuring, convertible financing, production-capacity constraints, working-capital requirements, and vendor exposure. This isn’t something you can understand from reading a few articles online.”
There it was.
My little family tradition.
Reduce whatever I knew until it fit comfortably inside their opinion of me.
I opened my laptop.
“Revenue is down forty-two percent over three years,” I said. “Gross margin has fallen below nineteen percent. You lost eighteen million dollars last quarter, and unless something changes, current unrestricted cash gives you roughly eight weeks before you breach payroll and lender obligations.”
The room went completely still.
My mother’s face changed first.
“Where did you hear those numbers?”
“The preliminary board package.”
“That package is confidential.”
“I know.”
My father’s voice hardened.
“Who gave it to you?”
Thomas cleared his throat.
“Richard.”
Dad held up one hand.
“No. I want an answer.”
“I reviewed the reports last week,” I said.
“That’s not what I asked.”
“Richard,” Thomas said again, more firmly.
Mom turned toward him.
“What?”
Thomas folded his hands.
“Perhaps we should explain why Emma is here.”
My father frowned.
“She doesn’t belong here.”
I closed my laptop halfway.
“I’m a voting member.”
Dad stared at me.
Then came the laugh again.
“A voting member.”
No one else laughed.
He looked around the table as if inviting support.
“Emma, you don’t own shares in Chen Technologies.”
Thomas spoke before I could.
“She owns forty-seven percent.”
The sentence entered the room quietly.
It landed like a dropped steel beam.
My mother turned her head very slowly.
“What did you say?”
Thomas did not raise his voice.
“Emma owns forty-seven percent of Chen Technologies. She has been the company’s largest single shareholder for approximately six months.”
My father stopped smiling.
For several seconds, he simply looked at Thomas.
Then at me.
Then back at Thomas.
“That’s impossible.”
“It is not.”
“This company is closely held.”
“Yes.”
“Any significant transfer requires compliance review.”
“It received one.”
“I would know.”
Marcus finally spoke.
“Not necessarily.”
Dad looked at him.
Marcus swallowed.
“The shares were acquired through eligible transfers from the employee option pool, former directors, and permitted secondary sales. None individually required founder approval under the amended shareholder agreement.”
Mom looked at me.
“You don’t have the money.”
It was almost reflexive.
Not How?
Not Why?
You don’t have the money.
I had heard versions of that sentence since childhood.
You cannot afford that.
You do not understand that.
That is not your field.
Leave this to people who know what they’re doing.
I said, “At the company’s last formal valuation, forty-seven percent was theoretically worth around four hundred forty million dollars.”
Mom stared.
Dad shook his head.
“That valuation is outdated.”
“I agree.”
The board members watched.
“Based on current performance,” I continued, “I would mark the business closer to three hundred twenty million in enterprise value before restructuring.”
My father’s eyebrows lifted.
“That’s ridiculous.”
“Which means, on paper, I overpaid for several of my purchases.”
Mom gave a short, breathless laugh.
“You expect us to believe you spent hundreds of millions buying our company?”
“No.”
I looked directly at her.
“I expect you to understand that I invested through several acquisition entities over fourteen months, using a combination of personal capital, financed positions, and partnerships where I control the voting rights.”
Marcus was typing rapidly.
He stopped.
“Oh, my God.”
Dad turned.
“What?”
Marcus rotated his laptop slightly.
“Three LLCs.”
I nodded.
“North Beacon Holdings. Pine Harbor Capital Partners. Meridian Technical Investments.”
Marcus stared at me.
“You control all three.”
“Yes.”
“How did we miss this?”
“You didn’t miss the transactions. You missed the common control.”
Dad shoved back his chair.
“This is some kind of game.”
“No.”
“What are you trying to prove?”
“Nothing.”
“You secretly buy half our company, walk into an emergency board meeting, and tell me you’re proving nothing?”
His voice was rising.
Thomas intervened.
“Richard, every transaction has been reviewed. I sold part of my own position to one of Emma’s entities.”
Dad turned toward him.
“You knew?”
“Yes.”
“And said nothing?”
“The buyer had no obligation to disclose private family relationships beyond the corporate filings.”
Mom stared at Thomas as though he had personally betrayed her.
Then she looked at me.
“You did this behind our backs.”
“I did it through legal market transactions.”
“You knew we would object.”
“Yes.”
My father pressed both hands to the table.
“Why?”
I could have answered immediately.
Instead I looked around the room.
Some of the people there had known me since childhood.
Thomas Harrison had attended my fifth birthday party.
Daniel Rothstein had brought his family to our house for Thanksgiving twice.
Marcus had once helped me with a high school economics project because my father was traveling.
All of them had watched me grow up.
Most had also watched my parents continue treating me like a child long after I became something else.
I said, “Because I tried speaking to you first.”
Dad scoffed.
“When?”
“Three months ago.”
His expression changed slightly.
I continued.
“I called you after the Q4 reports started circulating. I told you I was concerned about cash flow, client concentration, and the delayed avionics line.”
“You asked questions.”
“I told you the company was overleveraged.”
“You did not have the complete picture.”
“I had enough of it.”
Mom cut in.
“Emma, you work in investments. That doesn’t make you an expert in aerospace manufacturing.”
My father nodded.
“Exactly.”
Thomas leaned forward.
“Patricia.”
“What?”
“You should probably know Emma is a managing partner at Quantum Capital.”
The silence returned.
Mom blinked.
“She’s what?”
“Managing partner.”
Dad looked at me.
“You’re an analyst.”
“I started as one.”
“When?”
“Five years ago.”
“You told us you worked at a boutique investment firm.”
“I do.”
“You never said you were a partner.”
“You never asked.”
My mother’s face went pale.
Thomas continued, perhaps because he had decided incomplete disclosure was no longer helping anyone.
“Emma has run Quantum’s industrial technology portfolio for more than two years. The strategy returned forty-three percent last year.”
Mom looked at him.
Then at me.
“That’s not possible.”
It should not have hurt.
At twenty-eight years old, after everything I had built, those three words should have rolled off me.
They did not.
Because I was still their daughter.
Some part of me was still seventeen, standing in the kitchen with an MIT acceptance letter while my father said computational finance sounded unnecessarily theoretical.
I kept my voice level.
“It is possible.”
“You would have told us.”
“Why?”
Mom flinched.
“Because we’re your parents.”
“So you could call it my little investment job?”
“I have never said that.”
“You called Quantum ‘that boutique place in Boston’ at Thanksgiving.”
“It is a boutique firm.”
“You told Aunt Ellen I mostly build spreadsheets.”
Mom’s mouth tightened.
Dad said, “This isn’t the place for family grievances.”
I looked at him.
“I agree.”
“Then stop turning this into one.”
“I’m not.”
I opened another document.
“I’m here as a shareholder.”
Dad stared.
“Forty-seven percent does not give you control.”
“No.”
I looked toward Daniel Rothstein, seated three places from Thomas.
Daniel lowered his eyes.
“I closed another purchase this morning.”
Mom’s head turned.
“How much?”
“Eight percent.”
The boardroom erupted.
Not shouting exactly.
A dozen surprised voices at once.
Chairs shifted.
Paper moved.
Marcus started typing again.
Thomas raised his voice.
“Everyone, please.”
I waited.
When the room settled, I said:
“That brings my voting position to fifty-five percent.”
My father did not speak.
Mom sat completely still.
For the first time in my life, neither parent had an immediate correction.
I was the majority shareholder of Chen Technologies.
The company they had created in our garage twenty-five years earlier.
The company whose logo had been on our Christmas cards.
The company my father referred to as his third child when he was in a sentimental mood.
The company they had spent my entire life telling me I did not understand.
I had not planned to take control of it.
Not originally.
Fourteen months earlier, I had planned to make a small investment.
That was before I understood how close they were to losing everything.
Chen Technologies began in 2001 in the detached garage behind the first house my parents owned in Woburn, Massachusetts.
I was three.
I remember very little from that period directly.
Most of what I know came from family stories and old photographs.
Dad sitting at a folding workbench under fluorescent shop lights.
Mom at an ancient desktop computer balancing purchase orders after midnight.
Circuit boards stacked in anti-static bags beside boxes of diapers.
A whiteboard covered with component numbers.
My father had been an electrical engineer at a defense contractor.
My mother had worked in procurement.
They saw a niche.
Smaller aerospace companies needed specialized low-volume, high-reliability circuit boards, but larger manufacturers disliked short production runs.
My parents built a business around doing difficult things other suppliers considered inconvenient.
At first, every order mattered.
Dad designed.
Mom sourced components.
A retired engineer named Leonard Price helped with quality systems.
Thomas Harrison provided the first significant outside investment.
By the time I was ten, Chen Technologies had moved into a small industrial building north of Boston.
By fourteen, they had eighty employees.
By eighteen, more than two hundred.
The company’s boards went into navigation systems, aircraft communication units, weather satellites, and specialized research equipment.
My parents were brilliant.
I want that understood.
Nothing that happened later erased what they had accomplished.
My father could look at a production defect and often identify the cause before the quality report reached his desk.
My mother could negotiate a component contract so effectively that suppliers sometimes left meetings smiling without realizing how much margin she had taken away from them.
They built something real.
They also built a family culture around it.
Chen Technologies was not simply their company.
It became their measure of seriousness.
Engineering mattered.
Manufacturing mattered.
Physical products mattered.
Things you could hold mattered.
Finance, software, economics, consulting—those were adjacent activities.
Useful, perhaps.
But not real work in the same sense.
I loved numbers.
Not accounting specifically.
Systems.
Probability.
Markets.
I liked the way risk behaved when thousands of variables interacted.
At thirteen, I built a crude model to predict baseball outcomes and tried to explain it to Dad.
He smiled.
“That’s cute.”
At fifteen, I entered a state mathematics competition and placed first.
Mom framed the certificate.
Dad said I should consider engineering.
At seventeen, I told them I wanted to study computational finance and applied mathematics.
Dad frowned.
“At MIT?”
“If I get in.”
“You could study electrical engineering there.”
“I could.”
“That would actually connect to something.”
“I don’t want to design circuit boards.”
He looked personally wounded.
“What’s wrong with circuit boards?”
“Nothing.”
“Then why finance?”
“Because I like it.”
My mother tried to help.
“Maybe she can minor in it.”
I remember looking at both of them.
This was my life.
They were discussing it like a product configuration.
I got into MIT.
Financial aid covered part of it.
My parents covered the rest, and I have never pretended otherwise.
They helped me enormously.
But every tuition payment arrived wrapped in commentary.
“I still don’t understand why you need this many statistics classes.”
“Don’t let Wall Street turn you into someone who thinks money appears by magic.”
“Someday you’ll understand the difference between investing and actually building something.”
I graduated near the top of my class.
Quantum Capital recruited me.
It was a specialized investment firm in Boston with a reputation for buying positions in complicated industrial and technology companies that larger funds did not fully understand.
At my graduation dinner, Dad asked the managing director who had recruited me:
“What exactly will Emma do?”
He explained.
Dad listened.
Then said:
“So research.”
I closed my eyes.
The managing director smiled politely.
“Research that moves several hundred million dollars.”
Dad laughed as though it were a good joke.
I started at Quantum the following July.
I loved it immediately.
Not because of the money.
Because the work demanded the exact combination of skills my parents had dismissed as too abstract.
Technology.
Mathematics.
Operational analysis.
Market behavior.
Capital structure.
You could not understand an industrial company by reading financial statements alone.
You had to understand what the company made.
How.
With which equipment.
Using whose components.
At what yield.
At what capacity.
With what defect rate.
Under what customer-certification requirements.
I had grown up hearing my parents discuss all of those things over dinner.
They thought I had not listened because I rarely joined the conversation.
I had listened to everything.
The first major investment idea I brought to Quantum was a sensor manufacturer in New Hampshire.
My senior partner told me the margins looked terrible.
“They are.”
“Then why do you like it?”
“The margins look terrible because they are running at forty-eight percent capacity.”
“So?”
“The new customer contract takes them to seventy-five.”
“Everyone knows about the contract.”
“No. Everyone knows the revenue estimate. They’re missing the production leverage.”
He stared.
I continued.
“The fixed-cost absorption changes the entire business.”
He let me build the model.
Quantum invested.
Eighteen months later, we exited with a return above seventy percent.
That changed my career.
I was promoted.
Then promoted again.
By twenty-six, I was a partner.
By twenty-seven, managing partner over a specialized technology portfolio.
My compensation grew with performance.
So did my personal investments.
I did not spend much.
My parents assumed this meant I was not making much.
I lived in a two-bedroom condo in Cambridge instead of buying a large house.
I drove a Volvo that was six years old.
I took the T when it was easier than driving.
I wore expensive clothes only when the situation required them and had no interest in posting photographs of vacations online.
At family dinners, my mother still asked whether I was “enjoying the little firm.”
I eventually stopped correcting her.
That was probably my mistake.
Silence protects peace in the short term.
Sometimes it also protects people from information they need.
Three years before the board meeting, I began investing personally outside Quantum’s funds, fully disclosed under our compliance rules.
Not wild bets.
Industrial technology companies I understood.
A battery-management company.
A defense software supplier.
A robotics integrator.
A semiconductor-testing business.
I rolled profits forward.
My signing bonus, early equity compensation, carried interest, and investment returns accumulated faster than my lifestyle expanded.
By twenty-eight, my personal net worth had become large enough that I stopped looking at the number emotionally.
Numbers that large become abstract until attached to something physical.
A house.
A payroll.
A factory.
Or, eventually, my parents’ company.
I first realized Chen Technologies was in serious trouble at a Thanksgiving dinner.
Not because anyone told me.
Because Dad complained about a supplier.
We were in my parents’ house in Lexington.
Mom had made turkey despite insisting every year that turkey was overrated.
My cousin was discussing college applications.
Dad was drinking cabernet and talking about capacitor lead times.
“Taiwan supplier wants thirty percent upfront now.”
I looked up.
“Why?”
Dad shrugged.
“Everybody wants better terms.”
“Did they change terms for all customers?”
“How would I know?”
“You could ask.”
He frowned.
“Emma.”
“What?”
“Let the adults finish.”
I was twenty-seven.
I nearly laughed.
Instead I looked at Mom.
She gave me the familiar expression.
Not tonight.
So I stopped.
But the comment stayed with me.
Strong suppliers do not suddenly demand upfront payment from twenty-five-year customers unless something changes.
Either their own financing worsens, or they become worried about yours.
Two weeks later, I pulled Chen Technologies’ public filings and lender disclosures available through industry databases.
Then I accessed what I legally could through shareholder channels once I began buying eligible stock.
The picture worsened quickly.
Receivables aging.
Inventory increasing.
Capital expenditure delayed.
Two major customers reducing orders.
Debt rising.
Research spending falling.
That last one worried me most.
Technology manufacturers sometimes respond to financial pressure by cutting research because research does not help next quarter.
Then, two years later, they discover they have saved their way into irrelevance.
Chen was doing exactly that.
My parents had spent decades succeeding because their designs were more specialized than overseas competitors.
Now lower-cost manufacturers had improved.
Instead of moving higher up the technology chain, Chen cut R&D.
They were defending yesterday’s advantage.
I called Dad.
“Can we have lunch?”
“Sure.”
“About the company.”
A pause.
“Why?”
“I’ve been looking at the sector.”
“You always look at sectors.”
“I’m concerned.”
Dad sighed.
“Emma, our company is not a stock chart.”
“I know.”
“You don’t understand customer relationships in aerospace.”
“I understand declining backlog.”
His voice changed.
“Where are you getting information?”
“Industry data.”
“Stop worrying.”
“Your competitors are spending twelve to fourteen percent of revenue on product development. Chen is under five.”
“That is temporary.”
“Why?”
“We have cash priorities.”
“That’s exactly my concern.”
He laughed softly.
“There are parts of business you cannot see from Boston.”
I wanted to tell him I was sitting in Boston managing more money than Chen Technologies had ever been worth.
I did not.
Instead I said, “Let me review the company with you.”
“No.”
“Why?”
“Because you’re my daughter.”
“I don’t understand.”
“I don’t want you looking at your parents’ company like one of your investments.”
That sentence mattered.
At the time, I thought he was protecting himself.
Later, I realized he was protecting his identity.
If I evaluated Chen Technologies professionally, I might discover my parents were failing professionally.
They could tolerate a stranger saying that.
Not me.
I began buying shares six weeks later.
Not because I intended a takeover.
Because I believed the company was undervalued if it could be fixed.
My first purchase was four percent.
Then three more.
An early employee retiring to Florida sold part of his stake.
I bought it.
One former board member wanted liquidity for estate planning.
I bought his shares too.
Thomas called after I crossed fifteen percent.
“What are you doing?”
“Investing.”
“In your parents?”
“In the company.”
“Do they know?”
“No.”
“They’re going to hate this.”
“They already hate when I discuss the company.”
Thomas was quiet.
Then he said, “You think it can be saved?”
“Yes.”
“How?”
“Not under current management.”
Another silence.
“You mean Richard and Patricia.”
“Yes.”
He sighed.
“I helped them start this company.”
“I know.”
“They’re going to consider that betrayal.”
“I know.”
“Are you sure?”
“No.”
That answer seemed to satisfy him more than certainty would have.
He agreed to sell me part of his stake three months later.
By then, I owned twenty-eight percent.
At thirty-five percent, Marcus noticed unusual ownership concentration.
He called me privately.
“Emma.”
“Hi, Marcus.”
“I assume you know why I’m calling.”
“Probably.”
“You are acquiring this company.”
“Yes.”
“Do Richard and Patricia know?”
“No.”
He exhaled slowly.
“I’m going to need stronger coffee.”
“Fair.”
“Are you planning a hostile takeover?”
“No.”
“That answer is not as comforting as you think.”
“I’m planning to preserve the business.”
“By owning it?”
“If necessary.”
Marcus did not laugh.
That was why I respected him.
He asked:
“Have you modeled what preservation costs?”
“Yes.”
“How bad?”
“Worse than you think.”
That was the beginning of our informal alliance.
Not against my parents.
Against bankruptcy.
By then, Chen Technologies had lost an important avionics customer after repeated delivery delays.
Their revolving credit line was nearly exhausted.
One production line desperately needed retooling.
Employee turnover among younger engineers had doubled because competitors paid more and offered newer projects.
The company still possessed excellent certifications, strong customer history, valuable manufacturing capability, and a skilled workforce.
But capability without capital becomes a museum.
Quantum’s investment committee agreed to review a rescue financing.
I recused myself from the final independent approval vote but prepared much of the operating analysis.
The proposal was aggressive.
Two hundred million dollars of new capital.
New machinery.
Research funding restored.
Debt refinanced.
New executive leadership.
A convertible structure that protected Quantum if the turnaround failed.
My parents rejected the concept before even seeing the full term sheet.
Dad called outside capital “predatory.”
Mom said private investment firms did not understand manufacturing culture.
Then another opportunity changed the equation.
Asteron Space Systems, one of the fastest-growing commercial satellite companies in the country, issued a supplier inquiry for next-generation high-reliability boards used in low-orbit communications hardware.
Most manufacturers saw a difficult contract.
Thin early margins.
Enormous certification demands.
Rapid capacity requirements.
I saw Chen Technologies.
Their legacy process controls were unusually well suited.
Their engineering team had experience in extreme-vibration environments.
They already held several relevant certifications.
What they lacked was the capital to fulfill the volume.
I contacted Asteron through Quantum.
Four months of meetings followed.
Technical audits.
Capacity planning.
Pricing models.
Site assessments.
At first, I did not tell Asteron I was Richard and Patricia Chen’s daughter.
It was irrelevant.
I was representing investment capital with a potential turnaround plan.
Their vice president of supply chain eventually asked:
“Why are you so committed to this manufacturer?”
I answered:
“Because the capability is better than the balance sheet.”
That was true.
By the week of the board meeting, we had a verbal commercial commitment.
If Chen Technologies completed the restructuring and installed the proposed equipment, Asteron would move forward with a three-year supply contract worth approximately $340 million, subject to final legal and technical terms.
That contract could save the company.
But only if my parents stopped trying to run it the way they had in 2008.
Back in the boardroom, Dad was staring at me.
“If you actually control fifty-five percent, what exactly do you think you’re going to do?”
The question was quieter than before.
That made it more dangerous.
I turned my laptop toward the table.
“Approve the restructuring package.”
Mom frowned.
“What restructuring package?”
Thomas slid a document from his stack.
“The Quantum proposal.”
Dad looked at him.
“You told me that proposal was preliminary.”
“It was.”
“And now?”
“It’s funded.”
I spoke.
“Two hundred million dollars.”
Mom stared.
“For what equity?”
“Convertible debt initially. Performance triggers determine conversion.”
Dad grabbed the term sheet.
“This could give Quantum sixty-five percent.”
“If the operating milestones are missed.”
“So we become minority shareholders.”
I looked at him.
“You already are.”
His face tightened.
Mom whispered, “Emma.”
I regretted the sentence immediately.
Not because it was false.
Because it was unnecessarily sharp.
I took a breath.
“The capital gives the company twenty-four months of runway, funds the new manufacturing line, restores R&D, refinances the worst debt, and protects existing pension obligations.”
Dad shook his head.
“Under your control.”
“Under professional management.”
“What does that mean?”
“I want Thomas to remain board chair.”
Thomas said nothing.
“Katherine Walsh would come in as CEO.”
Mom sat upright.
“Absolutely not.”
Dad dropped the term sheet.
“Katherine Walsh?”
“Yes.”
“She works for Innovatech.”
“She resigned last quarter.”
“She is a competitor.”
“She was.”
“She doesn’t know our company.”
“She knows manufacturing.”
“She doesn’t know our culture.”
Marcus spoke quietly.
“Our culture is currently producing eighteen-million-dollar quarterly losses.”
Mom turned on him.
“Whose side are you on?”
Marcus met her eyes.
“The company’s.”
The room went silent again.
I continued.
“Katherine took Innovatech from fifty million in revenue to more than eight hundred million in seven years. She rebuilt their supply chain, expanded aerospace certifications, and doubled operating margins.”
Dad said, “She’s not an engineer.”
“No.”
“So you want someone who doesn’t understand our technology running a technology company.”
“I want engineers focused on engineering.”
His eyes narrowed.
“What does that mean for us?”
I looked at both of them.
This was the part I had rehearsed dozens of times and still hated.
“You stay on the board.”
Mom did not blink.
“You retain meaningful equity.”
Dad’s face became hard.
“Meaningful.”
“You remain involved in engineering and product strategy if you choose.”
“If we choose?”
“Yes.”
“This is our company.”
“It is a company you founded.”
His hand hit the table.
“Don’t play language games.”
“I’m not.”
My own voice rose for the first time.
“You built something extraordinary. You also nearly drove it into bankruptcy because you refused to admit the skills required to invent a company are not automatically the skills required to manage it forever.”
No one moved.
Dad stared.
Mom’s eyes filled, but she blinked the tears away before they formed.
I lowered my voice.
“I’m trying to keep it alive.”
“By taking it from us.”
“No.”
“Then what do you call this?”
“Restructuring ownership and management before creditors do it for us.”
He pushed back his chair.
“You sound exactly like every private equity person I ever hated.”
“That may be because some of them occasionally understand capital structure.”
His eyes flashed.
Thomas intervened.
“Richard.”
Dad ignored him.
“You’re twenty-eight.”
There it was.
The last safe argument.
Age.
“You’ve worked five years.”
“Yes.”
“And we’re supposed to trust you with a company that took twenty-five years to build?”
“I manage six hundred twenty million dollars in my portfolio strategy.”
Mom’s face changed again.
I continued.
“The broader funds I oversee have more than four billion under management.”
Dad stared.
“That isn’t your money.”
“No.”
“Then stop talking like it is.”
“I wasn’t.”
I looked directly at him.
“My personal portfolio is substantial. Chen Technologies represents roughly seventy percent of it now.”
Thomas looked at me sharply.
He knew I had invested heavily.
He had not known how heavily.
Mom whispered:
“You put seventy percent of everything you have into this?”
“Yes.”
“Why?”
Dad laughed bitterly.
“To prove she’s smarter than us.”
“No.”
“Then why?”
I looked at them.
“Because I believe the company can be worth two billion dollars in five years.”
Marcus slowly nodded.
“The model supports that.”
Dad turned.
“What model?”
I opened the projection.
“A retooled line raises capacity approximately seventy percent. New automated inspection reduces rework. Restoring R&D gets us back into higher-margin designs. The Asteron contract gives the first major demand anchor.”
Mom frowned.
“What Asteron contract?”
No one spoke for a second.
Then I said:
“I’ve been negotiating with Asteron Space Systems for four months.”
Dad stared.
“Why?”
“They need a supplier for their next-generation satellite communications boards.”
“We bid on something with them two years ago.”
“You lost.”
His face hardened.
I continued carefully.
“You lost because you did not have capacity and would not commit to the equipment investment.”
“We weren’t going to spend thirty million dollars hoping they might order.”
“They’re prepared to commit now.”
Mom leaned forward.
“How much?”
“Approximately three hundred forty million over three years, with renewal options.”
The room changed.
Even the older directors who had known about the restructuring did not know the final contract range.
Dad sat down.
Marcus whispered:
“That changes everything.”
“It changes the probability,” I corrected.
Dad looked at me.
“You negotiated this?”
“With Quantum’s industrial team and Asteron’s supply-chain group.”
“They spoke to you about our capabilities?”
“Yes.”
“Without us?”
“They toured the facility under confidentiality through the strategic review process.”
His face went red.
“You brought customers into our plant without telling us?”
“The board authorized strategic diligence.”
Thomas said, “I signed the access.”
Dad looked toward him.
“You’re all in on this.”
“No,” Thomas said.
His voice was tired.
“We’re all trying to prevent bankruptcy.”
That landed differently.
Dad looked around the table.
Perhaps for the first time, he noticed no one was treating me as the intruding daughter.
They were treating him as an executive who needed to listen.
Mom’s voice became quieter.
“If you have the money, the investors, the customer… why didn’t you come to us?”
“I did.”
“No. Why didn’t you tell us all of this?”
I held her gaze.
“Because every time I tried to talk about business, you told me to let the adults talk.”
Her face fell.
“Emma.”
“At Christmas two years ago, Dad told Uncle David I worked with spreadsheets.”
“He was joking.”
“At Thanksgiving, you told me not to interrupt a supply-chain conversation because manufacturing was different from finance.”
“It is different.”
“Yes.”
“But?”
“But I had spent the previous month restructuring a semiconductor company’s vendor financing.”
Mom looked away.
I continued.
“Three months ago, I called Dad specifically because I wanted to discuss Chen’s financial condition.”
Dad’s voice cracked slightly.
“You didn’t tell me you were buying the company.”
“You didn’t let me get through the first ten minutes.”
“That’s different.”
“How?”
He opened his mouth.
No answer came.
For most of my life, my parents had not been malicious.
That was what made the resentment difficult to explain.
They loved me.
They paid for school.
They showed up to graduations.
Mom mailed care packages during finals.
Dad once drove forty-five minutes in a snowstorm because my car would not start.
They were good parents in dozens of practical ways.
They simply had one large blind spot.
They could not imagine that their daughter might someday understand the thing they understood best better than they did.
Not engineering.
Their company.
Thomas called a recess.
“Fifteen minutes.”
No one objected.
The directors left slowly.
Marcus took his laptop.
Daniel Rothstein disappeared without looking at my father.
My parents remained seated.
I stood.
Thomas caught my eye.
“Walk with me.”
We stepped into the hallway.
The executive floor overlooked the manufacturing facility through tall interior windows.
Below us, employees in blue smocks moved between work cells.
Circuit panels traveled down an inspection line.
A forklift carried sealed component bins toward receiving.
Two hundred forty employees.
People whose names my parents knew.
People who had mortgages.
Kids.
College tuition.
Medical bills.
Retirement accounts.
That was the part of corporate finance most people never see when they talk about control.
Shares are numbers until the factory closes.
Thomas stopped beside the glass.
“That was brutal.”
“It wasn’t supposed to be.”
“You could have told them before today.”
“I tried.”
“All of it?”
“No.”
He looked at me.
“Why?”
“Because I wanted them to listen before they knew I had enough shares to force the issue.”
Thomas sighed.
“That did not happen.”
“No.”
He watched the factory.
“You know they may never forgive this.”
I leaned against the railing.
“What exactly am I losing?”
“Your parents.”
“That’s not what I meant.”
“I know.”
I closed my eyes.
“This relationship where they dismiss everything I say? Where my career is a cute side interest until they need my capital?”
“That’s unfair to them.”
“Probably.”
Thomas turned toward me.
“Then be careful.”
“With what?”
“Winning too completely.”
The sentence stayed with me.
He continued.
“You have the votes. You have the money. You probably have the right strategy. That doesn’t mean every sharp sentence needs to be spoken.”
I looked through the glass at my father, still seated inside the boardroom.
His elbows were on the table.
His head was down.
I had never seen him look that old.
Thomas said, “They built this from nothing.”
“I know.”
“You know intellectually.”
“I grew up with it.”
“No.”
Thomas shook his head.
“You grew up next to it. That’s different from carrying payroll when there’s seven thousand dollars in the bank and thirty employees expecting checks. Different from mortgaging your house for equipment. Different from having a customer reject six months of work.”
I looked at him.
“I’m not trying to erase what they built.”
“Good.”
“I’m trying to preserve it.”
“Then make sure preservation doesn’t feel like punishment.”
He walked away.
I remained at the window.
Below, a woman named Sonia Alvarez was inspecting boards beneath a magnifier.
I recognized her because she had worked at Chen since I was eleven.
She used to bring homemade cookies to the Christmas party.
Somewhere on the floor was Daniel Cho, a quality engineer whose daughter had just started college.
Marcus had shown me pension obligations.
Payroll.
Health plans.
Severance exposure.
If Chen Technologies filed Chapter 11 and ultimately liquidated, the story would not be about my parents’ pride.
It would be about hundreds of people carrying cardboard boxes to their cars.
That was why I had done this.
At least, that was what I kept telling myself.
But I would be lying if I said ego played no role.
Part of me wanted my father to know.
Part of me wanted my mother to see the title.
The returns.
The money.
The contract.
I wanted them to remember every little dismissal and feel embarrassed.
That part of me existed.
I did not like her very much.
But pretending she did not exist would have made me less trustworthy, not more.
I returned to the boardroom twenty-five minutes later.
My parents entered last.
This time they sat together.
United.
Their shoulders nearly touched.
Dad stood before Thomas formally reopened the meeting.
“I want to say something.”
Thomas nodded.
Dad looked at the board.
Then at me.
“What Emma has done may be legal.”
His voice had regained the polished strength he used at customer conferences.
“But legality and ethics are not identical.”
I said nothing.
“She acquired shares while possessing unusual knowledge of our vulnerabilities.”
Marcus immediately spoke.
“All material transactions were reviewed under applicable information-control policies.”
Dad held up a hand.
“I’m not making a technical securities allegation.”
“Good,” Marcus said.
Dad’s jaw tightened.
“I’m talking about family.”
I looked down at my notes.
“You sat at our dinner table while secretly buying the company your mother and I built.”
“Yes.”
“You listened while we discussed problems.”
“You also told me not to comment on them.”
His face tightened.
“I’m speaking.”
I nodded.
He continued.
“You positioned yourself to take control at the moment we were weakest.”
“No.”
He looked at me.
“I positioned myself because the company was weakest.”
“That is the same thing.”
“It isn’t.”
“To us, it is.”
That sentence quieted me.
Dad looked around the boardroom.
“Twenty-five years. Patricia and I built this company for twenty-five years.”
Mom sat rigid beside him.
“We signed personal guarantees when no bank wanted us. We worked weekends. We missed vacations. We put every dollar back into the business for years.”
His voice wavered once.
Then strengthened.
“And now our daughter comes in with a private fund and tells us we are no longer qualified to run it.”
I met his eyes.
“You’re qualified to build technology.”
“Don’t patronize me.”
“I’m not.”
“That is exactly what you’re doing.”
I almost answered sharply.
Thomas’s sentence returned.
Winning too completely.
I took a breath.
“You are one of the best engineers I know.”
Dad laughed bitterly.
“Generous.”
“You are.”
I looked at Mom.
“And you built the supply chain that made this company scalable.”
Her face moved slightly.
“I learned half of what I know about operational risk from listening to both of you.”
Dad frowned.
“Then why are we here?”
“Because the company changed.”
Silence.
“The job changed.”
I continued.
“When there were forty employees, you could know everything. At eighty, maybe. At two hundred forty, across multiple aerospace programs, global suppliers, regulatory requirements, debt markets, customer concentration, labor planning, and capital strategy, the company needed management systems you never built.”
Mom whispered, “We built systems.”
“You built systems around yourselves.”
That hurt.
I saw it.
I softened my voice.
“The company cannot depend on two people forever.”
Dad sat slowly.
Mom looked at me.
“Is that what you think we did wrong?”
“No.”
“What then?”
“You became indispensable.”
She frowned.
“That sounds like a compliment.”
“It’s dangerous.”
Marcus nodded.
I continued.
“Every major decision still climbs to you. Engineering exceptions. Vendor approvals. Capital spending. Senior hires. You built a company where nothing important moves unless Richard or Patricia Chen touches it.”
Dad said, “Accountability.”
“No. Bottleneck.”
The word landed hard.
Mom stared at me.
I showed the board a slide.
“Average capital approval time: forty-six days. Your competitors average twelve.”
Next slide.
“Senior hiring cycle: ninety-one days.”
Another.
“New-product engineering requests waiting for founder sign-off: twenty-three.”
Dad looked at the screen.
“Those numbers have context.”
“They always do.”
I clicked again.
“Turnover among engineers under thirty-five: thirty-eight percent.”
Mom looked toward Marcus.
He nodded sadly.
I closed the presentation.
“This is not about whether you’re intelligent.”
I looked at both of them.
“It’s about whether you are willing to build a company that can operate without you.”
Nobody spoke.
Thomas eventually said:
“We need to discuss the proposal.”
Mom folded her hands.
“What happens to us?”
There was no anger now.
That was worse.
I answered honestly.
“You remain directors.”
“And operationally?”
“Dad would become chief technical adviser.”
His eyes flashed.
“A ceremonial title.”
“No.”
“What authority?”
“Engineering design, product architecture, customer technical relationships.”
“And budget?”
“Approved through the new executive process.”
He shook his head.
Mom asked, “And me?”
“Senior adviser on procurement transition if you want it. Katherine wants your help redesigning the supplier network.”
“If I want it.”
“Yes.”
For years, my parents had spoken to me as if choice were a privilege granted by age.
Now I was giving them one.
The irony made me uncomfortable.
Dad said, “And salaries?”
“Market.”
He gave a humorless smile.
“So reduced.”
“Yes.”
“By how much?”
“Approximately forty percent.”
Mom looked down.
I said, “Your board compensation remains separate. Your equity remains valuable if the turnaround succeeds.”
Dad asked, “And if we say no?”
There it was.
The question everyone had avoided.
I answered quietly.
“The board can proceed without your approval.”
Mom closed her eyes.
Dad stared at the table.
Thomas said, “We should discuss alternatives.”
Dad immediately looked up.
“Yes.”
Thomas slid another packet forward.
“The only credible external offer is Davidson Industrial.”
My mother took it.
“One hundred twenty million?”
“For selected assets.”
“What happens to the company?”
“Likely liquidation.”
Dad frowned.
“They told us they were interested in acquiring operations.”
“They are interested in thirty employees, certain certifications, customer contracts, and selected equipment.”
“Where does production go?”
“Malaysia.”
Mom went pale.
Thomas continued.
“The rest of the workforce would be terminated over transition.”
Dad looked at him.
“That isn’t what they told me.”
“It’s in the revised diligence plan.”
Marcus said, “I confirmed it yesterday.”
Mom whispered, “Two hundred people.”
“Closer to two hundred ten.”
No one spoke.
For all their faults, my parents cared about the employees.
That was another reason the situation had become so painful.
Their refusal to change had not come from greed.
It came from confidence calcifying into certainty.
Dad looked at me.
“Quantum is the only other option?”
“The only funded one with a credible path preserving operations.”
“You’ve spoken to others?”
“Every strategic buyer I could reasonably identify. Several private equity firms. Two specialty credit funds. Three investment banks.”
Mom blinked.
“You did all of that?”
“Yes.”
“Over how long?”
“Four months intensively. Longer informally.”
Dad looked away.
I continued.
“The market thinks Chen is too leveraged and too slow. Asteron is what changes the model.”
Dad rubbed his chin.
“How solid?”
“Technical diligence completed. Pricing largely agreed. Supply-chain VP has given verbal commitment contingent on restructuring and equipment financing. Their legal team is drafting.”
“So no signed contract.”
“Not yet.”
He looked at the board.
“So we’re taking two hundred million dollars of outside capital based on a verbal promise.”
“No.”
I opened another page.
“We’re taking two hundred million because without it we may miss payroll in eight weeks.”
That ended the argument.
Thomas called the vote.
“All in favor of accepting the Quantum Capital restructuring proposal, authorizing the financing package, initiating the executive transition, and appointing Katherine Walsh chief executive effective upon closing?”
My hand went up.
Thomas raised his.
Marcus, though not voting on every issue historically, held a director seat and raised his.
Daniel Rothstein raised his.
Two independent directors followed.
Six.
My parents voted no.
Two longtime directors joined them.
Four.
One director abstained because of a separate conflict.
Thomas looked down at the tally.
“The motion carries.”
The words were quiet.
There was no applause.
No triumph.
My father stood.
“We’ll challenge it.”
Marcus looked at him.
“On what grounds?”
“We’ll find them.”
“Richard.”
Marcus’s voice softened.
“Every transaction has been reviewed. Every disclosure. Every shareholder transfer. You are free to obtain counsel, but nothing in the ownership structure was hidden from the company.”
“It was hidden from me.”
“Yes.”
Dad looked at me.
“That’s the point.”
I could not answer.
Mom gathered her papers.
“There is one more agenda item,” Thomas said.
She stopped.
“Emma has requested a company-wide meeting tomorrow morning.”
Dad turned.
“No.”
Thomas continued.
“As majority shareholder and sponsor of the restructuring, she wants to address employees directly.”
“Those are our employees.”
I answered gently.
“They are Chen Technologies employees.”
His face hardened.
“They don’t need to hear this from you.”
“They’re already hearing rumors.”
Marcus nodded.
“The floor knows we’re in trouble. Suppliers know. People are terrified.”
Mom looked at me.
“What are you going to tell them?”
“The truth.”
“That you took over?”
“That their jobs are protected under the restructuring. That capital is coming. That Katherine is joining. That the Asteron opportunity could expand production.”
Dad said, “You want to stand in front of our employees and announce that you replaced us.”
“No.”
I looked at him.
“I want them to know there will still be a company next month.”
Mom stared at me.
Then said quietly:
“This is wrong.”
Her voice hurt more than anger.
“What you did.”
“Mom.”
“No.”
She stood.
“You can explain it with numbers. You can tell yourself you saved jobs. Maybe you did.”
Her eyes filled.
“But you took something from us.”
I swallowed.
“I’m trying to stop you from losing all of it.”
“You already took control.”
“That’s not the same as taking the company away.”
“It feels the same.”
I had no argument for feelings.
She picked up her bag.
“You have destroyed this family over money and control.”
“No.”
My own voice shook now.
“I saved the company whether you can see it or not.”
Mom looked at me.
“That may be true.”
Then she left.
Dad followed.
The door closed.
For several seconds, no one moved.
Marcus broke the silence.
“Well.”
Thomas looked at him.
“Don’t.”
“I was going to say that was the most difficult board meeting of my career.”
“That’s fair.”
Marcus rubbed his face.
“Thirty-five years in corporate finance. Three restructurings. Two fraud investigations. One CEO throwing a chair.”
I looked at him.
“A chair?”
“Different decade.”
Despite myself, I smiled.
The smile disappeared quickly.
I began packing my laptop.
Thomas said, “You did the right thing.”
“I’m not sure.”
“The necessary thing.”
“That is different.”
“Yes.”
Marcus leaned back.
“Will they come tomorrow?”
“I don’t know.”
“Do you want them there?”
I stopped.
“Yes.”
“Even after today?”
“They built the place.”
Thomas nodded.
“That answer gives me some hope.”
“For what?”
“That you’re not doing this for the wrong reasons.”
I looked toward the empty chairs at the far end of the table.
“I’m not sure there are ever completely clean reasons.”
Thomas smiled faintly.
“That answer gives me more.”
I left Chen Technologies as the sun was dropping behind the industrial park.
September light reflected off rows of parked cars.
Second shift was arriving.
Employees crossed the lot carrying coffee, lunch bags, safety glasses clipped to shirt pockets.
People nodded at me without knowing who I was.
Most had no reason to recognize Richard Chen’s daughter.
I had stayed away from the plant for years.
At my car, I stopped.
My phone buzzed repeatedly.
Quantum’s legal team.
Katherine Walsh.
Asteron counsel.
Our restructuring adviser.
No message from Mom.
No message from Dad.
I sat behind the wheel without starting the engine.
From the parking lot, Chen Technologies looked remarkably ordinary.
A low industrial building.
White sign.
Blue logo.
Twenty-five years of my parents’ lives hidden behind precast concrete walls.
I thought of every Sunday Dad had gone into the plant “for an hour” and come home after dark.
Every supplier call Mom had taken during vacations.
Every family dinner interrupted by production emergencies.
They had built their lives around that building.
Now their daughter controlled it.
The daughter who, according to Dad, could not understand real business.
I should have felt vindicated.
Instead I felt hollow.
My phone buzzed.
Thomas:
Employee meeting tomorrow. 10:00. Main production hall, not Conference B. We’re expecting nearly everyone from first shift. Tough crowd. Be ready.
I typed:
I’m ready.
Then erased it.
I wrote:
I’ll be prepared.
That was more accurate.
The next morning, I arrived at 7:30.
The employee cafeteria smelled like coffee, bacon sandwiches, and industrial floor cleaner.
Katherine Walsh was already there.
She was fifty-two, tall, practical, with shoulder-length gray-blond hair and the sort of direct eye contact that made people stop decorating their answers.
We had met repeatedly during the prior two months.
She carried a legal pad instead of a tablet and disliked executive jargon almost as much as my father disliked outside management.
“Sleep?” she asked.
“Some.”
“Parents?”
“No.”
“Good conversation?”
“No.”
“Expected?”
“Yes.”
She nodded.
“Then stop looking surprised.”
I almost laughed.
We walked the plant.
Katherine asked questions.
Not performative questions.
Specific ones.
Why were completed boards waiting eighteen hours before final test?
Why did one line use manual optical inspection where another had automation?
Why was receiving storing critical components in two locations?
Why did the quality team report through operations rather than independently?
Employees noticed.
Some knew who she was.
Most knew something was happening.
At 9:55, the main production hall began filling.
Machine noise had been reduced.
Folding chairs were arranged in rows.
Employees stood along walls when seats ran out.
About two hundred people.
Maybe more.
I saw Sonia Alvarez near the front.
Daniel Cho beside her.
People I recognized from employee rosters and photographs.
People who had no idea how often their names had appeared in my models as payroll lines, pension obligations, average tenure, retention risk.
Numbers becoming faces.
That is always sobering.
Thomas stepped to the microphone.
“Good morning.”
Conversation faded.
“You’ve all heard rumors. Some accurate. Some not.”
A few nervous laughs.
“This company is going through a restructuring.”
The room became silent.
“No facility closure is planned.”
Shoulders visibly relaxed.
“No layoffs are being announced today as part of this restructuring.”
More movement.
Thomas continued.
“Chen Technologies has secured a significant new capital commitment designed to stabilize the balance sheet, modernize production, and restore growth.”
Someone in the back shouted:
“From who?”
Thomas looked at me.
I stepped forward.
“From Quantum Capital.”
People turned.
I heard whispers.
Thomas said:
“Emma Chen will explain.”
I took the microphone.
My parents were not there.
For one second, disappointment hit so sharply that I almost lost my place.
Then the side door opened.
Dad entered.
Mom behind him.
They stood against the back wall.
Dad’s arms folded.
Mom beside him.
They had come.
I looked at the employees.
“My name is Emma Chen.”
A few people smiled.
“Most of you know my parents better than you know me.”
That produced scattered laughter.
“I grew up around this company.”
I looked toward Dad.
“I also spent most of my adult life somewhere else.”
Then I turned back.
“I’m now the majority shareholder of Chen Technologies.”
The room changed.
Whispers.
Someone actually said, “What?”
I continued.
“I know that announcement creates questions.”
A man near the aisle raised his hand.
I pointed to him.
“Are Richard and Patricia leaving?”
“No.”
Dad looked toward me.
“They will remain directors. Richard will continue contributing to product architecture and engineering strategy. Patricia has been asked to remain involved in supply-chain transition.”
Mom’s expression shifted slightly.
The employee asked, “Who’s running the company?”
I gestured toward Katherine.
“Katherine Walsh will become chief executive.”
That caused more reaction.
People knew her.
Industry reputations travel.
Katherine stepped beside me.
“Some of you know me from Innovatech.”
A voice called:
“Unfortunately.”
The room laughed.
Katherine smiled.
“Good. Honesty already.”
Even Dad nearly smiled.
She continued.
“I’m not coming here to turn Chen into Innovatech. If I wanted to run Innovatech, I would have stayed there.”
That helped.
“My job is to make sure this company can afford to keep doing what it does best—and get better at the things it currently does badly.”
Sonia raised her hand.
“What happens to pensions?”
Marcus answered from beside the stage.
“Existing accrued obligations remain intact. The restructuring specifically funds pension requirements.”
“What about health insurance?”
“No planned change this calendar year.”
“Overtime?”
Katherine answered.
“We need to assess production. I’m not cutting labor blindly to make a spreadsheet look prettier.”
That got a few approving murmurs.
Then an engineer asked the question everyone really cared about.
“How bad is it?”
I took the microphone.
“Bad enough that without new financing, the company could face a serious liquidity crisis within approximately two months.”
Silence.
I did not soften it.
“The capital commitment is two hundred million dollars.”
Someone whistled.
“It refinances short-term pressure, funds new equipment, restores research budgets, and gives us enough runway to execute a turnaround.”
Another employee shouted:
“What’s the catch?”
“Accountability.”
Some people laughed nervously.
“I mean that.”
I looked around.
“The company cannot spend its way out of every problem. We have to fix delivery performance. We have to improve yields. We have to speed up decisions. We have to retain engineers. We have to win new programs.”
I clicked a remote.
Asteron’s logo appeared on the screen.
This time the room truly erupted.
Most people in aerospace electronics knew the name.
I waited.
“We are in final contract negotiations to become a major supplier for Asteron Space Systems.”
Dad unfolded his arms.
I continued.
“Potential value is approximately three hundred forty million dollars over the initial term.”
Someone shouted:
“Signed?”
I appreciated the question.
“Not yet.”
The room quieted.
“Technical diligence is complete. Commercial terms are substantially agreed. Legal documentation is in process. I will not tell you it is guaranteed until signatures exist.”
That earned more respect than false certainty would have.
“But if it closes, the program requires exactly what this company has spent twenty-five years learning to do.”
I looked toward my parents.
“High-reliability specialized manufacturing.”
Dad’s face changed.
For the first time since the board meeting, the line between his work and mine felt connected instead of competitive.
I continued.
“This restructuring is not about erasing what came before.”
I meant the employees to hear it.
I also meant my parents.
“It exists because what came before is worth preserving.”
The room was quiet.
“I cannot promise every quarter will be easy.”
I looked around at the production floor.
“I can promise we are not here to liquidate the company, ship the equipment overseas, or treat two hundred forty employees like lines in a shutdown model.”
Sonia nodded.
“We are here to invest.”
Afterward, employees surrounded Katherine, Marcus, and me.
Questions.
Benefits.
Schedules.
Equipment.
Certifications.
Rumors.
A machinist shook my hand and said, “I remember you running around here with a juice box.”
I laughed.
“Please don’t tell anyone.”
“Too late.”
Another employee said quietly:
“Thank you for not selling us.”
That one stayed with me.
My parents remained near the back wall.
When the crowd thinned, I walked toward them.
Mom looked exhausted.
Dad’s face revealed nothing.
I stopped.
“Thank you for coming.”
Dad nodded toward the screen.
“Asteron.”
“Yes.”
“You really think their volume fits Line Three?”
“With the new equipment.”
“You’ll need separate inspection capacity.”
“Yes.”
“The current x-ray system bottlenecks everything.”
“I know.”
He looked at me.
For one brief second, business replaced family.
“Who spec’d the replacement?”
“Katherine’s team shortlisted two. I want you to review them.”
Dad blinked.
“You do?”
“Yes.”
He looked almost suspicious.
“I thought I was just a technical adviser.”
“You are.”
“That sounds like technical advice.”
A corner of his mouth moved.
Mom looked between us.
Then said, “What do you want from me?”
I turned toward her.
“Katherine wants to redesign supplier segmentation. You built most of those relationships.”
“Which you told the board were inefficient.”
“Some contracts are inefficient.”
Her eyes narrowed.
“That’s not the same as saying you are.”
She said nothing.
“I want you involved.”
“Why?”
“Because you know things none of us know.”
Mom looked away.
Then back.
“Do I get to disagree?”
“Yes.”
“Will you listen?”
“Yes.”
She gave a tired, almost sad smile.
“That would be new for both of us.”
I deserved that.
The restructuring closed three weeks later.
So did the Asteron contract.
Three hundred thirty-eight million dollars in committed volume over the initial three-year schedule, plus options that could take the relationship significantly higher.
The first payment from Quantum hit Chen Technologies’ accounts on a Thursday.
Marcus sent me a screenshot.
For the first time in months, unrestricted liquidity did not look like a countdown clock.
Katherine began work the following Monday.
She moved quickly.
Not recklessly.
Three executive positions were consolidated.
Two underperforming managers left with severance.
Research spending was restored.
A modernization team evaluated every major production line.
Approval thresholds were delegated downward.
Supplier contracts were rebid.
A weekly operating meeting replaced the endless chains of founder approvals.
My father hated half of it.
At least at first.
The first serious clash came over new automated optical inspection equipment.
Dad argued for a proven European system.
Katherine preferred a newer American vendor with better integration.
They fought for forty-five minutes.
Finally Katherine said:
“Richard, convince me with data.”
He froze.
My father was accustomed to authority.
Not persuasion.
Then something remarkable happened.
He did exactly that.
Two days later, he returned with throughput comparisons, failure rates, service records, and total-cost calculations.
Katherine reviewed them.
Then chose his system.
Dad called me afterward.
“She listened.”
I almost laughed.
“Yes.”
“She changed her decision.”
“Yes.”
“Because I was right.”
“Yes, Dad.”
He paused.
“I like her less now.”
“I assumed.”
But I heard satisfaction in his voice.
Being removed from the CEO role wounded him.
Being taken seriously as an engineer began healing something different.
My mother’s adjustment was slower.
Patricia had controlled purchasing for almost twenty-five years.
She knew vendors by first name.
She knew which sales representative drank decaf and which supplier’s owner had a son at Purdue.
Katherine’s new procurement director wanted formal scorecards.
Mom considered that insulting.
“They’re not numbers.”
“They are partly numbers.”
“Relationships matter.”
“I agree.”
“You people think everything can be ranked.”
I smiled slightly.
“You raised me.”
She did not appreciate that.
For months, every conversation contained old friction.
Then one supplier failed to meet a critical delivery.
Under the old system, Mom would have called personally, argued, negotiated, and probably secured an emergency shipment.
The new scorecard had already flagged the vendor’s declining performance three months earlier.
Katherine’s team had qualified a backup.
Production lost six hours instead of six days.
Mom stared at the report.
Then said:
“I still hate the scorecards.”
The procurement director smiled.
“You can hate them.”
Mom looked at her.
“As long as I use them.”
“Exactly.”
Six months after the restructuring, Chen Technologies posted its first profitable quarter in more than a year.
Not a large profit.
But profit.
The Asteron line was running behind schedule and above budget, which Dad reminded everyone was normal for new aerospace production.
Engineering turnover fell.
Delivery performance improved.
Quantum did not convert additional ownership because the first performance milestones were met.
That mattered to my parents.
Their equity was still minority equity.
But its value stopped shrinking.
At Thanksgiving, we went to my parents’ house.
It was the first holiday after the takeover.
No one used that word.
Takeover.
We all thought it.
Mom put the turkey on the table.
Dad poured wine.
For twenty minutes, we discussed anything except Chen Technologies.
Weather.
My cousin’s new house.
Aunt Ellen’s knee surgery.
The Patriots.
Then Dad asked:
“What do you think of the new defense electronics acquisition in Arizona?”
The table became very quiet.
I looked at him.
“Are you asking me?”
He frowned.
“Who else?”
Mom covered a smile with her wineglass.
I said, “I think they overpaid.”
“Why?”
“Customer concentration.”
Dad nodded slowly.
“That’s what I thought.”
It was a tiny moment.
No apology.
No speech.
But for the first time in my life, my father asked what I thought about business and waited for the answer.
I drove home afterward and cried in the car.
Not because everything was repaired.
Because sometimes the smallest change reveals how much you wanted something.
A year after the restructuring, Chen Technologies’ revenue was up thirty-one percent.
Margins had improved.
The Asteron program had expanded.
Katherine signed two additional aerospace customers.
The company crossed three hundred employees.
Quantum’s original investment increased substantially in value.
My personal stake did too.
On paper, my parents were wealthier as minority shareholders than they had been when they controlled a failing business.
Dad found this deeply annoying.
“You realize the stock is worth more now.”
“I have seen the reports.”
“Just checking.”
“You enjoy this.”
“A little.”
He shook his head.
Then smiled.
Mom never admitted she had been wrong about outside management.
She said:
“Katherine turned out to be better than expected.”
That was Patricia Chen language for high praise.
Two years after the board meeting, the company held its twenty-seventh anniversary dinner in the manufacturing hall.
Not a country club.
Dad insisted.
Long tables ran between temporarily cleared production areas.
Employees brought spouses.
There was catered Chinese food, Italian food, barbecue, and a Costco sheet cake large enough to feed a military unit.
Thomas gave a speech.
Then Katherine.
Then my father.
He stood at the microphone.
For years, he had been excellent at speeches.
Funny.
Confident.
Precise.
That night, he looked almost nervous.
“When Patricia and I started this company, we thought the hard part would be learning how to build something people wanted.”
He paused.
“We were wrong.”
Employees laughed.
“The harder part turned out to be learning when the thing you built no longer belongs only to you.”
The room quieted.
Dad looked toward Mom.
Then toward me.
“I did not learn that gracefully.”
A few people smiled.
“That is the diplomatic version.”
More laughter.
He continued.
“Two years ago, I believed anyone who wanted to change Chen Technologies was threatening our legacy.”
He looked around the production floor.
“I eventually understood that refusing to change was the greater threat.”
My throat tightened.
Dad said, “Katherine Walsh taught us how to run a larger company.”
Katherine raised her glass.
“Marcus Webb kept us honest about money.”
Marcus smiled.
“Thomas Harrison kept the board from killing one another.”
That earned loud laughter.
Then Dad looked at me.
“And my daughter taught me something I should have known before she had to buy fifty-five percent of my company to make me listen.”
The room went silent.
I stared at him.
He smiled.
“I’m sorry, Emma.”
Not private.
Not polished.
Not complicated.
Just those words.
“I spent years telling you that you didn’t understand business while failing to understand your business.”
I could barely breathe.
“You saw this company more clearly than I did when it mattered most.”
He paused.
“I hated you for being right.”
Several employees laughed softly.
“So did your mother.”
Mom called from her seat:
“Richard.”
The room laughed harder.
Dad grinned.
“Temporarily.”
Mom shook her head.
He continued.
“I thought leadership meant having the answer.”
His voice softened.
“Turns out sometimes leadership means recognizing who else does.”
He raised his glass.
“To Emma.”
The room stood.
I hated that.
I loved it.
Both were true.
Afterward, Dad found me near the dessert table.
“You’re crying.”
“No.”
“You are.”
“You gave a speech.”
“I’ve given hundreds.”
“Not like that.”
He nodded.
“No.”
We stood awkwardly.
Then he said:
“I meant it.”
“I know.”
“I was proud of you before.”
That caught me.
“I just didn’t understand what you were doing.”
“That’s not entirely the same thing.”
“No.”
He looked down.
“I know.”
I hugged him.
Not because everything disappeared.
Because enough had changed.
Mom apologized differently.
Months later, she came to my condo carrying two grocery bags and announced that my refrigerator contained “food for a college student.”
“I’m twenty-nine.”
“Your refrigerator does not know that.”
We cooked together.
Halfway through chopping vegetables, she said:
“I used to think you chose finance because you didn’t want what we built.”
I put down the knife.
“I didn’t want to manufacture circuit boards.”
“I know.”
“That’s different.”
“I know that now.”
She rinsed a pepper.
“I took it personally.”
“I know.”
“When you didn’t join the company after college, I thought you were rejecting us.”
I stared.
“You never said that.”
“Parents are terrible at saying the thing they actually mean.”
“Apparently.”
She smiled sadly.
“I called your work little because I needed ours to be bigger.”
The honesty hurt.
But it also healed.
“I’m sorry.”
I nodded.
“I know.”
“No.”
Mom turned toward me.
“I’m sorry I made you feel like the things you were good at counted less because I didn’t understand them.”
That was the apology I had wanted without knowing the words.
I hugged her too.
Chen Technologies reached a billion-dollar valuation in the fourth year after restructuring.
Not two billion.
My model had been optimistic.
I reminded Dad that projections were not promises.
He enjoyed reminding me that I had once predicted two billion in five years.
“Still time,” I said.
He responded:
“Spoken like finance.”
By year five, we passed $1.7 billion after winning two additional satellite and defense programs.
Close enough for family bragging rights.
I did not become CEO.
That surprised people.
The Wall Street Journal ran a short piece describing me as “the daughter who took control without taking the corner office.”
I disliked the headline.
But it was accurate.
I never wanted to run a circuit-board manufacturer.
That had been my parents’ dream.
I wanted to invest.
Katherine ran Chen Technologies far better than I could have.
Dad remained chief technical adviser.
Eventually, we stopped pretending the title needed “chief.”
Everyone simply called him Richard.
He spent his days where he was happiest.
Engineering reviews.
Prototype labs.
Customer technical meetings.
He stopped attending most budget meetings voluntarily.
“I have escaped,” he told me once.
Mom gradually reduced her formal role too.
She mentored the new procurement team.
She still knew every supplier.
She also learned to let the scorecards do part of the arguing.
My relationship with my parents never returned to what it had been.
That was probably good.
The old relationship had required me to remain smaller so they could remain certain.
The new one was less comfortable.
More equal.
We argued.
Sometimes Dad still said, “When you’re older, you’ll understand.”
Then he would catch himself.
Mom sometimes introduced me as “our investor genius” at family events.
I asked her to stop.
She mostly did.
Healing is not a personality transplant.
It is correction repeated often enough to become habit.
Thomas retired from the board at seventy-two.
At his last meeting, he handed me the old wooden gavel.
“I don’t want this.”
“Take it.”
“Why?”
“You caused more trouble in that boardroom than anyone since your father.”
“That is not a compliment.”
“It is from me.”
I kept it in a drawer.
Marcus retired a year later.
At his party, he told the story of the emergency board meeting.
He exaggerated everything.
According to Marcus, Dad nearly flipped the table.
He did not.
According to Marcus, Mom looked ready to have me removed by security.
Possible.
Then Marcus raised a glass.
“I spent thirty-five years watching people confuse ownership with leadership.”
He looked at me.
“Emma was the first person I saw acquire ownership specifically because leadership had failed—and then immediately hand operational power to someone more qualified.”
I felt uncomfortable.
Marcus knew.
“So here’s to knowing the difference between being able to control something and needing to.”
That lesson mattered more to me as I got older.
At twenty-eight, I believed control was the solution.
Sometimes it is.
Control allowed me to force a restructuring my parents would never have accepted willingly.
Without it, the company probably would have failed.
But control is dangerous when success convinces you that being right once makes you right generally.
Katherine saved me from that.
A year after the turnaround, I opposed closing a small product line that I considered unprofitable.
She disagreed.
“The line supports three larger customers.”
“The margins are terrible.”
“You’re looking at direct contribution.”
“That’s usually how margins work.”
She stared at me.
“You sound like Richard.”
I stopped.
“That was unnecessary.”
“It was accurate.”
She showed me the customer-retention analysis.
I was wrong.
We kept the line.
Two of those customers later expanded.
That day, I understood my parents a little more.
Not enough to excuse what had happened.
Enough to respect how seductive certainty becomes after years of being correct.
They had built a company through instincts that worked repeatedly.
Success became evidence that those instincts would always work.
Then the world changed.
They did not.
I was not immune to the same disease.
Nobody is.
Five years after that emergency board meeting, Dad and I drove to the original garage in Woburn.
The house belonged to someone else now.
The current owners had turned the garage into a home gym.
Dad had contacted them through an old neighbor and, to my embarrassment, explained the company history.
They invited us over.
The garage looked tiny.
Dad stood near the back wall.
“My first reflow setup was there.”
He pointed.
“Your mother kept inventory on shelves here.”
The homeowner’s Peloton occupied the approximate location.
I smiled.
“Very industrial.”
Dad laughed.
He looked around.
“I thought this place was enormous.”
“You were younger.”
“I was terrified.”
That surprised me.
“You?”
“Constantly.”
“You never seemed afraid.”
“I had you.”
“What does that mean?”
“You were three. Your mother was pregnant with the first big contract, metaphorically speaking. We had a mortgage. I had quit my job.”
He smiled.
“I didn’t have the luxury of looking scared.”
We stepped outside.
Late-afternoon sun fell across the driveway.
Dad leaned against my car.
“When you took control of Chen, that was the first time I felt what I probably made you feel for years.”
I looked at him.
“Small?”
“Dismissed.”
I said nothing.
“I walked into a room thinking I was the authority and discovered everyone else had been having a conversation without me.”
His voice was quiet.
“It was awful.”
“I know.”
“I wanted to punish you for it.”
“I know that too.”
He looked toward the garage.
“But you had tried.”
“Yes.”
“I just couldn’t hear you.”
We stood there for a while.
Then Dad said:
“I’m glad you didn’t wait until I was ready.”
That was perhaps the greatest compliment he ever gave me.
Because he had finally understood something I had learned painfully.
Sometimes the people you love do not change because you explain yourself better.
Sometimes the structure has to change first.
People imagine family businesses fail because relatives fight.
Sometimes they fail because relatives avoid fighting until reality makes the decision for them.
We had spent years choosing politeness over clarity.
Dad dismissed my expertise.
I hid my success.
Mom interpreted silence as agreement.
I bought shares rather than forcing a confrontation earlier.
Everyone contributed something to the eventual explosion.
The difference was that, by the time we reached the boardroom, we were running out of time.
Eight weeks of cash.
Two hundred forty jobs.
A company with real technology and no room left for pride.
Would I do everything exactly the same again?
No.
I would tell my parents sooner that I had become a partner.
Not because they were entitled to my résumé.
Because hiding became its own kind of power.
I liked knowing something they did not.
That was not as innocent as I once pretended.
I would have forced the conversation earlier.
Not by asking permission to offer advice.
By saying:
I am an investor. I have reviewed the numbers. You are in trouble. We need to talk as adults.
Maybe Dad still would have laughed.
Probably.
But I would know I had spoken plainly.
I would still buy the shares.
That part I do not regret.
Ownership gave me the leverage necessary to protect employees and preserve the company.
I would still hire Katherine.
Still approve the restructuring.
Still secure the Asteron contract.
Still vote yes.
Some decisions hurt people and remain correct.
Adulthood includes learning to live with that.
What changed most was my reason for wanting my parents to respect me.
At twenty-eight, part of me wanted them to admit I understood business.
At thirty-three, I no longer needed that.
They did respect me.
But by then, the respect felt less important than being known.
Dad began calling me when he had an investment question.
Mom called when she wanted to understand a news story about interest rates.
I called Dad about aerospace technology I did not understand.
I called Mom when Quantum evaluated a company with a complicated supplier problem.
We became useful to one another.
That was better than ranking.
At one Thanksgiving dinner, years after the boardroom confrontation, my younger cousin asked how I had taken over Chen Technologies.
Dad answered before I could.
“She bought it.”
Mom rolled her eyes.
“That makes it sound like she walked into Costco.”
Dad shrugged.
“She kept buying shares until she owned us.”
“I did not own you.”
Dad smiled.
“That distinction took me three years to learn.”
Everyone laughed.
Then my cousin asked:
“Were you mad?”
Dad looked at me.
“Furious.”
“For how long?”
“Long enough to be embarrassing.”
Mom said, “Your father considered suing everyone.”
“I spoke to attorneys.”
“You spoke to six attorneys.”
“Responsible due diligence.”
I laughed.
My cousin asked:
“When did you realize Emma was right?”
Dad became thoughtful.
“The employee meeting.”
I had never known that.
“Really?”
He nodded.
“You stood in front of the factory and told them the truth.”
“What part?”
“That things were bad.”
He looked down at his plate.
“I had spent six months telling everyone we were fine.”
Mom became quiet.
Dad continued.
“You were willing to say we weren’t.”
That was when I understood something about leadership I had not modeled in a spreadsheet.
People often believe confidence requires certainty.
My father had believed employees needed him to say everything was under control.
I had believed credibility required showing them the danger clearly.
Both instincts came from wanting to protect people.
Only one gave them enough truth to prepare.
Chen Technologies eventually celebrated its thirtieth anniversary.
More than four hundred employees attended the company picnic.
There were food trucks in the parking lot.
Kids ran through inflatable obstacle courses.
Dad stood near the engineering tent explaining an old circuit board to a group of interns who probably considered the technology prehistoric.
Mom was arguing with a caterer because they had run out of vegetarian sandwiches.
Some things never change.
Katherine found me near the stage.
“Look at them.”
“I am.”
“You know they’re happy.”
“My parents?”
“Yes.”
I watched Dad laugh.
“I know.”
“Do you know what they say when you’re not around?”
“That I overuse financial models?”
“That too.”
She smiled.
“They say their daughter saved the company.”
I looked away.
“I hate that phrase.”
“Why?”
“Too clean.”
Katherine waited.
“They saved it first.”
“What?”
“They built something worth saving.”
Katherine nodded.
“Fair.”
“And you fixed operations.”
“Yes.”
“Marcus kept the financing together.”
“Yes.”
“Employees stayed when they could have left.”
“Yes.”
“Asteron took a chance.”
“Yes.”
I looked at the factory.
“No one saves a company alone.”
Katherine smiled.
“You finally sound like an adult.”
I stared at her.
“You’re fired.”
“You can’t fire me without a board vote.”
“Unfortunately, I know.”
That evening, after everyone left, I walked through the production floor alone.
Second shift had not started yet.
Machines were quiet.
Work lights glowed above empty stations.
New equipment stood where the aging lines had once slowed everything down.
Asteron assemblies moved through a secured section behind glass.
On one wall hung photographs from the company’s history.
The garage.
The first employees.
The first major aerospace shipment.
Groundbreaking on the current plant.
My parents younger.
Me as a child sitting on Dad’s shoulders at a company picnic.
Then a more recent photograph.
Katherine, Mom, Dad, and me at the opening of the expanded satellite production line.
I stood there for a long time.
When I was younger, I thought success would feel like finally entering the room where the adults were talking.
Then I entered it.
It was just a room.
People were uncertain.
Egos got involved.
Numbers changed.
Smart people made mistakes.
Experience helped, but it did not create immunity from fear.
My parents had never been the all-knowing adults I imagined.
Neither was I.
That realization did not diminish them.
It made forgiveness easier.
I went upstairs to the boardroom.
The same mahogany table remained.
We had discussed replacing it during renovations.
Dad objected.
“Perfectly good table.”
For once, nobody fought him.
I sat in the chair at the far end.
The chair where I had been sitting when my father laughed.
I could still hear it if I tried.
Sweetheart, this is serious business.
I smiled.
Not because I had defeated him.
That interpretation had become too small for what happened.
My father had been wrong about me.
I had also been wrong about what proving him wrong would feel like.
Victory was not the board vote.
It was not the fifty-five percent.
Not the $200 million financing.
Not even the contract that gave Chen Technologies a future.
Victory was five years later, when my father could call and say:
“Emma, I don’t understand this. Explain it to me.”
And I could explain without needing him to remember that once he thought I could not read a balance sheet.
It was Mom sending me a supplier report and asking:
“What am I missing?”
It was me calling Dad because Quantum was looking at a company with a manufacturing problem and saying:
“I need your engineering opinion.”
It was no longer important who had been the adult in the room.
We had finally become adults in the same room.
That was harder than acquiring a company.
It was also worth more.
I still own a large position in Chen Technologies.
Less than fifty-five percent now.
Over time, some of my stake was redistributed through employee ownership, new investors, and strategic compensation.
People occasionally ask how I could willingly dilute control after fighting so hard to obtain it.
The answer is simple.
Control was a tool.
Not the destination.
I needed enough of it once to force a company to change.
Keeping it forever just because I had fought for it would have meant learning the wrong lesson from my parents.
A healthy company should not depend on one person.
Not Richard Chen.
Not Patricia Chen.
Not Katherine Walsh.
Not me.
That was the flaw I had seen from the beginning.
Eventually I had to prove I believed my own diagnosis.
So we broadened ownership.
Built stronger governance.
Created succession plans.
Expanded employee equity.
Made sure no future twenty-eight-year-old would need to spend fourteen months quietly buying half the company just to get the board to confront reality.
Dad hated the employee-equity dilution proposal at first.
Then one afternoon he called.
“I’ve been thinking.”
“Dangerous.”
“Very funny.”
“What?”
“The employee shares.”
“Yes?”
“I think we should increase the allocation.”
I sat up.
“Why?”
“People build things.”
He paused.
“They should own some of what they build.”
I smiled.
“That sounds suspiciously modern.”
“Don’t push it.”
We increased the pool.
When the plan was announced, Sonia Alvarez—now a production supervisor—came to my office.
She had worked at Chen since I was eleven.
“Your dad told me this was his idea.”
I laughed.
“Let him have it.”
She smiled.
“You two are more alike than either of you wants to admit.”
That was probably true.
My father and I both liked being right.
We both mistook preparation for certainty.
We both protected people by trying to control situations.
The difference was that I got to learn from watching him.
Then he got to learn from watching me.
Families rarely teach in one direction.
The old story of Chen Technologies used to be simple.
Richard and Patricia Chen built a company from their garage.
Then the market changed.
They failed to adapt.
Their daughter quietly acquired control and saved the business.
That is the version financial journalists preferred.
It fit neatly into a headline.
It was also incomplete.
The fuller story was messier.
My parents built the knowledge that made me capable of seeing what was wrong, even while failing to recognize that capability in me.
I learned finance because I wanted a path different from theirs, then used finance to preserve what they had built.
I took control because they would not listen.
Then I learned that leadership meant giving much of that control away again.
They lost authority and found better roles.
I got the respect I thought I wanted and discovered respect mattered less than relationship.
The company survived because all of us eventually accepted something we had resisted.
My parents accepted that creating something did not entitle them to control it forever.
I accepted that being right did not entitle me to humiliate them.
That may have been the real restructuring.
Not the notes.
Not the board.
Not the ownership percentages.
Us.
Years later, when Dad finally retired from formal technical work, the company held a small dinner.
He refused the large ballroom.
“Waste of money.”
We reserved a private room at an Italian restaurant near Burlington instead.
Thirty people.
Family.
Board members.
Longtime employees.
Katherine.
Marcus came out of retirement long enough to complain about the wine.
Thomas brought the old gavel because he apparently believed it should attend major life events.
After dinner, Dad stood.
“No long speeches.”
Everyone laughed because nobody believed him.
He looked around.
“I spent most of my life believing Chen Technologies was the thing Patricia and I would leave behind.”
Mom looked at him.
“I was wrong.”
He pointed toward several longtime employees.
“It belongs partly to every person who solved a problem here when I wasn’t looking.”
Then toward Katherine.
“To people who made it better when I thought changing it would ruin it.”
Finally toward me.
“And to a daughter who loved it enough to risk making us hate her.”
The room became quiet.
Dad smiled.
“For a while, we did.”
“Richard,” Mom said.
“What? We did.”
Everyone laughed.
He looked at me.
“I’m glad you didn’t need our permission.”
My eyes filled.
This time I did not pretend otherwise.
Dad raised his glass.
“To people who tell you the truth before you’re ready.”
We drank.
After dinner, I drove my parents home.
They had downsized from the large Lexington house to a condo closer to Boston.
Dad complained about the HOA.
Mom liked not having a yard.
At the entrance, Dad paused before getting out.
“You know, I still think computational finance is a ridiculous degree name.”
I stared at him.
“Good night, Dad.”
“But apparently useful.”
“Get out of my car.”
Mom laughed all the way to the door.
I drove home smiling.
Twenty years earlier, I would have stored that comment like evidence.
One more dismissal.
Now it was just a joke.
Context changes when people do.
The night I took control of Chen Technologies, I believed the biggest question was whether my parents would ever forgive me.
Years later, I understood the more important question had been whether any of us could change enough to deserve a different relationship.
We did.
Not perfectly.
Not quickly.
But enough.
The company survived.
The jobs survived.
My parents’ work survived.
So did our family.
And whenever I walk into that old boardroom now, I sometimes remember my father’s condescending laugh echoing off the mahogany walls.
I remember him looking around the table and saying his daughter did not own a single share.
I remember Thomas Harrison answering quietly:
“She owns forty-seven percent.”
Then I remember what came next.
Not the shock.
Not the vote.
Not the takeover.
The years after.
The slow work of building something better from a moment that could easily have destroyed all of us.
My parents spent my whole childhood telling me they understood business because they had built one.
They were right.
They understood how to build a company from nothing.
What none of us understood yet was that building something and owning its future are not the same skill.
Sometimes protecting what you built means letting someone else change it.
Sometimes respecting your parents means refusing to let their pride destroy their life’s work.
And sometimes becoming an adult means walking into a room where your parents still see a child, sitting down without asking permission, and calmly proving that the future has already changed.
Not so you can take their place.
So there will still be something worth passing on when all of you finally learn to let go.