FAMILY SHAREHOLDERS ONLY,” SISTER ANNOUNCED, CLOSING THE DOOR. “NOT FAILED ENTREPRENEURS,” MOM SMIRKED. I MADE ONE CALL. THE INVESTMENT BANK’S EMAIL BLAST HIT EVERYONE’S PHONES: “EMERGENCY MEETING – $180M FUNDING WITHDRAWAL IN PROGRESS…
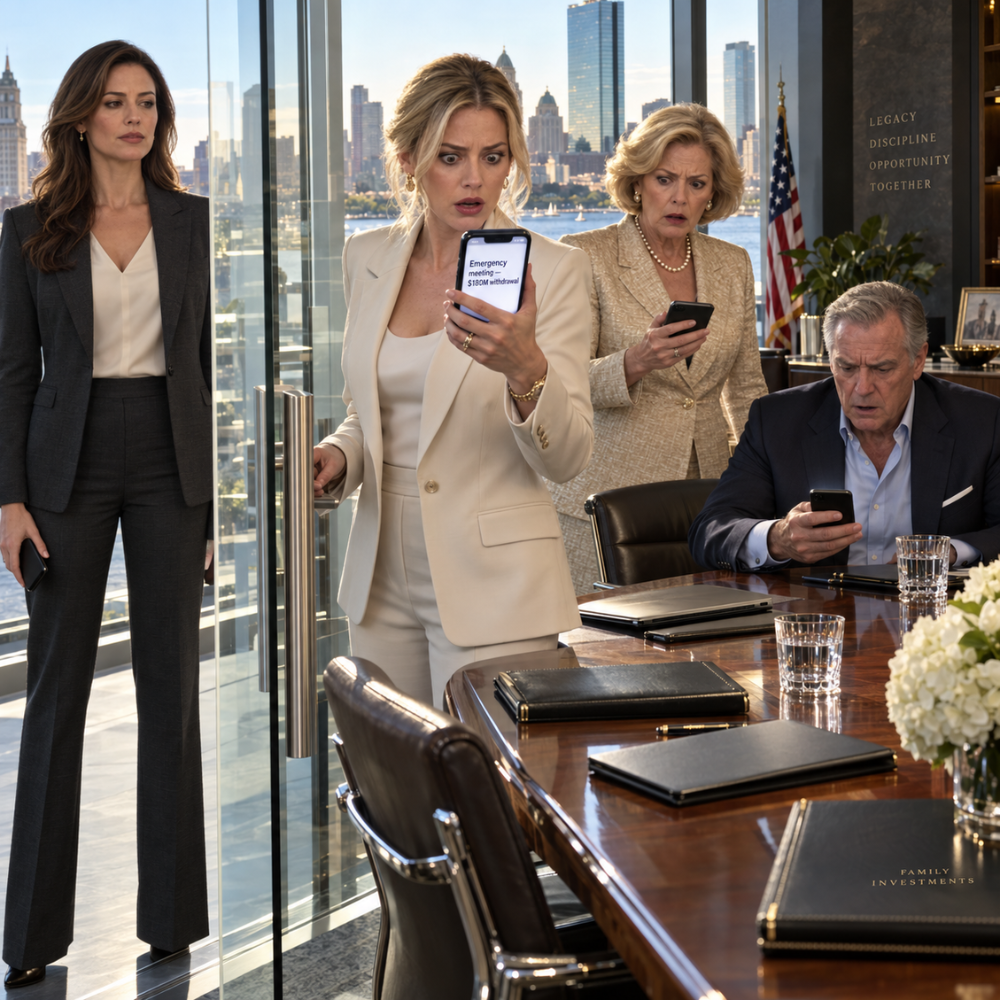
My sister shut me out of our family’s shareholder meeting because I was a “failed entrepreneur.” A week later, she saved two seats for the investors keeping the company alive—and I sat in one.
“The family session is starting in twenty minutes, Jordan.”
Vanessa stood in the doorway of Hartwell Industries’ executive conference room with one hand resting lightly against the glass.
She was smiling.
That was how my sister delivered almost everything difficult.
Politely.
As children, she could exclude you from a birthday game while making it sound as though she was protecting you from getting tired. As an adult, she had simply replaced playground diplomacy with corporate language.
Behind her, twelve leather portfolios had been arranged around the long walnut table.
My father stood at the head, reading through a printed agenda.
My mother was adjusting a white floral arrangement that had no obvious business purpose other than making the conference room look like something from a glossy annual report.
My uncle Richard was talking to one of our outside directors.
Vanessa’s husband, Marcus, had already opened his laptop.
Everyone looked as if important decisions were about to be made.
Which, unfortunately, was true.
“I know when it starts,” I said. “I received the agenda.”
Vanessa’s smile held.
“This part is for active family owners.”
“I am a family owner.”
Technically, my original ten-percent inheritance from our grandfather had been diluted over the years by later issuances. I now held slightly under six percent of Hartwell’s voting common stock directly.
Vanessa knew that.
So did Dad.
That was not what she meant.
She lowered her voice.
“You know what I’m saying.”
“Actually, I’d like you to say it.”
Something moved behind her eyes.
Then Mom appeared.
She wore a pale blue suit and low pearls, the same uniform she had worn to school fundraisers, hospital board luncheons, funerals, and every important Hartwell event since I was a teenager.
“What is going on?”
“Nothing,” Vanessa said.
Mom looked at me.
“Jordan, this is a working session.”
“I understand.”
“For people involved with the company.”
“I also understand that.”
Her expression softened in the way it always did before she said something she considered reasonable and I experienced as a small cut.
“You haven’t worked here in years.”
“I interned here for one summer when I was twenty-one.”
“Exactly.”
“That’s not what I meant.”
She sighed.
“Your father is trying to keep the discussion focused. We’re considering an acquisition. There are financing matters, management issues, long-term strategy. This is not a sentimental family gathering.”
I looked through the glass at the room my grandfather had insisted be built when Hartwell Industries moved its headquarters outside Boston.
His photograph still hung near the far wall.
Elias Hartwell, 1987.
Gray work shirt.
No jacket.
Standing beside the first CNC machine the company had ever purchased.
My grandfather had spent most of his career telling people that a conference table did not make a company serious.
Products did.
Customers did.
Payroll did.
Cash did.
He would have hated the flowers.
Vanessa glanced toward the room.
“We should go in.”
Mom remained with me.
“Jordan, I’m not trying to hurt your feelings.”
That phrase had preceded enough hurt in my life to have become almost ceremonial.
“I know.”
“You’ve done well in your own way.”
“My own way.”
“You understand what I mean.”
“I usually do.”
She continued as if I had agreed.
“TechBridge didn’t become what you hoped. That happens. Most businesses don’t survive.”
TechBridge Consulting had been profitable.
I had closed it deliberately three years earlier after selling its client contracts and moving full-time into investment management.
But I had never given my parents the details.
At Thanksgiving, I had simply said I was winding the firm down.
Dad looked disappointed.
Vanessa called it “a brave decision.”
Mom told relatives I had “tried entrepreneurship.”
By Christmas, TechBridge had become the family’s shorthand for failure.
No one asked what happened to the clients.
No one asked what I did next.
No one asked why I suddenly traveled to New York twice a week or why I sometimes disappeared for three days into manufacturing towns in Ohio, Pennsylvania, and Tennessee.
They decided I was doing “investment consulting.”
That was close enough to reality that correcting them never seemed worth the effort.
Mom touched my forearm.
“Not everyone needs to be at the center of the business.”
There it was.
I looked at her.
“Go to your meeting.”
Relief flickered across her face.
“We’ll have lunch afterward.”
“Maybe.”
Vanessa opened the conference-room door wider.
Mom stepped through.
Before the door closed, my sister looked back at me.
“Coffee later?”
“Sure.”
We both knew it would not happen.
The glass door clicked shut.
I stood outside for another few seconds.
Nobody inside turned toward me.
Dad checked his watch.
Mom took her seat.
Vanessa opened her presentation.
Then I walked away.
The elevator carried me four floors down to the parking garage.
I sat in my car with the engine off.
It was late October, cold enough that the concrete garage held a damp metallic chill. Somewhere two rows away, someone locked a car and the horn chirped.
My phone showed three unread emails.
The first two were routine.
The third had arrived from Hart Capital Partners at 8:02 that morning.
I opened it.
HARTWELL INDUSTRIES — Q3 PORTFOLIO REVIEW.
The summary was sixteen pages long.
I scrolled to the investment history.
Hart Capital had first provided forty-five million dollars to Hartwell Industries in March 2020 through a structured preferred-equity and secured-debt package.
That had not been a growth investment.
It had been rescue capital.
Hartwell had been less than six weeks from violating its senior lending covenants.
Its largest automotive customer had postponed orders.
Two production lines were obsolete.
A disastrous inventory-management system had tied up working capital the company did not have.
Dad never told the family any of that.
At Sunday dinners he called it a “temporary liquidity issue.”
Hart Capital supplied another twenty-two million that summer for equipment financing.
Then eighteen million during the supply-chain restructuring.
Thirty million the following year for research, tooling, and customer diversification.
Another twenty-five million when the company modernized the Lowell facility.
Twelve million in emergency operating capital after a major customer delayed payment.
Then additional capital for expansion, refinancing, and the purchase of specialized production equipment.
Total committed across several vehicles and instruments:
Just over one hundred eighty million dollars.
The legal shareholder listed on Hartwell’s cap table was Hart Capital Industrial Opportunities III, LP, together with two affiliated entities.
Collectively, those vehicles controlled forty-seven percent of Hartwell’s voting equity after conversion and preferred rights.
The Hartwell family knew Hart Capital.
They dealt regularly with our law firm, our administrator, our finance team, and our outside representatives.
What they did not know was who controlled Hart Capital.
That information had never been secret from regulators, banks, auditors, or the professionals required to know it.
Hartwell’s outside counsel had completed the appropriate beneficial-ownership and conflict documentation at each closing.
But my family had never examined the ownership chain beyond the investment entities signing the documents.
They assumed Hart Capital was another private fund backed by insurance companies, pension money, family offices, and wealthy investors.
In part, they were right.
Hart Capital did manage outside money.
What they did not know was that I had founded it.
I was its managing partner.
I chaired its investment committee.
And Hartwell Industries existed in its present form largely because, three years earlier, I had decided not to let my grandfather’s company die.
My phone rang.
Elena Vasquez.
General counsel for Hart Capital.
She was also my closest professional confidante.
I answered.
“You were right,” she said.
“About what?”
“They excluded you.”
I stared through the windshield.
“How do you know?”
“Your face.”
“You cannot see my face.”
“I’ve known you seven years. I can hear it.”
I leaned back.
“Vanessa said it was for active family owners.”
Elena was quiet for two seconds.
Then she laughed.
Not loudly.
Just enough.
“I’m sorry.”
“No, you’re not.”
“I’m sorry it hurt. The irony is objectively funny.”
“I know.”
“Are you going to join the investor feed?”
“Yes.”
Hart Capital had contractual observer rights for certain board and strategic sessions. Our observer that morning was scheduled to attend remotely.
Usually one of my partners handled it.
That day, I had asked to use the secure feed myself.
Not because I planned revenge.
At least that was what I had told myself at breakfast.
I wanted to know what they said when they believed I was outside the room.
Elena understood immediately.
“Call me after.”
“I will.”
“And Jordan?”
“Yes?”
“Do not make decisions from the parking garage.”
Despite myself, I smiled.
“That specific warning sounds personal.”
“I have watched people sign terrible documents while angry in parking garages.”
“I’m not signing anything.”
“Good.”
I ended the call.
Then I opened my laptop.
No hacking.
No old credentials.
No secret camera.
Just the secure link our investment agreement entitled Hart Capital to use.
The feed connected.
The conference room appeared.
I muted my microphone and turned off my camera.
Dad was already speaking.
“As all of you know, the last several years have challenged every manufacturer in our category.”
That was true.
Semiconductors.
Freight.
Labor shortages.
Energy costs.
Customers changing forecasts every quarter.
Hartwell had faced all of it.
What came next was less accurate.
“But our discipline and strong family leadership have carried us through.”
I sat alone in my car and closed my eyes.
Strong family leadership.
Hartwell had survived because lenders extended terms, customers tolerated delays, employees worked overtime, and Hart Capital repeatedly injected money while demanding less control than almost any investor committing that much capital would normally accept.
I had chosen that structure deliberately.
My grandfather hated outside interference.
Dad did too.
When Hartwell first needed rescue capital, I told my investment committee I wanted the company saved without my family knowing I was behind the fund.
One partner called the idea psychologically unhealthy.
He was probably right.
But the investment itself made sense at the right price.
Hartwell owned valuable customer relationships.
Its workforce was skilled.
Its machining capabilities were difficult to replicate quickly.
The problems were governance, aging equipment, poor capital allocation, and a family leadership structure that confused loyalty with qualification.
The company was fixable.
We fixed enough of it to keep going.
Then Vanessa stood.
A slide appeared behind her.
HARTWELL 2027: GROWTH THROUGH SCALE.
My sister was good at presentations.
I had always given her that.
At eight, she sold more school wrapping paper than any child in our district.
At twelve, she convinced our parents to let her attend an overnight party by presenting a handwritten “safety plan.”
At twenty-six, she persuaded Dad to create the role of Director of Strategic Growth despite the fact that nobody at Hartwell could explain precisely what strategic growth meant.
She made ambiguity sound intentional.
“Over the past three years,” she began, “we have transformed Hartwell from a defensive manufacturer into a platform positioned for expansion.”
The slide listed plant upgrades.
New automation.
Research spending.
Aerospace certifications.
Customer diversification.
Every line had a number beside it.
I recognized most of those numbers because my team had approved the capital behind them.
“The logical next step,” Vanessa said, “is acquisition.”
A company logo appeared.
Bennett Manufacturing.
I leaned closer to the screen.
I knew Bennett.
Not deeply, but enough.
Privately held.
Precision aerospace and industrial components.
Two facilities.
Roughly eighty million dollars in annual revenue.
A good customer list.
A complicated history involving older industrial sites.
Vanessa continued.
“Bennett gives us immediate access to aerospace programs where Hartwell currently lacks scale.”
Dad nodded.
Mom looked pleased.
Uncle Richard folded his arms.
“What are they asking?”
“Eighty-five.”
Richard whistled.
“Million?”
Vanessa smiled.
“No, Uncle Richard. Dollars.”
Several people laughed.
Richard did too.
Then he said, “I’m serious. Eighty-five is a lot for us.”
“We believe seventy-two to seventy-five gets it done.”
Marcus finally spoke.
He worked for a midmarket private-equity firm and therefore understood capital structure better than most people around that table.
“What does financing look like?”
Dad answered.
“We would expect our investment partner to support the majority.”
I sat completely still.
Marcus frowned.
“Have they agreed?”
“We have a history.”
“That isn’t what I asked.”
Dad’s expression tightened slightly.
“We’ve received support every time the company had a compelling capital need.”
My respect for Marcus increased one degree when he did not let that pass.
“Rescue financing and acquisition financing are different.”
Vanessa stepped in.
“The transaction would be subject to financing. We are not suggesting signing an unconditional purchase agreement.”
Good.
At least someone had spoken to a lawyer.
One of the outside directors asked, “How much family capital?”
“Potentially five to seven million,” Dad said. “Depending on structure.”
“And Hart Capital?”
“Sixty to seventy.”
I stared at the screen.
No one at Hart Capital had seen a formal Bennett financing proposal.
No one had received a diligence package.
No investment memorandum existed.
No committee meeting had been scheduled.
Yet my family was designing an acquisition that assumed my firm would provide almost all of the money.
I picked up my phone and sent a message to David Chin, our CFO.
ANY BENNETT REQUEST FROM HARTWELL?
His response came ninety seconds later.
NONE. ELENA ASKED SAME THING THIS MORNING. ONLY GENERAL DISCUSSION OF “POTENTIAL M&A” IN LAST MONTH’S REPORT.
I typed:
PULL ALL FUNDING COVENANTS AND APPROVAL RIGHTS. NO ACTION YET.
He sent a thumbs-up.
On the screen, Vanessa changed slides.
The title made me sit forward.
FAMILY OWNERSHIP ALIGNMENT.
Dad looked toward her.
She continued carefully.
“If we’re going to take Hartwell into its next phase, our family ownership should reflect long-term involvement.”
My cousin Peter frowned.
“What does that mean?”
“Some shareholders are contributing actively.”
She gestured around the table.
“Others have become passive.”
Nobody said my name.
They did not need to.
Vanessa clicked again.
A simplified capitalization chart appeared.
Family holdings.
Hart Capital holdings.
Employee pool.
My personal common shares appeared beneath a label:
PASSIVE FAMILY INTEREST — 5.8%.
At least she had the percentage right.
“Jordan?” Uncle Richard asked.
“Yes.”
Mom answered before Vanessa could.
“It makes sense.”
I felt something tighten behind my ribs.
Vanessa continued.
“The proposal is to make a fair offer for Jordan’s shares, either through the company or through participating family members.”
Peter looked uncomfortable.
“Does Jordan want to sell?”
“We haven’t asked yet.”
“Then why are we discussing it?”
Mom leaned forward.
“Because Jordan has no involvement here.”
“She inherited those shares.”
“So did all of us.”
“Grandpa gave hers directly.”
The room shifted.
That detail mattered.
Most of the family stock had been placed into trusts and distributed through Dad and Richard.
My grandfather had personally transferred my original shares when I was twenty-three.
He included a note.
Use these wisely. Build something real.
I still had it.
Vanessa kept her voice professional.
“No one is taking anything from Jordan. We would pay fair value.”
“Which value?” Marcus asked.
“Book value with a premium.”
I actually laughed in the car.
Book value.
For a manufacturing company that had undergone enormous capital restructuring and held customer relationships, machinery, intellectual property, and real estate whose economic value could not be captured by a simple book calculation.
Marcus frowned.
“That’s not necessarily fair value.”
Mom looked annoyed.
“Why are you arguing?”
“I’m not. I’m pointing out that if you want Jordan to voluntarily sell, using an aggressive insider valuation is a bad place to start.”
That earned him another degree of respect.
Dad made a note.
“We’ll have an independent valuation.”
“Good.”
Then he added, “But I agree we should consolidate active-family control where possible.”
There it was.
Not illegal.
Not even irrational on its face.
Just revealing.
They wanted my grandfather’s shares back because they believed I had failed to become important enough to deserve them.
The conversation moved to Hart Capital.
Uncle Richard asked the question I had been waiting for.
“Do we know anything more about them?”
Dad shook his head.
“Private investment partnership. Multiple vehicles. Their counsel is excellent. Their capital has always shown up.”
Diane, Richard’s wife, frowned.
“That amount of money without demanding more control makes me nervous.”
Marcus nodded.
“It should.”
Vanessa looked at him.
“You’ve said for years they’re ideal investors.”
“I said they’ve behaved like unusually patient investors.”
“What’s the difference?”
“Patient investors still have rights.”
He tapped the capitalization chart.
“They’re at forty-seven percent voting ownership. Add preferred protections and whatever debt covenants exist, and we should stop talking about them like an ATM.”
Thank you, Marcus.
My sister rolled her eyes.
“You’re being dramatic.”
“No. I’m being a private-equity professional.”
Dad looked irritated.
“Hart Capital has never interfered.”
“Which means either they trust you,” Marcus said, “or they’re waiting.”
I leaned back in my seat.
He had no idea how correct that sounded.
Mom asked, “Waiting for what?”
“For a reason not to be passive.”
Vanessa dismissed that.
“So what do you suggest?”
Marcus thought for a moment.
“Before Bennett, we need a direct relationship with their principals. Not just lawyers and finance people. We should discuss governance, maybe explore repurchasing some of their equity if financing markets allow it.”
Dad nodded slowly.
“I’ve wanted that for some time.”
“Then request a principal meeting.”
I wrote the words down.
Request a principal meeting.
That, more than anything, determined what happened next.
The meeting continued another forty minutes.
Assignments were made.
Vanessa would lead initial Bennett diligence.
Marcus would help structure a financing proposal.
Dad would contact Hart Capital requesting a face-to-face meeting with senior decision-makers.
The company’s outside lawyers would commission an independent valuation before making any offer for my personal shares.
That last change probably came from Marcus.
I appreciated it.
Then people began packing their folders.
I nearly ended the stream.
Then I heard Vanessa laugh.
“Jordan will make the share thing emotional.”
Mom replied without hesitation.
“Everything involving your grandfather becomes emotional with Jordan.”
“It was his gift.”
“I know. But sentiment isn’t a business strategy.”
Vanessa lowered her voice.
“She’ll say we’re pushing her out.”
“You are not pushing out someone who never came in.”
There are sentences that do not look important on paper.
They become important because of who says them.
My mother continued.
“Jordan has her little investment work. She’s fine. Some people build companies. Some people support from the edges.”
Vanessa gave a small laugh.
“She likes the edges.”
I closed the laptop.
For several seconds, the garage was completely silent.
Then my phone rang.
Elena.
I answered.
“You watched to the end,” she said.
“Yes.”
“I did too.”
I gripped the steering wheel.
“Tell me not to do anything from the parking garage.”
“Do not do anything from the parking garage.”
“Thank you.”
“You sound angry.”
“I am.”
“That is allowed.”
“I know.”
“Anger is information. It is not governance.”
Sometimes I hated lawyers.
“What do you recommend?”
“A full internal review before any response. Ownership rights. Board rights. related-party transactions. Compensation. Funding covenants. Everything.”
“You think there’s a problem?”
“I think we should know whether there is a problem before your family asks you for seventy million dollars.”
I started the car.
“I’m coming to Cambridge.”
“Good.”
Hart Capital’s office was not impressive by venture-capital standards.
That was intentional.
We occupied most of the seventh floor of a brick-and-glass building in Cambridge, close enough to Kendall Square to meet technology companies without paying for a lobby designed to intimidate them.
Our furniture was good.
Our coffee was better.
Nothing had our name carved into marble.
When I arrived, David was already in the conference room.
So were Elena, two analysts, and our controller.
David looked up.
“How bad?”
“Family part or company part?”
“Company first.”
“Potentially manageable.”
“Family?”
“Do you have alcohol?”
“It’s eleven twenty in the morning.”
“That was not my question.”
One of the analysts smiled.
Elena did not.
She slid a folder toward me.
“We pulled the governance documents.”
I sat down.
My five-point-eight-percent direct common stake combined with Hart Capital’s converted voting equity placed entities I controlled at approximately fifty-two-point-eight percent of total voting power.
That did not mean I could do anything I wanted.
Majority shareholders owe duties.
Boards have authority.
Debt documents have procedures.
State corporate law does not become optional because the person holding fifty-two percent is angry at Thanksgiving memories.
But it did mean something important.
If necessary, we could elect directors.
We could block an acquisition requiring shareholder approval.
Hart Capital could refuse new money.
We could insist on compliance with the consent rights already written into the financing agreements.
David opened another binder.
“We also reviewed cash.”
“How much runway?”
“Without new financing, assuming current orders hold, eight to ten months.”
“That bad?”
“Working capital deteriorated in Q3.”
“Why?”
“Inventory.”
I frowned.
“We funded an inventory-management overhaul.”
“They bought ahead of projected aerospace demand.”
“Who approved it?”
He looked at me.
“Vanessa’s growth group pushed it. Operations objected. Dad sided with Vanessa.”
I exhaled.
“How much?”
“About eleven million more inventory than plan.”
“Wonderful.”
Elena added, “There’s more.”
There usually was.
Hart Capital had required quarterly reporting and annual outside audits.
Nothing in those reports suggested massive theft or fictional books.
But our team had identified related-party spending that deserved scrutiny.
Several senior family executives had compensation far above market.
Hartwell paid for two country-club memberships justified as customer-development expenses.
Three luxury vehicle leases were allocated partly to business use.
A vacation property in Maine had been used for customer retreats twice but family weekends many more times.
A vendor partly owned by a cousin had received maintenance contracts without competitive bids.
None of this automatically meant fraud.
Some could be legitimate business expenses.
Some could be taxable perks.
Some could simply be bad governance.
But when a company has received one hundred eighty million dollars in rescue and growth capital, “bad governance” stops being cute.
“How long have we known?”
“Pieces of it,” David said. “Not enough to justify intervention before. The aggregate is uglier.”
I looked around the table.
“What would you do if Hartwell had no relationship to me?”
That was the test I forced myself to use.
Elena answered first.
“Pause acquisition discussion.”
David nodded.
“Install stronger board oversight.”
Our controller added, “Independent compensation review.”
One analyst said, “Related-party transaction policy.”
“Management changes?” I asked.
David hesitated.
“Not automatically.”
“Why?”
“Because operating performance has improved in several areas. Richard’s plants are better. Safety metrics are strong. On-time delivery improved. Vanessa is not useless, Jordan. Some of the diversification strategy worked.”
“I know.”
“You asked what we’d do if they weren’t family.”
“Yes.”
“We wouldn’t fire capable managers simply because governance was sloppy. We’d fix governance and measure performance.”
That answer mattered.
I had not built Hart Capital to become the person my family believed I was.
Petty.
Emotional.
Unable to separate sentiment from business.
“Okay.”
Elena leaned forward.
“They requested a principal meeting this morning.”
I looked up.
“That fast?”
“Your father called our outside counsel at ten fifty-two.”
“What did he say?”
“He wants to discuss Bennett, future financing, and ‘alignment around long-term ownership.’”
I laughed without humor.
“Meaning buy back some of our equity.”
“Probably.”
“Give him the meeting.”
“When?”
“One week.”
Elena studied me.
“You’re sure?”
“Yes.”
“Do you want your identity disclosed in advance?”
“No.”
“Jordan.”
“They asked to meet the principal.”
“Yes.”
“I’m the principal.”
“That is not what I’m asking.”
I knew.
She wanted to know whether I was staging an ambush.
Maybe I was.
But there was a difference between an ambush and allowing someone to arrive at a fact he could have discovered years earlier if he had been curious enough to look.
“I want all shareholders of record invited,” I said.
Elena leaned back.
“That will include your personal stake.”
“Yes.”
“And therefore you.”
“Yes.”
Her mouth twitched.
“You have thought this through.”
“For approximately ninety seconds.”
“That is not reassuring.”
“Draft the invitation.”
Three days later, Hartwell’s board received a formal email.
Hart Capital Partners acknowledged the request for a principal-level meeting.
The agenda would include capital allocation, governance, ownership, Bennett Manufacturing, and future financing.
All significant shareholders and directors were requested to attend.
The meeting was scheduled for Tuesday at two.
Dad called me within an hour.
I answered on the third ring.
“Jordan.”
“Hi, Dad.”
“We have an important investor meeting Tuesday.”
“I heard.”
That surprised him.
“How?”
“I’m still a shareholder.”
A pause.
“Right.”
I waited.
“We need all family owners there.”
I looked at the ceiling.
Six days earlier, I had been too irrelevant for a family ownership discussion.
Now I was part of the united front.
“I can make it.”
“Good.”
Another pause.
Then, astonishingly:
“Wear something professional.”
I looked down at the navy suit I was wearing in my own office.
“What do you think I wear to work?”
“I don’t know. Business casual?”
I nearly laughed.
“Sure, Dad.”
“This group controls a lot of our future. We need to make a strong impression.”
“I understand.”
“And Jordan?”
“Yes?”
“Whatever you think about the share discussion, Tuesday isn’t the day.”
“What do I think about the share discussion?”
He went quiet.
So no one had planned to tell me yet.
Finally he said, “Vanessa may have mentioned consolidating family ownership.”
“She did not.”
“Well, nothing has been decided.”
“I’m glad.”
“We’ll talk later.”
“I’m sure we will.”
I ended the call.
The next week moved slowly.
We conducted what Elena called a pre-governance review.
I called it learning how much trouble I was in before announcing I owned the trouble.
Our conclusions were not catastrophic.
Hartwell was not secretly insolvent.
There was no giant embezzlement scheme.
The books were real.
The factories worked.
Customers existed.
Employees produced valuable things.
That made the situation more complicated.
The company was worth saving.
Again.
But family governance was damaging it.
Compensation had drifted.
Decision-making lacked discipline.
Major capital projects passed through emotional alliances rather than clear investment criteria.
Vanessa had been right about several growth opportunities and dangerously optimistic about others.
Dad remained talented with customers but increasingly resistant to anyone challenging him.
Uncle Richard was probably the strongest operating executive in the family.
Marcus was not an employee but had advised on deals despite having potential conflicts through his private-equity work.
The outside board was too friendly.
Nobody wanted to offend the Hartwells.
That would change.
Bennett also looked less attractive with every new document.
Environmental reports referenced legacy solvent use at one property.
Pension obligations were unclear.
A major aerospace contract had a change-of-control clause that could reduce the value of the acquisition materially.
I told our team to continue diligence quietly.
No decision before the meeting.
Tuesday arrived cold and bright.
I wore a charcoal suit.
Not because Dad told me to.
Because it was the same suit I wore when asking chief executives why their forecasts did not match their bank accounts.
I arrived at Hartwell headquarters at 1:42.
Vanessa was in the conference room.
So was Mom.
She looked relieved when she saw me.
“You came.”
“I said I would.”
Dad emerged from his office.
“Good.”
He looked me up and down.
Then nodded at my suit.
I almost admired his consistency.
Inside, two empty chairs waited at the far end of the table.
Small tent cards sat in front of them.
HART CAPITAL PARTNERS.
I put my portfolio beside one.
Mom noticed immediately.
“Jordan, those seats are for the investors.”
“I know.”
“Then sit over here.”
She pointed toward the opposite side near my cousin Peter.
“I’m comfortable here.”
Vanessa frowned.
“Why are you being difficult?”
“Maybe I like the view.”
“Jordan.”
I opened my laptop.
No one knew what to do with me.
Then the door opened.
Elena entered first.
Dark green suit.
Black leather folder.
Professional expression.
David came behind her.
Then two members of our investment team.
Dad stood.
His board members stood too.
Mom moved toward the door with her best hosting smile.
“Welcome. I’m Margaret Hartwell.”
“Elena Vasquez. General counsel for Hart Capital Partners.”
They shook hands.
“This is David Chin, our chief financial officer. Priya Shah from our investment team, and Andrew Cole from portfolio operations.”
Dad looked toward the hallway.
“Will your managing partner be joining?”
Elena looked at me.
The whole room followed her eyes.
I closed my laptop.
Then I stood.
“Yes.”
Dad frowned.
I walked around the corner of the table and held out my hand.
“Jordan Hartwell. Founder and managing partner of Hart Capital.”
Nobody moved.
I kept my hand extended.
My father stared at it as if he had forgotten what hands were for.
Then he looked at Elena.
Then David.
Then the black portfolio in front of me.
HART CAPITAL PARTNERS.
Vanessa laughed.
It came out too quickly.
“That’s not funny.”
“I’m not joking.”
Dad still had not taken my hand.
I lowered it.
Mom whispered, “What are you talking about?”
Elena opened her folder.
“Hart Capital Management LLC was founded by Jordan Hartwell six years ago. Ms. Hartwell serves as managing partner and chairs its investment committee. Our affiliated investment vehicles currently hold approximately forty-seven percent of Hartwell Industries’ voting equity, along with secured and preferred instruments described in your company’s capitalization records.”
No one said anything.
David placed a document in front of Dad.
“Your counsel has copies of the underlying ownership disclosures from each financing transaction. Beneficial-ownership information was provided where legally required. Hart Capital never misrepresented its identity.”
Dad picked up the paper.
His hands did not shake dramatically.
Real shock is often smaller.
His thumb simply stopped moving along the page.
Vanessa stared at me.
“You run Hart Capital.”
“Yes.”
“The entire fund.”
“The management company.”
“How much?”
I knew what she meant.
“How much what?”
“How big is it?”
David answered.
“Across committed and managed capital, approximately seven hundred twenty million dollars.”
Mom sat down.
“You told us you did investment consulting.”
“No.”
I looked at her.
“You told people I did investment consulting.”
“You never corrected us.”
“That part is true.”
Vanessa’s face was changing.
Shock first.
Then embarrassment.
Then anger.
“How long?”
“Hart Capital began six years ago.”
“And TechBridge?”
“Was profitable.”
She blinked.
“You closed it.”
“Yes.”
“Because it failed.”
“No.”
The word came out very quietly.
“I sold the client portfolio and wound the business down because managing Hart Capital required all of my time.”
“For how much?”
“That’s not relevant.”
“Jordan.”
“Not relevant.”
Marcus had not spoken.
He was staring at the ownership schedule.
Then he looked at me.
“You’re controlling Hart Capital’s forty-seven percent.”
“Yes.”
“And you still hold Grandpa’s common shares directly.”
“Yes.”
His face tightened.
“That puts you over fifty.”
“About fifty-two-point-eight percent of total voting power, subject to the rights and limitations in the charter.”
My father finally looked up.
“You control the company.”
“I have voting control.”
“That’s the same thing.”
“No.”
For the first time that afternoon, my voice sharpened.
“A company still has a board. Officers still have duties. Majority owners still have legal obligations. If you’ve spent the last few years assuming one person owning more than half means that person can simply do anything she wants, we have an even larger governance problem than I thought.”
Marcus looked down.
He knew I was right.
Vanessa sat back.
“You did this deliberately.”
“Which part?”
“Hidden behind some anonymous fund while we—”
“Hart Capital was not anonymous.”
“You knew we didn’t know.”
“Yes.”
“Why?”
There it was.
The question I had asked myself for years.
I could have given a speech.
I did not.
“I wanted the investment evaluated professionally.”
“That’s not why.”
“No.”
I met her eyes.
“I also wanted to know whether anyone in this family would ever become curious enough about my life to learn what I actually did.”
Silence.
Mom spoke first.
“That is incredibly unfair.”
“Maybe.”
“You were testing us?”
“At first.”
“For six years?”
“No. After the first couple of years, I had my answer.”
Vanessa looked wounded.
Strangely, that hurt.
“I would have asked.”
“You didn’t.”
“If I knew there was something to ask about.”
The sentence landed harder than she intended.
I nodded once.
“Exactly.”
Dad sat down.
He looked suddenly tired.
“Why invest in Hartwell?”
That question mattered more.
I answered honestly.
“Because in 2020 this company was six weeks from a serious liquidity crisis.”
Mom looked at him.
Dad said nothing.
I continued.
“Because the Lowell plant had equipment customers still valued. Because the workforce was better than management understood. Because your customer relationships were real. Because Grandpa built something worth preserving.”
I glanced toward his photograph.
“And because I believed the business could recover if someone gave it enough capital and demanded enough reporting without immediately ripping the family out of it.”
“You saved us,” Uncle Richard said.
I disliked the word.
“Hart Capital invested.”
“One hundred eighty million,” he said.
“Yes.”
Mom stared at me.
“That money was yours?”
“Some was mine. Most was capital our firm was responsible for on behalf of investors.”
“Then stop saying you saved the company.”
“I did not say that.”
Everyone went quiet.
My mother had expected me to claim victory.
When I did not, some of her anger had nowhere to go.
Elena spoke.
“We should move to the agenda.”
Professional rescue.
I sat.
So did everyone else.
The first item was Bennett.
David distributed our preliminary analysis.
Dad glanced through it.
“You already reviewed the acquisition?”
“You requested sixty to seventy million dollars from our capital base,” I said. “Of course we reviewed it.”
“We haven’t formally requested anything.”
“Correct. But you built a transaction plan around expected Hart Capital support.”
Dad’s jaw tightened.
“We believed our history justified discussing it.”
“Discussing, yes. Assuming, no.”
Vanessa leaned forward.
“We would never sign without financing.”
“I know.”
That surprised her.
“I watched the family session last week.”
Her face went pale.
“You what?”
“Hart Capital has contractual observer rights.”
“You were listening?”
“Yes.”
“To a private family session?”
“It transitioned into a financing and ownership discussion involving Hart Capital. Our authorized feed remained active.”
She looked toward Dad.
He looked toward the outside directors.
No one had checked when the remote observer disconnected.
Another governance problem.
Vanessa’s voice rose.
“You were spying on us.”
“I was monitoring a company in which my firm has one hundred eighty million dollars deployed.”
“You listened after you left.”
“Yes.”
“Why?”
“Because I wanted to know what people said when they believed I had no power.”
Mom closed her eyes.
I immediately regretted the sentence.
Not because it was false.
Because it sounded too much like revenge.
Elena glanced at me.
Anger is information. It is not governance.
I reset.
“Let me be clearer. I should not have made that personal. Hart Capital was entitled to monitor the session once financing and investor ownership were being discussed. I chose to listen personally because of the family issue. That was emotional. The business conclusions we’re presenting today were independently reviewed.”
Marcus looked at me differently after that.
Not warmly.
Respectfully.
I had admitted the part that was mine.
That mattered to people who understood decision-making.
David continued with Bennett.
“The company may still be attractive, but not at the price discussed.”
He summarized the risks.
Potential environmental remediation.
Pension exposure.
Customer concentration.
Change-of-control provisions.
Deferred maintenance.
“We estimate the true all-in cost could exceed one hundred million dollars depending on environmental findings.”
Dad stared at the report.
Vanessa flipped pages rapidly.
“Where did you get this?”
“Public records, seller materials, third-party consultants, and standard diligence sources.”
“You did all this in a week?”
Priya, one of our analysts, answered.
“We started when the opportunity first appeared in your monthly strategic report.”
Vanessa looked at her.
Then at me.
For years, my sister had treated investing as something abstract.
Money people.
Finance people.
People who appeared after founders did the real work.
Now she was seeing what the work looked like.
I did not enjoy her discomfort.
I enjoyed the accuracy.
“The recommendation,” I said, “is no financing commitment until full environmental, pension, customer, and operational diligence is complete.”
Dad nodded slowly.
“That’s reasonable.”
Vanessa looked at him.
“Dad.”
“It is.”
“We lose momentum.”
“If the deal cannot survive thirty more days of diligence,” Marcus said, “we should lose it.”
My sister glared at her husband.
He shrugged.
“She’s right.”
I almost smiled.
The next agenda item was governance.
That was harder.
Elena distributed a memorandum.
No accusations.
No theatrical claims about fraud.
Just facts.
Executive compensation had increased thirty-eight percent over three years while free cash flow remained negative.
Several related-party vendor arrangements lacked competitive documentation.
Business-use policies for vehicles, clubs, and retreat properties were poorly defined.
Inventory decisions had bypassed operating objections.
Outside directors had few meaningful committee processes.
The board lacked an independent audit chair.
Hart Capital’s concern was simple:
The company had become too dependent on informal family judgment for a business of its size and capital structure.
Dad’s face hardened as he read.
“This feels like an indictment.”
“It isn’t,” I said.
“Then what is it?”
“A governance review.”
“You think I’ve mismanaged the company.”
“I think you managed it the way Grandpa managed a company one-third this size in 1998.”
Richard made a quiet sound that might have been a cough.
Dad looked at him.
“Something funny?”
“No.”
I continued.
“That does not make you incompetent. It means the company outgrew the system.”
Vanessa stared at one page.
“My compensation is listed.”
“Yes.”
“Forty percent above benchmark?”
“Approximately.”
“Who decided that?”
“An independent compensation consultant.”
“I bring in major opportunities.”
“You also pushed eleven million dollars of excess inventory against operations’ recommendation.”
“That inventory supports growth.”
“Maybe. We’ll know when customers buy it.”
Her cheeks went red.
Mom intervened.
“You are enjoying this.”
I looked at her.
“No.”
“You expect me to believe that?”
“Yes.”
“You spent years letting us think you had failed.”
“I spent years letting you think whatever you wanted because asking questions became too exhausting.”
“That is not the same as honesty.”
She was right.
The room went still.
I looked at her.
“No. It isn’t.”
That answer unsettled her.
“I should have told you more about my life,” I said. “Not because you earned the information. Because silence became its own kind of resentment.”
No one moved.
“But my silence does not excuse excluding me from family decisions because you assumed I was unsuccessful. It does not make the plan to buy my grandfather’s shares at an insider-friendly valuation appropriate. And it does not make Hart Capital’s money something this family can plan around without asking.”
Dad leaned back.
“So what do you want?”
Finally.
Not what are you doing.
Not how could you.
What do you want?
I opened the last folder.
“Three things.”
Vanessa muttered, “Of course.”
I ignored it.
“First, Bennett stops until diligence is complete.”
Dad nodded once.
“Second, we restructure the board.”
His expression changed.
“How?”
“Seven seats. Three independent directors selected jointly from an agreed list. Two Hart Capital designees. Two family designees.”
“That gives you control,” Mom said.
“I already have majority voting power.”
“You keep saying that.”
“Because everyone keeps acting surprised.”
Elena almost smiled.
I continued.
“The board gets an independent audit committee, compensation committee, and related-party transaction policy.”
Richard asked, “And management?”
“Reviewed, not purged.”
Vanessa laughed bitterly.
“How generous.”
I looked at her.
“You are good at strategic sales, partnerships, and positioning.”
That stopped her.
“I think your current role is too broad. You need measurable targets and less authority over capital allocation.”
Her eyes narrowed.
“So you’re demoting me.”
“I am recommending that the board redefine the role.”
“You own the votes.”
“Yes.”
“So recommendation means order.”
“No. It means I expect directors to use judgment. If I wanted puppets, I could have kept the current board.”
One of the outside directors looked down.
Uncomfortable.
Good.
“Uncle Richard should retain operating responsibility,” I said. “He has improved plant performance materially.”
Richard stared at me.
I had never praised him to his face before.
“Dad should remain president during a transition while we begin an external CEO search.”
Mom whispered, “External?”
Dad went completely still.
I met his eyes.
“You’re sixty-eight.”
“I’m aware.”
“You’ve refused succession planning for eight years.”
“This is my company.”
“It was Grandpa’s company.”
His face tightened.
“And now?”
I took a breath.
“Now it belongs to everyone on the cap table.”
That was the answer business required.
He hated it.
So did part of me.
The third item concerned the family’s shares.
I slid the independent valuation engagement letter toward Vanessa.
“Do not prepare a buyout offer for my shares.”
“No one has.”
“You discussed one.”
“Yes.”
“I’m not selling.”
Mom folded her arms.
“Then why mention it?”
“Because I want it clear.”
I looked around the table.
“Those shares were Grandpa’s gift to me. They are not an administrative inconvenience. They are not available because you think I’m inactive. I will keep them.”
Vanessa looked toward Grandpa’s photograph.
Then back.
“Fine.”
Her voice was quiet.
Not defeated.
Just finished fighting that point.
Dad rubbed his forehead.
“And if we refuse all this?”
Elena answered before I could.
“Hart Capital has existing voting and consent rights it can exercise lawfully. Ms. Hartwell’s controlled entities hold a majority of voting power. We could pursue board changes through formal shareholder processes.”
Dad stared at me.
“So this isn’t a choice.”
“It is.”
“How?”
“I can force a governance fight,” I said. “Or we can agree on a structure that keeps family members involved where they’re qualified, protects employees, protects investors, and gives the company a chance to grow without turning every disagreement into a civil war.”
“And funding?”
“No new Hart Capital money until governance changes are signed and Bennett diligence is complete.”
Mom’s voice hardened.
“So you are holding the company hostage.”
“No.”
I shook my head.
“I am refusing to write another check before the people spending it accept oversight.”
“That is the same thing.”
Marcus finally spoke.
“No, Margaret. It isn’t.”
Every face turned toward him.
He looked tired.
“Any institutional investor at forty-seven percent would have demanded this years ago.”
Vanessa stared at her husband.
“Whose side are you on?”
“The side where we don’t pretend capital is free.”
I almost felt sorry for her.
She had walked into the room expecting a negotiation with strangers.
Instead, her husband was agreeing with the sister she had excluded.
Dad looked at Elena.
“What happens if we reject the restructuring?”
She answered clinically.
“Hart Capital exercises its contractual rights. No acquisition financing. We seek board changes. If the company later requires capital, you are free to seek outside financing.”
“Would anyone provide it?”
“That is not a legal question.”
David answered the economic one.
“Possibly, but likely on more expensive terms given current leverage, working capital, and governance issues.”
Richard rubbed his jaw.
“So the rational choice is restructuring.”
“Yes,” Marcus said.
Vanessa turned on him.
“Would you stop helping?”
“I am helping.”
“No. You’re helping Jordan.”
He looked at her for a long time.
Then said something that changed the room.
“Jordan has been helping us for three years.”
My sister looked down.
No one spoke.
I could have made a triumphant speech then.
I wanted to.
That is the truth.
I wanted to remind Mom about support staff.
Wanted to ask Vanessa whether failed entrepreneurs usually controlled nearly half of a company’s rescue financing.
Wanted to ask Dad if my suit was professional enough now.
Instead, I heard my grandfather’s voice.
Build something real.
Humiliation is not construction.
I closed the folder.
“You don’t have to decide in this room.”
Dad looked surprised.
“I thought you wanted signatures today.”
“No.”
Elena glanced at me.
That had been our initial plan.
I had changed my mind.
“Take forty-eight hours. Have independent counsel review everything. Not Hartwell’s regular counsel. Someone none of us selected. If you believe the structure is unfair, propose alternatives.”
Mom stared at me.
“You would accept alternatives?”
“If they solve the same problems.”
“What problems?”
“Independent oversight. Capital discipline. Compensation. related-party transactions. Succession.”
She sat back.
“You really think you’re the adult in the room.”
The sentence hurt more than I expected.
I answered slowly.
“No.”
“I think I’m the majority investor in the room.”
Then I gathered my papers.
The meeting ended without signatures.
That disappointed everyone expecting an explosion.
Real power rarely looks as satisfying as people imagine.
No security guards appeared.
Nobody was thrown out.
Dad did not collapse.
Vanessa did not scream.
My family simply walked into Conference Room B with independent counsel on speakerphone while I went upstairs to the office my grandfather had once used and closed the door.
His old desk was gone.
Dad replaced it years earlier with something larger.
But the window still overlooked the same parking lot.
I stood there for several minutes.
Elena entered without knocking.
“You changed the forty-eight-hour term.”
“Yes.”
“I noticed.”
“Problem?”
“No.”
She leaned against the door.
“Why?”
“Because making them sign while shocked would feel good for ten minutes and poison the restructuring for ten years.”
“That is annoyingly mature.”
“I’m furious.”
“You can be both.”
I looked outside.
“They really didn’t know.”
“No.”
“My own father thought I dressed business casual.”
“That may be the most offensive part.”
I laughed.
Then, unexpectedly, I cried.
Not much.
Just enough that I had to turn away.
Elena gave me the courtesy of pretending to review a document.
“I thought the reveal would make me feel better,” I said.
“It usually doesn’t.”
“You could have warned me.”
“I did.”
“No, you used lawyer words.”
“That is how warnings become billable.”
I laughed again.
By five, most of my family had left.
Dad remained.
He appeared in the doorway.
Elena gathered her papers.
“I’ll give you privacy.”
When she left, Dad stepped inside.
For years, he had seemed completely natural behind that desk.
Now he stood across from me as if unsure who belonged there.
“I owe you an apology.”
I folded my arms.
“For which thing?”
He accepted that.
“Several.”
“Okay.”
“I should have asked about TechBridge.”
“Yes.”
“I should have asked what came after.”
“Yes.”
“I should have known Hart Capital’s structure better.”
“That one is more your CFO and counsel than you personally.”
He looked surprised.
“You’re defending me?”
“I’m being accurate.”
He nodded.
“I also should not have allowed the discussion about your shares without speaking to you first.”
“No.”
“We weren’t planning to steal them.”
“I know.”
“I need you to know that.”
“I do.”
He sat in one of the guest chairs.
“The buyout idea seemed reasonable.”
“To you.”
“Yes.”
“Because you thought I didn’t matter to the company.”
He looked down.
“Yes.”
There are moments when an apology hurts more after someone finally tells the truth.
Dad continued.
“I thought you had chosen a smaller life.”
I stared at him.
“A smaller life.”
“I don’t mean that the way it sounds.”
“You definitely do.”
He rubbed both hands over his face.
“I thought Vanessa wanted the company. Richard wanted it. You didn’t.”
“I didn’t want a title here.”
“That looked like not caring.”
“Those are different.”
“I know that now.”
I sat opposite him.
“Why didn’t you ask?”
He had no answer.
Then he gave the only honest one.
“Because Vanessa was easier to understand.”
That surprised me.
“She was loud about what she wanted.”
He smiled faintly.
“Exactly.”
“And I wasn’t.”
“No.”
He looked toward the window.
“You were always private. Even with your grandfather.”
“Grandpa asked questions.”
Dad looked at me.
The truth landed.
He nodded.
“Yes.”
My grandfather had done something my father rarely did.
He waited through silence.
When I was nineteen, he once drove me two hours to look at a used milling machine because I mentioned in passing that I wanted to understand manufacturing economics.
He did not explain the company the entire way.
He asked what I thought.
That difference shaped my life more than anyone knew.
Dad stood.
“We’ll give you an answer tomorrow.”
“You have forty-eight hours.”
“We don’t need them.”
I looked at him.
He exhaled.
“Marcus is right.”
That probably cost him.
“The governance should have changed years ago.”
“What about the CEO search?”
His jaw tightened.
“I hate it.”
“Fair.”
“I also know I’m sixty-eight.”
“Also fair.”
He moved toward the door.
Then stopped.
“Was Grandpa proud of you?”
The question broke something open in me.
I answered quietly.
“I think so.”
Dad nodded.
“I wish I’d paid enough attention to know why.”
Then he left.
The family accepted the restructuring the next afternoon.
Not every detail.
We negotiated.
That mattered.
Richard argued successfully for two family board seats rather than one.
Dad wanted eighteen months before completing the CEO transition.
We settled on twelve with an extension available if the board believed the search required it.
Vanessa wanted her role evaluated after six months, not reduced immediately.
I agreed.
Compensation would be benchmarked by the independent committee.
My mother insisted the Maine property be removed from company ownership rather than simply regulated as a corporate asset.
That was actually sensible.
A valuation was obtained.
The family bought it personally.
Hartwell stopped paying for it.
By the end of three weeks, the new structure was signed.
The outside directors who had spent years politely agreeing with Dad were thanked and rotated off.
Our replacements were not hostile.
They were worse.
Competent.
Laura Bennett—not related to Bennett Manufacturing—had spent thirty years running industrial operations for a public aerospace supplier.
Michael Okafor was a former CFO known for making executives explain capital projects in one-page memos before he allowed anyone to show him a PowerPoint.
Denise Kaplan had served on three manufacturing boards and chaired audit committees through two recessions.
The first independent board meeting lasted four hours.
Dad hated it.
Vanessa hated it more.
Uncle Richard loved it.
I watched him come alive the first time Laura asked a detailed question about machine utilization instead of talking about “legacy.”
The governance review produced uncomfortable changes.
Vanessa’s compensation fell twenty-eight percent, not forty.
The consultant concluded part of her pay was justified by the partnerships she had developed.
She was furious for three days.
Then she asked for written performance metrics.
That was the smartest thing she could have done.
Dad’s compensation also came down.
So did Richard’s, though less.
The company canceled one luxury vehicle lease.
The others were restructured under a documented business-use policy.
Country-club memberships required customer-development reporting.
The related-party maintenance vendor was forced into a competitive bid and, to everyone’s embarrassment, won anyway at a lower price.
That taught us something useful.
Not every family relationship is corrupt.
Undocumented relationships simply make it impossible to know.
Marcus voluntarily stopped advising Hartwell transactions.
His employer’s compliance department had become uncomfortable with the overlap.
He and Vanessa fought about it privately.
I knew because she told me.
That conversation happened three months after the reveal.
She came to my office in Cambridge without calling.
My assistant appeared at the door.
“Your sister is here.”
“Which mood?”
“She looks like she hasn’t slept.”
“Send her in.”
Vanessa entered wearing black trousers, a gray sweater, and no jacket.
No presentation.
No leather portfolio.
Just my sister.
She sat across from me.
“I hate this.”
“The restructuring?”
“You.”
“That seems more honest.”
She almost smiled.
Then her face hardened again.
“Do you know what it feels like to discover your entire family identity was wrong in one afternoon?”
“Yes.”
She looked irritated.
“Of course you’d say that.”
“I spent most of my life being told you were the builder and I was the failed experiment.”
“I never called you that.”
“No. You used nicer words.”
She looked down.
I waited.
That was something investing taught me.
Do not rescue silence.
People often tell you the important thing after they have run out of prepared sentences.
Finally she said, “I liked you failing.”
There it was.
I stayed still.
Vanessa’s eyes filled.
“I didn’t want bad things for you.”
“I know.”
“But when TechBridge closed…”
She stopped.
“It made things easier.”
“For you.”
“Yes.”
“How?”
“Because I knew my role.”
I said nothing.
“I was the successful daughter. The one continuing Grandpa’s business. The one Mom talked about. The one Dad relied on.”
Her voice shook.
“If you had been doing better than me the whole time, then what was I?”
“My sister.”
She laughed bitterly.
“That’s easy for you to say.”
“No.”
I leaned forward.
“It took me years to understand I was allowed to be a person even if you were impressive.”
That stopped her.
“We both let them turn us into positions.”
“What positions?”
“You were the future.”
I pointed toward myself.
“I was the cautionary tale.”
Vanessa wiped one cheek.
“I treated you badly.”
“Yes.”
“You’re really not going to make this easy.”
“No.”
“Why?”
“Because if I tell you it was nothing, you get to feel better without changing.”
She looked at me.
Then nodded slowly.
“Fair.”
That was the beginning of whatever relationship we have now.
Not an apology with music.
Not a hug across a conference table.
Accuracy.
The Bennett acquisition died two months later.
Our environmental consultants found contamination risk at one of the older facilities.
Not catastrophic.
But expensive.
The seller refused to adjust price enough.
A key aerospace customer also indicated it would reconsider the contract under new ownership.
Vanessa argued for the deal longer than I liked.
Then Michael Okafor asked her one question.
“If Hartwell did not need to prove it was growing, would you still want this company?”
The room became quiet.
Vanessa looked at the numbers.
Then said, “No.”
That answer may have saved Hartwell another seventy million dollars.
Six months later, we acquired a smaller manufacturer in New Hampshire.
Thirty-eight million purchase price.
Cleaner balance sheet.
Modern equipment.
Specialty medical and aerospace components.
Management stayed.
The integration was boring.
That was wonderful.
No magazine articles.
No giant strategy language.
Just purchasing savings, shared customers, better scheduling, improved margins, and a factory full of people who still had jobs after the transaction.
Hartwell turned genuinely cash-flow positive the following year.
For the first time since 2019, it funded most of its own capital expenditures.
David brought the quarterly report into my office.
He placed it on my desk without speaking.
I read the number twice.
Positive free cash flow.
No emergency capital.
No bridge.
No request.
I looked up.
“Is this real?”
He smiled.
“We checked three times.”
I leaned back.
“That feels better than I expected.”
“You realize normal investors like distributions.”
“I’m learning.”
He left.
I sat alone with the report.
For three years, I had told myself the money was about Grandpa.
Then about employees.
Then about preserving value.
All true.
There had also been another reason.
I wanted proof.
Proof that I could save what my family could not.
Proof that my quiet work mattered more than their visible titles.
Proof that the daughter outside the conference room was actually the person holding the floor beneath everyone inside.
That desire had helped me work.
It also made me dangerous.
Because once you build success partly to correct humiliation, success can become another argument you never stop having.
I did not want Hartwell to spend the next twenty years as evidence in a family trial.
So I changed something.
I stopped hiding Hart Capital.
Not publicly.
We were still a private firm.
But from my family.
At Thanksgiving that year, Dad asked me about one of our portfolio companies.
Not Hartwell.
A packaging manufacturer in Ohio.
“How do you decide whether automation is worth the labor disruption?”
I looked at him.
He frowned.
“What?”
“Nothing.”
“You’re staring.”
“I don’t think you’ve ever asked me an actual investment question.”
“Well, don’t make it weird.”
Vanessa laughed.
Mom did not.
Thanksgiving remained difficult with her.
Of everyone, my mother had the hardest time adapting.
Dad could understand ownership.
Vanessa could understand performance.
Richard could understand operations.
Mom understood family hierarchy.
For thirty-five years, she had known where everyone sat.
My reveal destroyed the seating chart.
She was polite to me.
Too polite.
“Jordan’s fund is doing well,” she told relatives.
Never Hart Capital.
Never what I had built.
Sometimes I thought she was embarrassed.
Sometimes I thought she felt betrayed.
Probably both.
Six months after the restructuring, she asked to sell most of her shares.
No argument.
No threat.
Just a letter through counsel.
Independent valuation.
Proper process.
The company repurchased a portion and an existing investment vehicle bought the rest.
She received a little over four million dollars.
Not the fortune she once imagined Hartwell would automatically become.
Enough to remain comfortable.
After the transaction closed, she invited me to lunch.
Not the country club.
A small Italian restaurant in Wellesley.
Progress sometimes arrives through restaurant choice.
She ordered soup.
I ordered salad.
For twenty minutes we discussed nothing important.
Then she put down her spoon.
“I think you wanted to punish us.”
I considered lying.
“Part of me did.”
Her eyes lifted.
“I knew it.”
“Part of me also wanted to keep the company from making expensive mistakes.”
“Both can be true?”
“Yes.”
She looked away.
“I don’t like that.”
“Neither do I.”
“Were you happy when you sat in that investor chair?”
“No.”
That answer surprised her.
“I thought I would be.”
“Why weren’t you?”
“Because the people who underestimated me were still my family.”
Mom looked down.
“You could have told us.”
“Yes.”
“I keep coming back to that.”
“So do I.”
“Why didn’t you?”
I thought before answering.
“Because at some point being unseen became part of my identity too.”
She frowned.
“I don’t understand.”
“If I told you who I was and you treated me differently, I would always wonder whether you loved me or the success.”
“That sounds exhausting.”
“It was.”
She picked at the edge of her napkin.
“Do you still wonder?”
“Yes.”
Her face changed.
I regretted the bluntness.
Then she nodded.
“I suppose I earned that.”
That was as close to an apology as my mother could come then.
Months later, she came closer.
My father’s transition from president was not graceful.
He agreed to an external search and then found something wrong with every candidate.
Too corporate.
Too young.
Too little manufacturing experience.
Too much manufacturing experience and not enough customer instinct.
One afternoon Laura Bennett closed her notebook.
“Tom, do you want a successor?”
Dad looked offended.
“Of course.”
“Do you want a successor you cannot criticize?”
Silence.
There are reasons independent directors cost money.
Eventually we hired Aaron Patel, fifty-four, an industrial executive who had run two divisions of a public components manufacturer.
He was not charismatic.
Vanessa disliked him immediately.
That reassured me.
Aaron spent his first month walking plants.
He knew machinists’ names before he knew most board members’ spouses.
He found three million dollars in annual savings by fixing scheduling and scrap processes nobody considered strategic enough for a presentation.
Dad respected him against his will.
The handoff took fourteen months rather than twelve.
On Dad’s final day as president, employees held a lunch in the Lowell plant cafeteria.
Not a hotel ballroom.
Dad insisted.
Someone brought a Costco sheet cake.
My mother hated the plastic lid.
Richard gave a speech.
Vanessa cried.
Then Dad asked me to come forward.
I nearly refused.
He handed me a small wooden box.
Inside was Grandpa’s old mechanical pencil.
The one he carried in his shirt pocket on the factory floor.
“I thought Richard had this.”
“He gave it to me when Dad died.”
“Why are you giving it to me?”
“Because you did what he asked.”
I stared at him.
“What did he ask?”
Dad smiled.
“You know.”
Use these wisely. Build something real.
My throat closed.
Dad continued quietly enough that only the people nearest us could hear.
“I thought building meant running Hartwell.”
I looked at him.
“I was wrong.”
That was the apology that mattered most.
Not because it erased anything.
Because he finally understood the difference.
Two years after the restructuring, Hartwell’s enterprise value was roughly three times what it had been during the rescue period.
Not because I arrived as some genius and fixed everything.
I did not.
Aaron fixed things.
Richard fixed things.
Vanessa fixed things.
Plant supervisors fixed things.
Engineers redesigned components.
Sales teams repaired customer relationships.
Hourly employees found process problems executives had never seen.
Hart Capital supplied capital and governance.
That mattered.
It was not the whole story.
My family had spent years making success about individuals.
Grandpa.
Dad.
Vanessa.
Then eventually me.
The company became healthier when we stopped needing one person to be the hero.
Vanessa remained with Hartwell.
Her title eventually changed to Senior Vice President of Strategic Partnerships.
Less glamorous.
More accurate.
Her compensation rose again after she hit performance targets for two consecutive years.
I approved the board committee’s recommendation.
She called me afterward.
“You’re giving me a raise?”
“The board is.”
“You voted for it.”
“Yes.”
She was silent.
“Why?”
“You earned it.”
Another silence.
Then:
“Thank you.”
Our relationship never returned to what people imagine sisters should be.
We do not call every day.
We do not vacation together.
We do not pretend the conference-room years never happened.
But we learned how to speak without competing for oxygen.
That is more valuable.
One Christmas, her daughter Lucy was assigned a school project about family businesses.
She interviewed Grandpa’s old employees.
Dad.
Richard.
Vanessa.
Then me.
She came to Hart Capital with a spiral notebook and the seriousness of a twelve-year-old who had been told the project counted for thirty percent of her grade.
“What do you do exactly?”
I laughed.
“That question took this family thirty years.”
She did not understand.
“Is that a joke?”
“Yes.”
“Okay. What do you do?”
So I told her.
We evaluate businesses.
We provide capital.
We help companies restructure.
Sometimes we take minority stakes.
Sometimes control positions.
Sometimes debt.
Sometimes we walk away.
“How do you know if a company is good?”
“You don’t.”
She frowned.
“That’s not a good answer.”
“It’s the true one.”
I explained that investors rarely get certainty.
They get evidence.
Customers.
Cash flow.
Management behavior.
Debt.
Competition.
Whether people tell the truth when the numbers turn bad.
Lucy wrote something down.
Then asked:
“Was Hartwell good?”
I looked through the glass wall of my office.
On one shelf sat Grandpa’s stock certificate.
Beside it, his mechanical pencil.
“Yes.”
“Then why did it almost fail?”
“Good companies can be badly managed.”
She wrote that too.
“Was Grandma bad?”
I turned back.
Children have a gift for asking the question adults avoid.
“No.”
“Was Mom?”
“No.”
“Was Grandpa?”
“No.”
“Then whose fault was it?”
I smiled.
“Companies are usually more complicated than that.”
She frowned again.
“Adults always say complicated when they don’t want to answer.”
Ruth Calder would have liked her.
I leaned forward.
“Okay. Everyone made mistakes. Some bigger than others. The problem was that we were better at being a family than being accountable to one another.”
“What does accountable mean?”
“Being willing to say what actually happened even when you love the person who caused it.”
Lucy wrote slowly.
Then she looked up.
“Mom says you saved the company.”
I shook my head.
“No.”
“She says you did.”
“I helped.”
“Is that the same?”
“No.”
“Why not?”
“Because lots of people helped.”
She seemed disappointed.
Children prefer heroes too.
Then she asked, “Were you mad when they didn’t let you in the meeting?”
“Yes.”
“How mad?”
“Very.”
“Did you want to fire everybody?”
I laughed.
“For about eleven minutes.”
“Why didn’t you?”
“Because wanting to do something isn’t the same as it being wise.”
She wrote that down.
I hope her teacher appreciated how much family therapy went into the assignment.
Hart Capital grew.
Not explosively.
Intentionally.
We raised another vehicle focused on family-owned industrial businesses facing succession or capital problems.
The irony was not lost on me.
I became known for something I never planned to specialize in:
Families who loved each other and could not govern companies together.
The pattern repeated everywhere.
A founder who could not retire.
A daughter doing the work while a son held the title.
Three siblings drawing salaries unrelated to responsibility.
A cousin who treated company property like personal inheritance.
Parents who could discuss customer churn but not childhood resentment.
I learned that balance sheets are often cleaner than families.
At meetings, I began asking one question early.
“If this decision involved strangers instead of relatives, what would you do?”
The answer usually revealed everything.
I also stopped allowing my own family story to become a marketing story.
People suggested it.
A communications adviser once said:
“Founder secretly rescues family company and takes control—that’s compelling.”
“No.”
“Why?”
“Because employees are not props in a sibling story.”
That ended it.
Hartwell’s turnaround became a case study internally.
Governance.
Capital discipline.
Succession.
Operational modernization.
No revenge.
No mystery investor reveal.
No family quotes.
That belonged to us.
My relationship with Mom remained the least repaired.
For a long time, that bothered me.
Then I understood something.
Not every boundary produces reconciliation.
Sometimes it produces distance.
Distance can still be healthier than false closeness.
We saw each other on holidays.
Talked every few weeks.
She remained closer to Vanessa.
I stopped treating that as a verdict.
One afternoon, nearly three years after the meeting, Mom came to my office.
She had never visited before.
My assistant called.
“Your mother is here.”
“Does she have an appointment?”
“No.”
Of course.
Some things do not change entirely.
“Send her in.”
She entered carrying a paper shopping bag.
“I brought lunch.”
I stared.
“Why?”
“People eat lunch.”
“Yes.”
“You forget.”
Also true.
She unpacked sandwiches from the deli near our old house.
Turkey for me.
Chicken salad for her.
Two pickles wrapped separately in wax paper.
We ate at the small round table beside my office window.
She looked around.
“This is smaller than I expected.”
“There’s another floor.”
“Oh.”
I smiled.
She noticed Grandpa’s stock certificate on the wall.
Then the photograph of him at the first Hartwell factory.
Beneath it was the note he had written.
Use these wisely. Build something real.
Mom stood.
“I remember his handwriting.”
“So do I.”
“He gave you the shares without telling your father first.”
“I didn’t know that.”
“He told Tom afterward.”
“Was Dad angry?”
“Not angry.”
She smiled faintly.
“Confused.”
“That tracks.”
Mom read the note again.
Then said, “Your grandfather worried about you.”
I looked at her.
“Why?”
“He thought you would spend too much of your life waiting to be understood.”
I stopped breathing for a second.
“He said that?”
“Not exactly those words.”
Of course.
“What did he say?”
Mom looked embarrassed.
“He said, ‘That girl is going to make people work too hard to know her.’”
I laughed.
“That sounds like him.”
“He also said the rest of us were lazy.”
“That sounds even more like him.”
We both laughed.
Then Mom became serious.
“I was lazy.”
I said nothing.
“About you.”
The office seemed very quiet.
“I knew what Vanessa wanted because she told me constantly.”
“Yes.”
“You didn’t.”
“No.”
“I decided that meant you didn’t need anything.”
I looked at her.
“You needed me to ask.”
My eyes burned.
“Yes.”
Mom nodded.
“I’m sorry.”
Not sorry for the meeting.
Not sorry for calling me a failure.
Not sorry for the shares.
Sorry for not asking.
That was the oldest wound.
And somehow the smallest sentence reached it.
I stood and hugged her.
We did not become a perfect mother and daughter afterward.
She still irritated me.
I still became defensive too quickly.
She still gave Vanessa more attention when Vanessa entered a room.
Old family rhythms do not disappear because everyone has a breakthrough over sandwiches.
But now Mom sometimes caught herself.
At Christmas, Vanessa once began telling a story about a customer conference while I was answering Aunt Diane’s question about a portfolio company.
Mom raised one finger.
“Wait. Jordan was talking.”
The entire table went silent.
Vanessa stared at her.
Then at me.
I laughed.
“What?”
Mom frowned.
“Nothing. Finish your story.”
I did.
A year later, Hartwell considered another acquisition.
This time Vanessa brought the target to Aaron.
Aaron took it to the board.
The board sent it through diligence.
Hart Capital reviewed it.
No one called me privately.
No one assumed financing.
No one framed disagreement as disloyalty.
The target passed.
Forty-six million dollars.
Good margins.
Clean environmental review.
Diversified customers.
Strong management.
Hartwell funded part of it from cash, part through ordinary senior debt, and only a modest equity contribution from existing investors.
When the transaction closed, Dad called.
“They barely needed your money.”
I smiled.
“That’s the point.”
“I know.”
He sounded proud.
Not of me.
Of the company.
That mattered more.
Several months later, we held an annual shareholder meeting in the same conference room where Vanessa had stopped me in the hallway.
The flowers were gone.
Laura had banned decorative centerpieces because they blocked sightlines.
Mom complained about it once and then gave up.
The table had fewer leather portfolios and more actual operating reports.
I arrived five minutes early.
Vanessa was already there.
She looked up.
“Morning.”
“Morning.”
I chose a seat halfway down the table.
She pointed toward the head.
“Aren’t you sitting there?”
“No.”
“You own the majority.”
“Aaron runs the meeting.”
She looked almost amused.
“Three years ago you would have killed to sit there.”
“No.”
I thought about it.
“Three years ago I wanted everyone to know I could.”
“That’s worse.”
“Probably.”
She smiled.
Then slid a coffee toward me.
“Black. No sugar.”
“You remembered.”
“I’ve known you thirty-seven years.”
“Could’ve fooled me.”
She winced.
I immediately regretted it.
Then she surprised me.
“Fair.”
We sat quietly until the others arrived.
That was our relationship.
Not erased.
Recalibrated.
During the meeting, Lucy’s school project came up because the company had decided to create a small archive documenting Hartwell’s history for employees.
Vanessa wanted to include Grandpa’s handwritten note to me.
I shook my head.
“That’s personal.”
Dad disagreed.
“It says what the company needs.”
Use these wisely. Build something real.
Eventually I allowed a copy.
The original stayed in my office.
Beside it, I added another photograph.
Not of me signing the restructuring.
Not the investor reveal.
Not the new headquarters.
A factory-floor picture taken six months after Aaron became CEO.
Richard in safety glasses.
Vanessa beside an engineer.
Dad talking to a machinist.
Aaron laughing at something outside the frame.
No one posed.
No one at the center.
That became my favorite Hartwell photograph.
For most of my life, I believed my family underestimated me.
That was true.
What took longer to understand was how much energy I spent arranging my life around their mistake.
Every achievement became evidence.
Every investment became an argument.
Every quiet success carried an invisible sentence beneath it:
See?
See what you missed?
See what I am?
Hart Capital was real whether my mother understood it or not.
My work mattered before Vanessa learned the size of the fund.
My grandfather’s shares belonged to me before Dad accepted that I knew what to do with them.
I did not become valuable in that conference room.
They simply lost the ability to pretend otherwise.
That distinction changed everything.
I still have the first Hartwell stock certificate Grandpa gave me.
It hangs behind my desk in a plain black frame.
Visitors sometimes assume I display it because it marks the beginning of my control of the company.
They are wrong.
The certificate represents something simpler.
One person saw me early.
Not perfectly.
Nobody does.
But enough.
He saw that I asked questions.
That I listened longer than people expected.
That I cared more about how a business worked than how important the people running it looked.
He gave me ownership before I had done anything impressive enough to earn a family speech.
That may have been the greatest gift.
Not the equity.
The assumption that I would become someone capable of using it.
I spent years trying to force everyone else to offer me the same faith.
Eventually I stopped.
People reveal themselves through attention.
Through questions.
Through what they assume when you are quiet.
Through the stories they tell about you when they think you cannot hear them.
My family revealed plenty in that glass conference room.
So did I.
They revealed how easily affection can become hierarchy.
I revealed how easily hurt can become secrecy.
They mistook visible leadership for value.
I mistook being underestimated for permission to stop communicating.
They planned around capital they did not understand.
I let my resentment become part of an investment strategy.
None of us left untouched.
That is probably why Hartwell survived.
Not because one hidden investor finally took control.
Because eventually enough people became willing to stop protecting the story that made them look best.
Dad stopped needing to be indispensable.
Vanessa stopped needing to be the golden child.
Richard stopped pretending family politics were normal management.
Mom stopped treating attention like a prize one daughter could win.
I stopped needing my success to function as a rebuttal.
Even Marcus, who had once warned them about the mystery investor, told me years later over dinner:
“The funniest part is I spent months wondering what Hart Capital wanted.”
“What did you decide?”
“That you wanted the same thing every serious investor wants.”
“Returns?”
He shook his head.
“Reality.”
I laughed.
“Returns help.”
He raised his glass.
“Reality first.”
He was right.
The morning Vanessa stopped me outside that conference room, I thought the story was about exclusion.
Then I thought it was about money.
Then ownership.
Then revenge.
It was never really about any of those things.
It was about reality.
My family believed Hartwell’s success came from leadership they could see.
They did not see the capital underneath it.
They believed my life was small because I did not display it.
They believed my grandfather’s shares mattered less in my hands because I worked outside the company.
I believed revealing the truth would finally settle every old question.
It did not.
Truth rarely settles things that neatly.
It simply removes the excuse to keep lying.
Years later, when new executives join Hartwell, someone eventually tells them a shortened version of the family story.
They usually get it wrong.
Jordan secretly owned the company.
Not exactly.
Jordan saved Hartwell.
Too simple.
Jordan took over after being insulted.
Technically, but not the point.
One young finance manager once asked me directly.
“What actually happened?”
We were standing near the coffee machine after a board meeting.
I considered giving him the safe corporate answer.
Then I remembered Grandpa.
Ask the real question.
So I said:
“My family thought I was irrelevant. I let them think it for too long. Meanwhile, the investment firm I built became their biggest capital partner. When the gap between those two realities finally became impossible to maintain, we had to decide whether we wanted to keep acting like a family business or become a professionally governed company owned by a family.”
He thought about that.
“Which did you choose?”
“The second.”
“Was it worth it?”
I looked through the glass wall toward the conference room.
Dad was inside arguing with Aaron about a customer he believed we should never stop serving.
Vanessa was laughing at something Laura said.
Richard had a production report open.
No flowers.
No theater.
Just work.
“Yes,” I said.
“Mostly.”
The finance manager smiled.
“That sounds complicated.”
“It is.”
I picked up my coffee.
“Most real things are.”
I walked back into the conference room.
This time, no one stopped me at the door.